google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: AIM

  • Shots Fired. AnewFN v ADVFN

    Shots Fired. AnewFN v ADVFN


    The ousted founder of ADVFN, Clem Chambers is back with a bold new venture: www.Anewfn.com The pending launch comes on the heels of significant turmoil at ADVFN, where new management has been criticized for its handling of the platform, leading to a dramatic decline in share price and business performance.
    The nosedive in ADVFN value since the change of management is eye watering. They’ve taken a profitable venture and inflicted a catastrophic drop in sales, which in turn has lead to value destruction. The share price has plummeted from over 80p reaching lows just above 10p, and currently hovers in-between 17p/18.50p. The forthcoming year-end accounts will no doubt reveal more ‘troubling figures’, Mired in expensive legal acrimony with the former BOD is in itself an indication of ‘fumbling in the dark for excuses’ it undermines faith in ADVFN’s ability to recover.

    In response to these challenges, Chambers and his team have decided to embark on a new journey by creating www.AnewFN.com This platform aims to fill the void left by ADVFN’s decline, offering innovative features with a fresh approach to financial information. The OBC team, which founded ADVFN and operated it successfully for two decades, are poised to leverage their experience to create a platform that caters specifically for the needs of private investors.
    Chambers, rumoured to now be operating out of Estonia, believes that there is a solid audience waiting to be served, with significant revenue growth opportunities. Their vision is to revolutionize the financial information landscape once again, leveling the playing field for individual investors. 

    The creation of AnewFN is a serious threat in the space that ADVFN occupies..

    Amit Tauman
    Super Computer Intelligence

    ADVFN’s new kid on the block, CEO Amit Tauman, needs to pull his ‘mathematical fingers’ out of his ‘machine learning arse’. Tauman has what I’d describe as ‘Super Computer Intelligence’. He really is Academia Illuminati, with more degrees than a compass, make no mistake the kid is a genius, however in the real world of business and finance, especially on the wild west casino that is the AIM, it’s his ability to assimilate that intelligence with the reality of the sector and business space that ADVFN inhabit that ultimately will decide its fate. Shareholders and users of ADVFN are the life blood of the company, failure to engage, specifically ‘In Person’ by the whole board is endemic. That, among much more, needs to be addressed. 

    Users have noted a lack of meaningful development on the site. Beyond some cosmetic changes, the platform has seen a decay in its features and a deterioration in the quality of service that once distinguished it in the financial sector. It appears that the new team has taken ADVFN to a new level marked by reduced functionality and a failing business model. Their investment threads are awash with rebellious complaints.
    I’ve always had a soft spot for the platform and actually was co founder of the Jekyll & Hyde tip sheet in Jan’ 2017. A quick scan of the page reveals not one change in graphics since launch. The actual video with me in it is still there, while the banner declaring me as MR Hyde is emblazoned for all to see. I am not Mr Hyde.  That’s minor, I know, but it’s indicative of the general malaise in graphics, functionality and Board engagement with their base.
    As they prepare for the launch, Chambers invites early users and shareholders to sign up for exclusive access and updates. By visiting www.anewfn.com, interested parties can leave their email addresses to stay informed about the platform’s development and participate in special offerings. I signed up 3 weeks ago. Here’s a tip from ‘retired’ Mr Hyde: If anyone from ADVFN SIGNS UP then don’t forget to change your IP and use a ‘jenk’ email.

    Additionally, the OBC team plans to rebrand itself as Online PLC, distancing from the controversial associations of blockchain technology in the UK. While they remain supporters of blockchain, their focus has shifted towards building a premier financial website that prioritizes user experience and quality service. There are ‘Rumours’ of a NOMAD sourced for AnewFN with an investor pot of up to £25M. Time will tell… But It’s going to get spicey….

    Conclusion: Chambers v Tauman

    www.Anewfn.com Could represent a potential turning point for the market. As ADVFN struggles under itsWe really are trying hard despite sales new management, can AnewFN rise to challenge and surpass it, offering an alternative fit for use and user friendly financial site for private investors? Or can Tauman finally get his Board up to speed and on message taking a grip of ADVFN, pushing the SP upwards?
    Let battle commence.

    Viva

    Dan

    x


  • Reabold Resources ‘Project Wallace’

    Reabold Resources ‘Project Wallace’

    Tip: I often see and hear this: "Know The Game". Let me tell you something, anyone who consistently espouses this shite is 'at the bollox'. Investing/trading at any level isn't a 'game'. It's deadly serious. Those that tweet, podcast or write such shite are in the main Pump & Dumpers, who'll say and do anything to manipulate small cap' micro stocks. Using a whole host of anonymous twitter, BB accounts, DMs, Private chat, phone calls and email groups. It's easy to ramp telling 'porky pies' about crap companies you're taking kickbacks from or dumping shares into the ramp. Silence is better than bullshit.

    What isn't easy is getting your hands on quality information. Base your strategy on well sourced information. Remember losing several thousand pounds for most of us has financial consequences. Rather than know the 'game' 'Know Their Game'. Here endeth the lesson...

    There’s no a hard & fast rule, in the not so glittery world of financial commentary, but occasionally one has to make a ‘judgement call’ in the interests of transparency for shareholders, traders and investors who’re all too often kept in the dark, when really companies should be reaching out to their shareholder base and the wider market, instead of skulking around behind the ‘corporate curtain’, raising cash. 
    Some financial placings actually have merit and one, if given the chance, can see the raison d’être or not. Which brings me on nicely to “Project Wallace”. Documents now in my possession confirm that Reabold Resources (LON: RBD) basically think that they’ve hit the ‘Oil Jackpot’ at the West Newton drill site.

    Project Wallace is the corporate (Stifel) Institutional overview/pitch of all licences held by Reabold, with summary’s pertaining to each of their licence holdings: Reabold California (USA), Rathlin/West Newton (UK),  Danube Romania,  Corallian (UK)


    For the purposes of this blog post I’m specifically concentrating on the West Newton/Rathlin transaction that can be summed up as thus: “$29m investment for $274.4m of additional value” which doesn’t take into account the potential value/oil from the Cadeby oil play which has a further value of $850m NPV (gross). The proposed placing price was 1.2p. That may have changed post the ShareProphets scoop and RNS confirmation. We’ll know soon enough. For those of you who wish to read the complete unabridged Stifel overview there’s a ‘Click Me’ button at the bottom of this post.

    It’s glaringly apparent that RBD and their partners believe that West Newton is a major onshore oil/gas discovery that will flow oil & gas and could net well in excess of $1,000,000,000 at $11.50c net back based upon as yet the unpublished CPR and the volume-metrics that will soon be released. The Extended Well Test is due Q4 2019, which means West Newton is gearing up, news should start to drop next few weeks or so….

    To me it looks to be the ‘real deal’ based upon what’s been going on behind closed doors however ‘Caveat Emptor’ always applies. It’s not in the bag until it’s in the bag. RBD will be fully funded with an increase in West Newton which is basically their crown jewels. UJO are already fully paid up for the EWT and have £2,600,000 cash at hand, they’ll probably sell out after the oil/gas flows. It’s known that Bramhill (CEO UJO) has consistently rebuffed offers of financial backing from several institutions.

    So, how much O&G is there? We’ll get an idea once the CPR/Volume metrics are released which should come pre EWT. A 65 metre hydrocarbon column in the Kirkham Abbey is in itself a company maker. Add in the Cadeby and it’s probably the best O&G play on the London Stock Exchange. Especially since all the Major holders have all basically ‘sold off’. That brake has gone. Expect TR1s with the inevitable deceitful ones double speaking trying to talk both companies down. Par for the course, i’m afraid.

    Once oil/gas flows at West Newton then RBD could hit in excess of 5p and UJO anything up too 2p. Of course it’ll be a bumpy ride with many peaks and troughs but that’s again ‘par for the course’ in the Oil Sector. So, now we ALL know the facts on West Newton and the proverbial playing field has been levelled. Courtesy of Dan! The Man! Whose got no hair but doesn’t care LOL!
    Good Luck


    Viva!


    Dan

  • Ascent Resources. Death By A 1,000 Cuts (Placings). Another Massive Discounted Placing On The Way!

    Ascent Resources. Death By A 1,000 Cuts (Placings). Another Massive Discounted Placing On The Way!

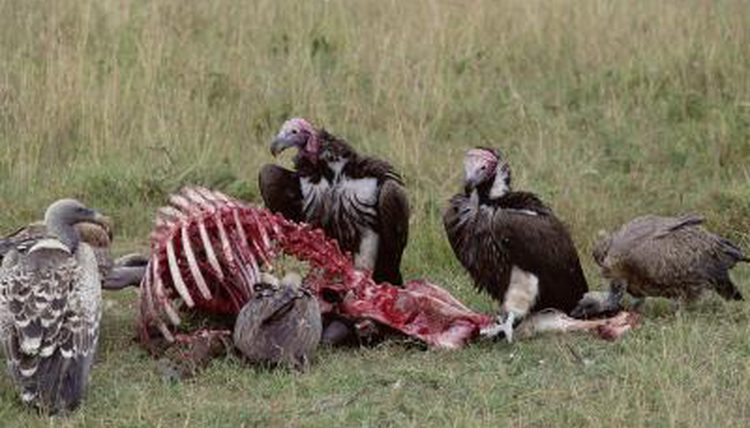
    Vultures now feeding.

    Ascent Resources (LON: AST) Yesterday plunged the knife yet again into their own shareholders via a huge discounted placing raising a piss poor £750,000. The last placing they tried was with Primary Bid ‘in the bolloxs which failed to flog the full allotment, of yet again, hugely discounted shares hence why the residual shares that Primary Bid couldn’t sell were off-loaded yesterday to yet more so called ‘Institutional’ investors. This is a bare-faced lie.

    There are no ‘Institutions’ investing in Ascent. Just as in the Henderson Global, Darwin Strategic, Lombard days of chicanery, so called Institutional Investors. And we all know exactly where these Institutions are right now. Gone, vamoosh, scarpered with the loot after selling off all their heavily discounted shares leaving you the mug punters holding the CONfetti.

    Gobshite Taking Cash To Ramp

    Ascent has now hit rock bottom and is having to use ‘bottom feeder’ bucket shop finance. The new improved ‘Institutional Investors’ are in actual fact a small group of well known ‘Vulture’, one man band corporate flippers. Who will be ramping to fook on twitter, Total Market Shite, ‘Gone for a Burton’ and various BB threads under anonymous names. My sources tell me that one of the flippers is planning to flip out every time he’s showing a 15%-20% gain. I could name that individual but it would compromise a source. But he’s a well known corporate shyster who works in cahoots with twitter cowboys and is a chum of the under investigation First Equity Broker Mr Miles ‘Vulture’ McNulty who recently ‘dearly departed’ from twitter due to said investigation….

    Ascent are embroiled in a costly legal dispute with the Slovenian Government, have piss poor deteriorating production that needs several million in capex spunking away every year on top of huge corporate overheads. The business isn’t viable. Come the Ascent Resources AGM, the Articles Of Association will be changed to allow Hutchinson to issue an unfettered amount of shares below ‘par value’. This is going to result in massive, and I mean massive dilution with a consolidation of shares in issue. Funnily enough round about the time ALL the corporate flippers will have sold all their discounted stock back to the mug punters. If you hold this stock for any length of time you are going to be wiped out. The Board have a history of not giving a flying fook about their shareholders. It’s all about keeping the lights on via whatever finance they can get.

    New Improved ‘Institutional Investors’

    Now we all know that CEO Colin Hutchinson, was left holding the entrails of the AST corpse after Clive Carver & Co jumped the sinking ship, (pockets filled with pay & expenses leaving him to wind down the company) has to raise money to survive otherwise it’s lights off and good night Vienna but when CEOs deliberately masquerade Corporate flippers as ‘Institutional Investors’ knowing full well that they will deliberately pump & dump to the detriment of genuine long suffering share-holders then it is time for shareholders to sell up and move on, particularly when the fundamentals are as shocking as Ascents. The next placing in Ascent Resources is already being planned by their newly installed joint broker SP Angel it will come post AGM. Of course they’ll now deny it till blue in the face and they’ll try to drag it out for as long as they can. But my source is within SP Angel and has confirmed that they were taken on specifically to assist in another cash raise post AGM. So expect more horse-shit RNS’s to artificially raise the SP.

    I wont go into the cash raised pre Jan’ 2017. Otherwise I’d be here all day! Suffice it to say that AST has spunked away circa £40,000,000 pre 2017. Since January 2017 Ascent resources has raised £14,235,271. 2017 & 2018 production generated circa £2M in revenue. Production has steadily fallen. Last figure was circa £35K for March 2019. Down from an initial high of circa £200k per month.

    Failure

    Ascent resources has basically spent £7,000,000 per year to generate circa £1M. As a business that is unsustainable. Which is why Hutchinson is now grabbing low level bottom feeder finance. The Petisovci gas field is in terminal decline. It needs, and will always need, expensive workovers to deliver small gas. The Capex by far out-stretches the revenues generated which is why during the Strategic Review no fooker would touch it. It’s production will never get into the black. In what business would you invest £7,000,000 per year to make £1M? The talk of ‘Workovers’ is very apt here. It’s you the AST shareholders who are and will continue to be worked-over by Ascent Resources. Production has all but ground to a halt and the cash-burn will have to increase. Enter the latest batch of corporate shyster finance.

    Talk of a new direction and new assets is a ‘Jackanory’, a white elephant. There’s no money for new assets. It’s a fig leaf to lessen the disaster that is the Petisovci field and the continual rape of UK Investors. This is only going one of two ways and that is administration/delisting or another team comes in and wipes out (again) share holders while heralding a new dawn…. We’ve all seen it many, many times. It never ends well.

    Get out and stay out!

    Viva

    Dan

  • Nostra Terra Oil & Gas. Fraud with a capital ‘F’. ‘Gone for a Burton’.

    Nostra Terra Oil & Gas. Fraud with a capital ‘F’. ‘Gone for a Burton’.

    Investors really need to take note of the lies and deceits of the well known fraudster and liar running the scam that is Nostra Terra Oil & Gas ((LON: NTOG). I’ve high-lighted this POS many times and each and every time I have been correct. Two weeks ago the Ex Estate Agent Mormon shyster, (Twat) Matt Lofgran, was running around with that other well known shyster outfit Total Market Shite (TMS) telling all & sundry that they would not be raising money and didn’t need too. While at the same time organising another placing. This was tweeted, posted and cowboy-casted out over all the financial platforms by the paid P&Ders.

    Lies, Lies & More Lies….
    Total Market Shite! Strikes Again!

    Total Market Shite is the brain-child of one Mr David Burton, who was booted out of Vox Markets, when they decided to clean up their act severing all ties with him & the P&Ders he’d introduced to the Vox platform. Now that’s fact. So it should be no surprise that TMS and the Burton Pump & Dump crew all found comfort together again taking payments from shyster companies, like Nostra.

    Misleading investors into proven shite companies, taking backhanders, trading the stock while heavily promoting company changing events is nothing new. The best way to think of it is as a bit like the ‘Time Share’ scam. Suckers get sucked in, fed horse-shite, part with cash. Leave with a head full of magic clutching worthless timeshares, then get wiped out. It’s only after the event reality bites. The scam moves on focusing on the next set of suckers. Rinse repeat ad-infinitum.

    The Crook Of Mormon.

    The simple truth on Nostra is as plain as the nose on your face. Lofgran has raped, lied & deceived gullible investors in the company for 10yrs. He’s wasted tens of millions of your cash. It’s had more bullshit assets, trumpeted as company changing plays than you’ve had hot dinners. RNS’s galore, Placings galore, Consolidations galore, Dilution galore. Debt galore, Assets galore. Production has never ever covered costs. It’s stripper well production. Marginal, exhausted fields/wells bought for a few thousand dollars to ‘Flesh out’ the ‘Jackanory’ are never going to transform a company. It’s cash burn out-strips it’s highly costly minimal stripper well production. It will always dilute and place to raise cash because there’s always debt. Here’s a prediction. Shares in issue will yet again double from where they are now. Then they’ll double again eventually breaching one billion etc. etc. etc. That’s the ‘Modus-Operandi’. Rinse repeat Mug Punters and always keep changing the ‘Jackanory’.

    Take some advice all you ADVFN/LSE/III Posters. Walk away there are plenty of decent oilers out there. This isn’t one of them. It’s a Fraud with a capital ‘F’.

    If you had invested £100,000 in Lofgran on day one of his tenure then you would have less than £100. You put money into NTOG then you will ultimately lose the lot. It’s run by a liar who shorts his own company and will carry on diluting and placing until you’re all ‘Gone for a Burton’.

    Work it out!

    Viva! Dan
  • Online Blockchain. It’s all coming together. I Buy for the Boom!

    Online Blockchain. It’s all coming together. I Buy for the Boom!


    Online Blockchain have been quietly going about their business and news has been and is being dampened down, particularly on their mining operation and the on-going negotiations that are always just an RNS away, there are deal/s in negotiations. Such as the Gibraltar Stock Exchange negotiations that were never RNS’d. OK that deal didn’t complete but somewhere along the line a big deal will come off. That is why I hold this stock.

    It’s already spiked to £1.85p. And it will no doubt surpass this as the crypto nerds focus in on OBC. (Oil & Gas traders don’t understand this market and should stay away).What those deals are will become apparent IF they’re signed up. Remember, the Chambers ethos is that only ‘signed deals’ are RNS’d, negotiations are not disclosed. (More of which I’ll go into later in this blog).

    OBC have now launched five crypto-coins. Buenos, Brazio, Manila, Veggie and the original Plus1 Coin. What most investors haven’t realised is that those five crypto currencies are seeds and look set to net OBC circa $1,000,000+ in Bitcoin forked coins over the next year or so. Each crypto, before it’s launch, is pre-mined. That’s to say that up to 20% of each coin is mined by OBC. I know that Buenos, Brazio Veggie and Manila coins were pre-mined. Now here’s an accountant’s question. Plus1coin has a MC of $250k. So hypothetically now there’s a $50k crypto currency asset. When it goes to $1M that’s $200k. That scenario is the same for each coin that OBC launch.

    Like all seeds time is the key. Bitcoin took 8-9 years before it spiked at $20,000 per coin. It’s now $6,000 per coin. The secret of crypto coins is to create a use for the coin. Each of the OBC coins has a user case. Therein lies the development cycle to the increase in value. Each Crypto currency has its own unique development cycle which can take time to work through. You must launch a Crypto that has a use, such as the Brazio coin, that’s been developed for the Brazilian capital markets and each Crypto has a wallet that brings revenue into the company. The more it’s mined the more they make. The Brazio Coin has only recently been released on the Brazilian market and is now tradeable on the Brazilian Crypto Hub Exchange.

    Now it has been quite some time since I updated on Online Blockchain (LON: OBC). That’s because information is hard to come across as the Board run a very tight-ship, for reasons best known to most of the quality disruptive techno’ companies they navigate carefully around the City of London, not wanting to draw the attention of the regulators and banks etc. That’s because this technology, Blockchain, is slowly creeping into the financial markets. People and industries especially the Financial industries are nervous about protecting the hegemony that is being slowly eroded.

    As for the deals and the way forward for OBC I do know that there’s certain pointers I use, whispers of negoiations, Coin launches, Wallets, Revenue, Warrant exercises, Hash rates etc. One such whisper is that they may have been approached to launch on the Canadian market. That’s important. If OBC take a listing in Canada (TSXV) then this SP will go through the roof, again. Why? Because Canada has two sectors that are world leading, one is Medicinal ‘Weed’ the other is Blockchain/Crypto. The Blockchain companies listed in Canada do so because the Canadian Investors are the most ‘savvy’ in that global sector. The UK Crypto/Blockchain Investor/writer really doesn’t exist. It’s a ‘Hodge Podge’ of traders/bloggers and ne’er-do-wells. People who don’t understand how the sector works and why it’s so boomtastic. I recently had a ‘JawJaw’ with a certain well-known financial writer, who admitted he knew fook all about ‘Blockchain and disruptive tech’. That hasn’t stopped the self-confessed ‘dilettante’ from opining on OBC. Lot of dis-information has been spewed out on the Chambers Crypto/Blockchain play. From people who admit they don’t have a ‘Scooby Doo’ about the tech’. Their ignorance has been my gain. I now hold circa 100,000 shares. I await the boom and boom it will…..

    At the time of writing the SP is circa 40p. That’s the basic reflection of the fundamentals but not of their potential to multi-bag on any given RNS.

    Get researching and use the opportunity to learn. It’s better to be in front of the Blockchain wave instead of chasing it.

    Hold for news. My spider senses are tingling. News will come.


    Viva


    Dan


  • One Last Big Push! Woodlarks Charity Walk! Come On! Support This Wonderful Charity.  #KARMA Will Reward You!

    One Last Big Push! Woodlarks Charity Walk! Come On! Support This Wonderful Charity. #KARMA Will Reward You!

    Woodlarks Camp SiteOn Saturday 28th July I take on the mammoth task of hiking 33 miles over the South Downs from the Gatwick Gusher that never gushed to Woodlarks camp site for the disabled with my fellow bloggers and erstwhile comrades Lucien Miers & Tom Winnifrith. I had been training extremely hard but as always life doesn’t deal from a straight deck. My training has been somewhat set back by personal family crises as has my correspondence, meetings and email. As for the telephone well, I’ve rarely answered calls because most of the time it’s been in-appropriate to do so. Even though I don’t like hospitals, chapels of rest or churches for that matter. (They are places of pain & sorrow) I do respect them and answering a mobile umpteen times a day at either of them isn’t the done thing. If you still haven’t donated or are thinking of supporting this super off the radar Great British charity then Click Here

    As some of you may, or may not, be aware life can kick you in the teeth and the ‘House of Levi’ has had several hard kicks in the face, of late. The last ten days has been difficult, not on the share front but on an emotional level. Two sisters in critical care within days of one another has sent me & the family into overdrive, as the clan, dispersed through-out the UK, Eire, USA & beyond, gathered for what was in all likelihood a double funeral…. Suffice it to say that one is slowly recovering, while one has passed away.

    Annette was my disabled sister who had been wheel chair bound for over 3 years. I was very close to her, being one of the only people who never gave up on me while I was at Her Majesty’s hotels for the criminally minded….  So, it’s with her memory in mind that I will, ‘come hell or high water’ walk 33 miles for the greater good that is the Woodlarks charity camp site for the disabled. A strange twist of fate, that isn’t lost upon me.Image may contain: 3 people, outdoor and closeup

    Now I know that you lot are a hard bunch to convince when it comes to parting with money. As an example I got an email yesterday that stated the walk was a ‘conjob’ & me and TW would be ‘divyng up the cash’ between ourselves….. Just what makes people come out with such ludicrous, malicious statements is more a testament to their mind-set than 3 guys and ALL the traders/investors/companies who’ve supported/donated their hard earned cash to help children/adults who’ve been dealt a shitty hand in life. Each and everyone of you should be quietly proud of what you’ve collectively achieved here! For it is you that has made the charity walk a success.

    Our target of £20,000 is stunningly close. To say I am over-whelmed by the generosity & humanity of those who have helped, regardless of how big or small the donation, or their personal peccadillos on myself, is an under-statement. I know Tom & Lucien have been going all out to get this over the line, while I have been coming to terms with the loss of Annette.

    Now that I’m nearly back on emotional track, having had a shave, wash, a good meal and several teary moments, if there’s any one out there who has been wavering on donating then do try and help us get this to its target, it’s all good Karma. And make no mistake it will come back many fold on judgement day. It could quite literally save your soul and tip the balance that opens the gates to paradise for yourselves. I myself will not be entering paradise, being black-balled from a very early age, so there’s no worries on that score. HELP HERE


    Many thanks to all who’ve supported thus far. It’s time to give yourself a pat on the back.


    Dan

    x


  • Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

    Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

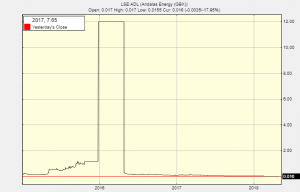
    Today yet again we have ‘yet again’ another scandalous placing & acquisition RNS and a Board change RNS from the corporate crooks who run Andalas Energy & Power (LON: ADL). Make no mistake these fookers are running true to form. The RNS’s contain blatant lies. Which I will expose further down in this ‘Epistle to the Morons’.

    Mug Retail Punters woke up this morning to yet more horse-shit via the bush-tucker system. I say ‘Bush-Tucker‘ for good reason as my sources, who are 100%, have kept me informed on #ADL at every twist & turn. More of why I’m using an Aussie term further down in the blog…

    What is happening at Andalas Energy? Well I’ll expose it and expose it in full! Today’s Placing/Acquisition wasn’t news to me as I already knew months ago about the new asset and knew on Thursday/Friday that the joint cunts, Novum & Optiva were lining up a placing. Sadly I only had 2 sources. (The BMD rule on solid info is that I have to get at least 3 separate sources unconnected with each other before I run an article.)

    RNS LIES

    Investors who are currently holding ADL stock are in for a wipe-out via a massive share consolidation and another placing. Todays RNS’s contain blatant lies. Gorringe has stated; “Indonesia offers significant potential and we remain committed to our existing projects and strategy there”.  This is a blatant lie.

    As is this; “On behalf of the board, I would like to extend our thanks to David (Whitby) for his service to the Company, he brought passion for Indonesia to Andalas and we wish him well in his future endeavours.” 

    New Name. New Asset. New BOD. Consolidation & Wipe-Out. Rinse Repeat!

    David Whitby, outgoing Chairman, said “I am proud of what the team has achieved in Indonesia, whilst the Company has not done enough to show the market that the foundations built over the past few years will generate shareholder value, I am confident that I leave the Company full of opportunity. I wish the team and shareholders all the best as Andalas executes its new focused strategy, which has the potential to make 2018 a significant and exciting year for all involved.”

    For a company to opine such blatant shite in an RNS is testament to how detached from reality they have become from their share-holders. There is no shareholder out there who, hand on heart, would agree with the utter shite above! Whitby and Gorringe have decimated ADL and raped it since day one with a series of worthless paper deals. Not one therm of gas or drop of oil has been produced, yet tens of millions of pounds have been fleeced out of UK investors. They’re now being paid off to fuck off. For Whitby or indeed any of the sad sack of shit that run this company, to state such utter bolloxs gives away exactly how they see shareholders. Gullible fools bent over & willing to be repeatedly financially sodomised, with the help of the likes of BigGob, Bellcunti & the Gunslinger a.k.a Doc Holiday etc. You’ll all remember them with their incessant ‘Share of The Year’ shysterism…

    SHADOW DIRECTING

    Those who are basically shadow directing ADL have no intention whatsoever of progressing Indonesian assets because they know they’re paper assets and worthless. The plan which is being shadow directed by Paul Hayward (Block Energy) Novum brokers Colin Rowbury, James Sheehan & Optivas Christian Dennis, (you may recall some of those names as these were the people who installed the crooked Whitby crew (and kept it going) at the beginning of this long, sad, tortuous tale and what a tale it has turned into) is to reinvent ADL and slowly flip out the majority of the board quietly over a period of months, bring in new blood, while at the same time changing the company’s name, employing professional PR/IR and changing the emphasis/direction of the company. Hence the new asset…. It is a reinvention of the wheel, a passing on of the ‘cash cow’ that allows those at the pigs trough to keep feeding and filling their pockets.

    And pray tell just where in the name of God are ADL going to get their 14.75% share of an offshore drill in the North-Sea for the Licence P2112 ? The cost of which is up to circa £50,000,000 sterling…. It cannot be done unless they jettison the entire Board of ADL and run away from Indonesia and wipe out existing shareholders via a massive Consolidation and placing and that folks is exactly what those shadow directing this POS are about to do!

    As for the rest of  Licence P2112 who is going to come in? My sources are telling me that, that other super sodomiser of UK Retail Mug Punters, Solo Oil & Gas (LON: SOLO) are also in discussions with Eagle Gas LTD. And we all know who really has their fat sticky ‘didgeridoos’ in SOLO. Come on down the fat Aussie Liar and corporate conman His Excellency ‘LordLieAlot’ take a bow David Lenigas!


    Wipe-Out on the way ADL!


    Have a Good Day Cobbers!


    Viva!


    Dan

  • Breaking News! Beaufort Securities. PWC Confidential Letter To Clients!! The Gory Details….. In Full!!!

    Breaking News! Beaufort Securities. PWC Confidential Letter To Clients!! The Gory Details….. In Full!!!

    Further update on client recoveries and distribution,
    client data notifications (GDPR) and cessation
    of ISA manager status
    Private & Confidential

    To the Firms’ clients

    Dear Sir/Madam,

    Beaufort Securities Limited (“BSL”) in administration; and
    Beaufort Asset Clearing Services Limited (“BACSL”) in special administration
    (together the “Firm(s)” and the “administrations”)

    We are writing further to our notification of appointment of the joint administrators dated 15 March 2018, in order to provide a more substantive update on the work we have been undertaking, the preliminary conclusions that we have reached and how we currently envisage being able to commence distributions to clients.

    Events leading up to the Firms’ cessation of trade

    Due to the circumstances surrounding the insolvency of the Firms, the appointment of the joint administrators occurred with very limited notice, which was unavoidable. Consequently, there was no time to make any plans as to how the disruption to clients might be minimised and the return of client assets could be expedited. As clients will be aware, BSL was (alongside certain other parties) charged with securities fraud in the United States of America. The Financial Conduct Authority (“FCA”) had also imposed various regulatory restrictions including a prohibition on all investment activity immediately prior to the Firms’ insolvencies.

    Prior to the administrations, the Firms had submitted to the FCA, on a routine basis, various regulatory confirmations regarding the status, quantity and amounts of client money and client assets held by BACSL. We have examined these regulatory confirmations and they have provided an important starting point for the joint administrators to review and assess the sufficiency of the client money and assets held for clients as compared with what is owed to them. They do highlight some relatively modest deficiencies in both client money and client assets. The Firms had, however, sometime previously switched over to a new accounting and record keeping system. These issues, together with the complex nature of the administrations, may create further challenges in the tasks ahead of returning client money and assets to clients.

    Steps taken immediately following the joint administrators’ appointment

    Immediately upon our appointment, as we have previously advised, we took steps to safeguard the Firms’ data and systems as well as their assets (those held for clients and their own). We have materially reduced the scale of the Firms’ operations and brought in relevant experts to assist us in the conduct of the administrations.

    We have also secured funding to ensure that all critical operations can be maintained in order to facilitate the return of client money and assets, in accordance with the proposed courses of action set out below.

    Preliminary conclusions

    We have carried out a full assessment of the Firms’ records, which enables us to reach the following preliminary conclusions:

      • in the absence of a surplus of funds within the Firms’ segregated resources and in accordance with governing legislation, relevant costs will need to be deducted from clients’ entitlements to client money and client assets.
      • client money and client assets were, as at the date of administration, substantially complete save for a very small number of isolated deficiencies.
      • a large number of the client securities are made up of illiquid or potentially nil value positions which will complicate the basis upon which costs may be levied against them.
      • in view of the issues identified, we have reluctantly ruled out an expedited return of assets without the statutory protection offered to clients and the joint administrators through a formal bar date and distribution plan.
      • a distribution plan is being developed (see below) as a matter of urgency and a realistic timeframe to commence returns for the majority of clients will be September 2018 at the earliest.
      • the FSCS will aim to make compensation payments to a client population who had only small client money balances with BACSL during May 2018.
      • the basis of allocating costs is also being developed and is likely to be levied by reference to value of the client portfolio and charged on a sliding scale (so that higher value portfolios will contribute more in absolute terms but proportionately less of the overall value of their portfolio of client money and client assets).
      • with a majority of clients likely to be eligible for Financial Services Compensation Scheme (“FSCS”) compensation with shortfalls and costs falling within the £50,000 compensation limit, we believe the substantial majority of clients will recover their portfolios in full in due course.
      • we do, however, estimate around 700 clients with client money and client assets together valued in excess of approximately £150,000 may experience a loss on their entitlements in excess of the FSCS’s £50,000 compensation limit.
    • clients who do not fulfil the FSCS eligibility criteria will not be entitled to receive FSCS compensation and will, regrettably, face a loss on their client money and assets.

    Revised estimate of securities value

    The indicative figures first published as to the value of the securities in the client assets portfolio have now been subjected to an initial independent valuation. This has highlighted a number of important issues, including as noted above the fact that a number of highly illiquid and potentially nil value positions are held. The carrying value used previously was based on a historic price which we do not believe appropriately reflects a more cautiously assessed valuation. The more conservative value for this assessment is in the region of £500 million.

    Corporate actions

    We have put in place new interim arrangements to manage the portfolio of custodied assets for corporate actions arising since our appointment, be this receipt of dividends or otherwise. We will provide an update at a later stage on our plans for dealing with clients’ accruing interests.

    Clients owing funds to the Firms

    A number of clients are indebted to one or both the Firms. Those amounts will need to be collected from the relevant clients as part of the client assets distribution programme referred to below.

    Access to the Firms’ Client Portal

    Shortly after our appointment, we suspended access to the Firms’ online Client Portal. We are in the process of updating the Firms’ records for the work detailed above and making other necessary changes to it. Once these are complete, we will provide access.

    Plans for distribution programme

    FSCS summary and overall client outcome

    Irrespective of the method of allocating costs among clients, it is clear that clients will face shortfalls as a result of the Firm’s insolvency and ensuing special administration. In accordance with applicable legislation, however, we have worked closely with the FSCS and are able to confirm that, where clients have client money and assets held with BACSL with a shortfall (including reserves for costs) of up to a value of £50,000, the FSCS will seek to provide compensation to eligible clients without it being necessary for a claim to be submitted in most cases. Further information on FSCS eligibility is available here: www.fscs.org.uk/what-we-cover/eligibility-rules/.

    Proposed distributions

    We are developing on an urgent basis two strands to an overall programme of distributions:

      • We have worked closely with the FSCS to identify approximately 2,700 BACSL clients who held client money only, each of whose claim is less than £2,000 in value. FSCS will aim to compensate these clients in full during May 2018, without the clients having to submit an application form. No reserves for costs will be deducted in this context. FSCS compensation will compensate these clients in full, and they will have no further claim against the Firm in the special administration. A notification will be sent to qualifying clients separately. This notification will include details of the cash sum to be returned along with limited bank details (if any) and affected clients will have an opportunity to reject the distribution or notify the Firms of any amendments. (Any rejected claims will be deferred for distribution under the distribution plan described below); and
    • A statutory “distribution plan”, pursuant to the applicable insolvency legislation, designed to facilitate the return to clients of the balance of the client money and securities held by BACSL, running alongside a process of returning client money not covered by the distribution referred to above.

    The applicable procedure laid down for the distribution plan by the relevant insolvency legislation entails the joint administrators:

      • Firstly, setting a bar date for claims in respect of securities: That bar date will be set by means of a notice currently expected to be distributed to all clients during May 2018. We presently anticipate that the bar date will be set for some time in June 2018. Under the applicable legislation, the effect of the bar date is that claimants who submit their claims after the bar date are not guaranteed to have their claims taken into account when distributions are effected, albeit the joint administrators will in any event take into account clients’ entitlements insofar as they are reflected in the Firms’ books and records. When notifying clients of the bar date, we will explain how clients can access a portal on the Firms’ website, designed to show clients what the Firms’ books and records show their entitlements to be, so that clients are in a position to submit any corrections or other information or documentation that they consider the joint administrators ought to take into account, prior to the bar date.
      • Secondly, preparing and circulating to clients (and the FCA, among others) a document setting out how they propose to go about returning the client securities in BACSL’s possession: This will be a detailed document and it will take some time to prepare. We set out below some of the substantive features that we currently expect it will have.
      • Thirdly, seeking and obtaining approval of the above document from the creditors’ committee: The joint administrators will be circulating details of an initial meeting of creditors and clients of BACSL. One of the purposes of that meeting is to constitute a committee, made up of creditors and clients of BACSL, which can then represent the wider constituency of creditors and clients during the remaining course of the special administration. It is a requirement of the applicable insolvency legislation that the statutory “distribution plan” be approved by the creditors’ committee, prior to being put into effect. Following the constitution of the creditors’ committee, therefore, there will need to be a meeting of that committee during which the joint administrators’ proposed distribution plan is considered and approved.
    • Fourthly, seeking and obtaining the approval of the above document from the court: It is a requirement of the applicable insolvency legislation that the statutory “distribution plan” be approved by the court, prior to being put into effect. Following the approval by the creditors’ committee of the draft distribution plan, therefore, the joint administrators will need to make an application to court seeking its approval.

    As noted above, the statutory “distribution plan” applies to securities, as opposed to client money. In practice, however, in order to expedite the process of returning clients’ investments (of whatever nature) to them, the joint administrators are planning to deal with client money in parallel with the process for returning client securities. That parallel process will also entail the setting of a bar date and may also involve one or more applications to the court for approval of particular aspects of the process.

    These procedures are important for the following reasons: if cash and/or securities were to be distributed to those clients to whom the Firms’ records indicate they are owed, without these procedures first having been implemented, it is possible that competing claims (not reflected in the Firms’ books and records) could subsequently be asserted by clients or other counterparties of the Firms; and that those asserting such claims might contend that the earlier distributions of securities ought to be disturbed, or that client money already distributed ought to be recovered from the clients to whom they were originally paid, for the purposes of meeting the late claims.

    In the circumstances, a significant advantage to clients that will be secured by the joint administrators following the procedures set out above is that, once clients receive their cash and/or securities from BACSL in accordance with such procedures, the applicable insolvency legislation expressly provides that such distributions cannot be disturbed by late claimants who later assert that they were entitled to share in the relevant stock lines and/or cash pool (e.g. the clients will receive good title to the securities).

    As appears from the above, however, the statutory process is necessarily complex, involving as it does a number of steps, including one or more court applications. There will inevitably be material costs associated with this process and such costs would ordinarily need to be paid for out of client money and assets, though the FSCS may be able to provide compensation in relation to the resulting shortfalls of eligible clients. The complexity, as well as the timeframes specified in the rules themselves, will also mean that there is a certain amount of unavoidable delay associated with the return of cash and securities.

    The joint administrators currently anticipate the statutory “distribution plan”, and their parallel plan for distributing client money in accordance with the applicable rules will involve, among other things:

      • A transfer for clients holding client money (who have not been compensated by FSCS in relation to a small client money balance) and/or client assets up to a certain limit to a nominated regulated broker. We are in the process of identifying a recipient broker and will communicate directly with those clients included within this programme. A client will be able to nominate another new custodian but that may delay the eventual transfer depending on the circumstances at the time. This is a complex exercise to arrange and execute. We anticipate, however, that it may in this way be possible to effect returns to a majority of clients by number and value. We have explored the possibility of effecting such a transfer outside of the statutory process described above (with a view to effecting it more quickly than will be possible within the confines of that process), but we have reluctantly concluded that such is not practicable or, in any event, in the interests of clients, particularly in light of the point made above as regards finality once distributions have been made (i.e. clients receiving good title). As it is, the joint administrators hope that a transfer of this nature may be achievable September 2018 at the earliest.
      • A plan for effecting distributions of all remaining client securities and money, possibly involving further bar dates and/or the liquidation of unclaimed or other client assets. Given that the clients and/or the assets to which this part of the overall plan will apply will be those giving rise to complexities of one kind or another (failing which they would have been included in one of the other methods of return referred to above), it is likely that this part of the process will be time-consuming and therefore the relevant returns to clients will inevitably take place at a later date than those referred to above.
      • A methodology for levying costs against client money and assets and as noted above this is likely to be by reference to value and charged on a sliding scale. Costs will need to be assessed on a prudent (high case basis) and allocated against portfolios valued on a conservative basis. The methodology will need to offer alternatives to avoid assets being sold to settle costs (which may need to be carried out as a last resort) and also set out how any rebate for costs will be returned to clients once the final costs have been settled and value of illiquid and potentially nil valued positions finalised.
    • How the Firms and clients will interact jointly with the FSCS in order to streamline claims for shortfalls arising on their client money and securities interests through costs levies or otherwise.

    Regulatory matters

    We are working closely with the FCA regarding the distribution of client money and assets. All distributions will be subject to the approval of the FCA.

    As part of the above, we will be seeking various “know your client” information and documentation. We shall provide guidance where specific actions on clients’ parts are needed.

    Other claims for compensation

    We are aware of some 700 claims against BSL by clients for compensation in respect of various matters, including poor investment advice. It is possible that further claims will be made and we will (as appropriate) develop a programme for dealing with these in due course. As regards what (if anything) relevant claimants might recover in respect of such claims, we note the following:

      • Distributions (if any) to ordinary creditors of the Firms through the insolvencies are likely to be minimal.
      • Clients of BSL who believe they have a claim for example in relation to negligent advice can submit their claims via the FSCS online portal at www.fscs.org.uk/your-claim/ with any compensation being capped at £50,000 per investor. This is separate from any claim the client may have in relation to a shortfall in client money or assets that were held by BACSL, where there is a separate £50,000 cap per investor and the FSCS will seek to compensate eligible clients without the need for an application to be submitted.
      • Existing claims against BSL being adjudicated by the Financial Ombudsman Service (“FOS”) are expected to be transferred to the FSCS. We understand the FOS is in the process of writing to all affected clients and will need client consent for this transfer to occur.
    • Once the FSCS is in receipt of the files, it will contact affected claimants. If a claim is accepted, the FSCS will pay compensation and will take an assignment of the claimant’s rights against BSL and any third party. This will enable the FSCS to seek recoveries, including from BSL’s Professional Indemnity Insurer, and there is no need for clients to seek their own recovery against the Professional Indemnity Insurer. Any recovery of insurance proceeds is likely to be limited.

    Individual Savings Account (“ISA”) notification

    We set out below formal notification to ISA clients.

    In accordance with the ISA Regulations SI 1998 (No.1870) (the “ISA Regulations”), we are obliged to notify you that BACSL has ceased to qualify as an ISA Manager effective from 1st March 2018.

    Ordinarily, individual ISA account holders are required to transfer their account to another ISA manager within 30 days of this letter to preserve the ISA status of their assets. However, having regard to BACSL’s special administration, HMRC have agreed to relax such a deadline in order to preserve ISA status. You therefore do not need to take any action at this time.

    As soon as any client money and client assets are ready to be returned to you, you should be able to validly transfer your ISAs to another account manager, but only after the joint administrators have quantified all of the assets held by BACSL, and the FCA have authorised the transfer of such assets. Further information will be provided shortly.

    On commencement of the new tax year, 6 April 2018, you should be able to open and pay into a new ISA with a different ISA manager subject to your individual circumstances. However, please note nothing in this letter is intended to constitute UK tax or planning advice. It is recommended that you seek independent advice where required.

    We will continue to keep clients informed on progress through the website and targeted communications.

    Yours faithfully
    For and on behalf of the Firms

    Russell Downs
    Joint Administrator and Joint Special Administrator
    Acting as agent of the Firms and without personal liability

    Appendix

    Client Data Notification (GDPR) 

    Russell Downs, Douglas Nigel Rackham, and Dan Yoram Schwarzmann have been appointed as joint administrators by the High Court to manage the affairs, business and property of Beaufort Securities Limited. Russell Downs, Douglas Nigel Rackham, and Dan Yoram Schwarzmann have also been appointed as joint special administrators by the High Court to manage the affairs, business and property of Beaufort Asset Clearing Services Limited.

    The Administrators and Special Administrators act as agents of the companies, without personal liability. All are licensed in the United Kingdom to act as Insolvency Practitioners by the Institute of Chartered Accountants in England and Wales. The Administrators and Special Administrators are bound by the Insolvency Code of Ethics which can be found here.

    The Administrators and Special Administrators are Data Controllers of personal data as defined by the Data Protection Act 1998. Personal data will be kept secure and processed only for matters relating to the appointment.

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights