Somehow I managed to get talked into doing the Great Ayton to Saltburn by the Sea leg of the 175K Cleveland Way hike in aid of The Yorkshire Cat Rescue Charity. I was up at 5am and drove the 116 miles to meet up with the newly named: Yorkshire Terminator aka Richard Jennings of Align Research. What a hilarious day I had on Saturday.
Click Pic 2 Donate
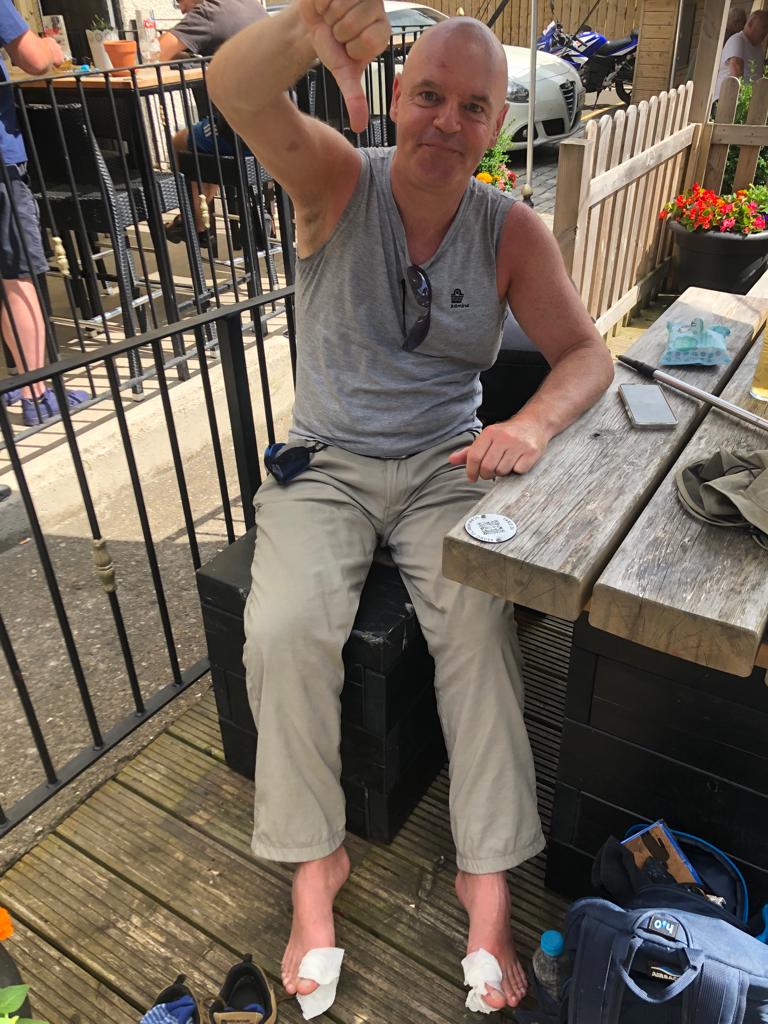
After 5 miles I managed to talk him down off the tops and we headed downwards to The Fox Inn, located in Guisborough. Patrons of the The Fox then had to eat their meals while Mr Jennings sat there in the posh beer garden with both bloodied feet in a wash bowl full of cider vinegar, provided by a relative of mine who (actually lives close by) came to the rescue. I imagine it’s now gone down in ‘Folklore’. We cleaned them up and true to form the Terminator swigged a beer and insisted on carrying on. Complete insanity
I’ve known RJ for a very long time. Had my own battles with him over companies but he’s always kept the door open to me. He’s one of the good guys. The tough, aggressive exterior is his protection against the lying scheming world that he navigates, but really underneath he’s a pussycat with a heart as big as a lion. He’ll be fuming reading this!!! My texts will go off the radar!
How he dragged himself over the Cleveland Way in agony and I mean in AGONY! Day upon day with 4 day old supperatting blisters, oozing blood, gunk, and toes swollen, was reminiscent of the Terminator. He refused to give in. Wouldn’t stop. Kept looking back and there he was dragging, himself towards me. Talk about Yorkshire Grit! LOL!!! If you ever met him I guarantee you’d not stop laughing and would walk away feeling a bit guilty. You wouldn’t have to buy the beer either….
There are some mean corporate bastards out there. It’s amusing to see them squirm when approached for a donation. However there’s a few that have donated. What that proves is that they’re still in-touch with the real world and real people such as you and me. But most wouldn’t give you the steam from their piss.
Well done to Richard Jennings and a big thank you for inviting me to hike with you. It was a pleasure and I will definitely take him up on his invitation to put in 10 days work at the Greek Cat Sanctuary he tirelessly keeps a float.
Some deluded, befuddled investors and traders are currently full of ‘Great Expectations’ on Mayan Energy (AIM: MYN) well let me educate those out there who are running with the hounds on this one, particularly my friend Richard Jennings, a good guy is Ritchie, whose company Align Research have over the last year or so really made a name for themselves as purveyors of honest opinion based on facts. That’s because Align try to ‘Align’ their interests with that of share-holders and usually, in the past have covered some decent listed companies.
I’ve used their research to great effect but sadly I believe their standards are now being lowered by covering companies of let’s say ‘dubious’ history. If you roll around with dogs then you get fleas and I’d urge Align Research to cease coverage on companies that have a history of telling ‘Tom Peppers’. Now I know why the Dogs of AIM are all rushing to Align Research. It’s because they have a good name as responsible analysts. Ergo the Dogs want their blessing to give them the semblance of respectability and professionalism. Basically so they can shaft investors. Fortunately I can write it as it is and am not enslaved by the corporate world. So you get it as it is. The truth no matter how unpalatable gets told by ‘Yours Truly’.
Lifestyle companies now being covered by Align Research, such as Red Rock Resources (AIM: RRR) run by that well-known Charlatan Andrew ‘Calamity’ Bell, the Dud, PowerHouse Resources (AIM: PHE) and the one I’m currently going to chronologically dissect, Mayan Energy, formerly trading as Northcote Energy and also Everest Energy, are beginning to surface. I changed my name once these fookers have had three….
Now I won’t go into Everest Energy. Other than to say Charlie Woods has been at it from the beginning. I’ll go straight from the Northcote 1st day of dealings run through their ‘Jackanory’ of company changing assets that always end up in the shitter and point out the increase in shares and the many placings. Then we’ll get to grips with the ‘Mayan’ assets, massive share dilution, placings, assets and CONsolidation and the new improved ‘assets’ while stating the fundamental cash position of thrice named Mayan….
DAY ONE NORTHCOTE
Northcote was launched with a $10,000,000 share purchase agreement (SPA) and a £1,000,000 placing. Their asset was The Horizon Project which produced 26.4 boe/d. Northcote had 866,904,578 shares in issue. Within 12 weeks they had placed yet again for £1,500,000, shares now in issue 991,412,716 assets coming in were the OKE Acquisition, the Eagle Option and the Bird Creek Project oil production was circa 48boepd. Yet again within 3-4 weeks they placed again £663,922, shares in issue 1,066,627,375 another asset Matthis. Oil production circa 100boepd. 5 Months down the line they place again £1,750,000, shares in issue 1,150,503,626, another asset South Weslaco.
By the time we get to Feb’ 2014 there’s now 1,238,066,657 shares in issue via options/assets paid for in stock and the initial issue of £1,200,000 zero coupon secured loan notes from vulture financiers Darwin Strategic, the Cleveland asset is renamed Zinc Ranch. 97.6 BOPD and 560.2 MCF/D net to Northcote. We get to 7am on the 12th Feb’ 2015 a loan note conversion is announced £50,000 total loan notes so far £250,000 push the shares in issue to 1,412,731,660, Shoats Creek, MXO deal etc. We then fast forward 1 minute, yes 60 seconds and Northcote RNS a placing for £1,558,000 further ballooning shares in issue to 3,380,021,399. In comes the acquisition of NAP USA. Then the fire sale of assets begins. Now are you getting the picture here? By the 20th of April 2015 the shares in issue stand at 4,748,137,883.
Now again I could go on and on but I suspect I’ll have to fast forward before I kill you with the litany of bullshit placings, stripper well assets and tie ups with such ‘illustrious’partners as Andalas Energy, MXO, Red Rock Resources and further asset sales, decreasing oil production, placings and cash rinsing that ended up with over ten billion FOOKING shares in issue (10,098,253,604) just before they changed the name to Mayan and started a rinse repeat operation.
FAST EDDIE ‘PARACHUTES’ IN
The 1st ‘Fast Eddie’ placing and a 400-1 consolidation!!! After fleecing tens of millions of pounds from UK Investors! Losses of circa $20,000,000, liabilities of approx. $3,500,000 with a ‘thumping’ $91k in cash! Doesn’t exactly instil confidence does it guys? ‘Fast Eddie’ parachutes in……
Nevertheless, let’s carry on because believe me it’s a right ‘Carry on’ and it only gets worse! The parachuting in of Eddie Gonzalez or as I call him ‘Fast Eddie!’ on 1st Sept’ 2016. ‘Fast Eddie’, didn’t waste any time getting to grips with the newly named Mayan Energy he quickly placed £550,000 and the shares in issue skied to (I kid you not) 13, 898,253,603 (Thirteen Billion, Eight Hundred and Ninety Eight Million, Two Hundred and Fifty Three Thousand, Six Hundred and Three). Of course, ‘Fast Eddie’ did exactly what the previous failed shysters did and issued himself a shitload of options: 780,000,000 (5.7% of the new improved rinse repeat Mayan) at 0.015 of a new shiny penny.
Within weeks ‘Fast Eddie’ was at the placing bolloxs yet again. This time a placing for £1,250,000. Shares now in issue a staggering 21,144,630,415 (Twenty One Billion, One Hundred and Forty Four Million, Six Hundred and Thirty Thousand, Four Hundred and Fifteen shares…..) I wont bother going into the warrant packages for the other corporate shysters.
But wait I’m not done yet!
‘Fast Eddie’ Not as ‘Fast’ as BMD I see right through you!!!
In March 2017 some 7 months since the new improved CEO took the helm, ‘Fast Eddie’ is at the Placing bollox yet again! This time it’s a 12,000,000,000 (Twelve Billion) £600,000 placing. Shares now in issue 33,144,630,415, (Thirty-Three Billion, One Hundred and Forty Four Million, Six Hundred and Thirty Thousand, Four Hundred and Fifteen). Oil production 20bopd!
CONsolidation
30 Days later we get a 400-1 share CONsolidation. The stock clock is reset and ‘Fast Eddie’ is rinse repeat raring to go… 82,861,576 shares now in issue. Read on it’s hilarious. 8 Weeks later ‘Fast Eddie’ places yet again! This time it’s 255,833,333 raising £587,500 shares now in issue 338,694,909 or to put that into old shares 135,477,963,600 (One Hundred and Thirty-Five Billion, Four Hundred and Seventy-Seven Million, Nine Hundred and Sixty Three Thousand, Six Hundred) and again I want bore you with the usual corporate shyster warrant packages or the bullshit nonsense about super dooper assets bought for peanuts….
This just gets better, 10 weeks after the above ‘Fast Eddie’ (I shit you not) places again! This time it’s another 287,000,000 shares raising £861,000 taking the shares in issue to… Wait for it … Wait for it… 604,156,447 or to give you the figure pre-CONsolidation 241,662,578,800 (Two Hundred and Forty-One Billion, Six Hundred and Sixty Two Million, Five Hundred and Seventy Eight Thousand, Eight Hundred) Usual corporate warrants for the corporate rats.
Now the absolute killer here if the above wasn’t enough to scare the living daylights out of you, is this!!! On the 17th November 2017 ‘Fast Eddie’ is at it yet a fooking gain. He raises £2,000,000 via the issue of 432,692,304 Placing, Settlement and Adviser and Deloro Investment Shares with the usual corporate shyster warrants. Mayan’s issued share capital is now back over 1 Billion!!! It’s 1,166,335,931 to put that into the old shares 466,534,372,400 (Four Hundred and Sixty-Six Billion, Five Hundred and Thirty-Four Million, Three Hundred and Seventy Two Thousand, Four Hundred). Give or take the odd share….
So, Dear Align Research you’ll have to forgive me for not being a believer in this POS, your research And ‘Fast Eddie….’ Who as you know, has been covertly operating on twitter via a private twitter group ramping and briefing well-known pump and dumpers in that group, exhorting them to buy/hold the stock while hinting of fantastic news and getting said P&Ders to retweet his tweets and sing the Mayan song to all and sundry.
ASPHALT RIDGE The Latest ‘JACKANORY’
So, I ask again just where is the cash coming from to progress Asphalt Ridge? Bearing in mind that $1,005,000 has already gone from the November 2017 £2 million placing while Mayans PLC costs and capex for their ‘other’ shite onshore USA assets, such as Zinc Ranch, which the company are actively trying to flog as I type, for a few hundred thousand dollars. Pray do tell me? Let me answer that Vulture Finance/Placing.
I’ll remind investors of the hastily formed Deloro company deal that gives Mayan and ‘Fast Eddie’ access to 8.3% of a potential 49% of Petroteqs’ Ashphalt Ridge, which would be owned by Deloro, not Mayan Energy! Mayans’ 8.3% is subject to the investment of $10,000,000 in staged payments by Deloro to Petroteq. Money Deloro and Mayan simply do not have, that is a fact.
The Asphalt Ridge project is being paid in the form of convertible loan notes, payable as follows: As announced months ago 16th November 2017.
Tranche 1 of US$2.5million due immediately to fund completion of plant upgrades and start-up of initial production; Tranche 2 of US$3.5million due once plant for more than 30 days is operating at greater than 1,000 bopd, and Tranche 3 of US$3.95million due on or before by 1 June 2018.
We know that Tranche 1 was paid in November 2017. Deloro, by their own hand, admit that they had $2.900,000 in cash and Mayan shares. $2,500,000 of that cash has gone. It went last year in November. $3,500,000 is now outstanding for Tranche 2. Where is that money coming from? Then there’s Tranche 3 $3,950,000 where is that money coming from? Mayans’ investment if they actually achieve 1,000 bopd and providing they pay all the $10,000,000 is 83 bopd? No it’s 8.3% of Deloros’ 49% which is circa 40bopd. Laughable!
RAMPING
Let me tell you why ‘Fast Eddie’ is ramping to fook on twitter and in private twitter chat groups. He’s trying to keep the Mayan SP up so that Deloro can dump (sell) the stock HE gave them as part of the Asphalt Ridge deal! 64,102,564 shares and to get yet another Placing away in the not too distant future. It’s an orchestrated, corporate, shyster, deliberate case of wholesale market manipulation.
The Mayan CEO Eddie Gonzalez ‘Fast Eddie’ has issued in old shares after only 16 months in the job and countless asset twists and turns Four Hundred and Fifty Five BILLION shares! Placings aplenty and there’s another one being lined up.
Now hopefully you will all understand my rather cynical view of ‘Fast Eddie’ and his Board, who’ve tried to use the good reputation of Align Research to HOODWINK the market! I respect Richard Jennings he’s one of a few good guys out there, but on this take heed: get yourself and your company as far away from this POS as is humanly possible. Otherwise your reputation and credibility will be damaged.
As for ‘Fast Eddie’ and Charlie woods, you’ll remember him he’s been ‘at it’ since day one, I’d expect that the thousands of UK Investors who’ve been rinsed out of tens of millions of pounds would like to ‘metaphorically’ take out, shoot and chop the Mayan board of shysters into Four Hundred and Sixty-Six Billion, Five Hundred and Thirty-Four Million, Three Hundred and Seventy Two Thousand and Four Hundred pieces of the rotten meat they are, then feed them to the fishes……
It looks like there’s another ‘developing’ Blockchain play, story at The Milestone Group (LON: MSG). I’m hearing that they’re rushing to get the news out and an RNS could drop within days setting out the companies strategy.
Now I’ve read the Align Research Note on them. HERE. However what it doesn’t state is when news is due. I can exclusively reveal that news could drop within seven days. If it does then I expect it will set out the MSG Blockchain strategy. That in itself is enough to move their SP. Blockchain is as those of you who know starting to set the world on-fire. Richard Jennings (Align head honcho) is a clever CFA dude. If he says they’re going big into Blockchain then believe me he has got the heads up.
There’s a new board of techie geeks coming on so this should help to drive Milestone away from the piss poor shenanigans of their checkered past. Lot of stock in issue but their SP is buttons. I can really see this one going on another rollercoaster when the news drops. At the moment their sp is 0.40p. Fundamentals aren’t too bad they’ve got cash in the bank, shares in issue are circa 1.7 billion. But as with all of these penny stocks the key is the quality of their Board in their space.
Get researching them probably worth a few hundred pounds as a punt. Remember when these companies start to flesh out their Blockchain strategy/products then they usually go mental!
FinnAust Mining (LON: FAM) is a dual AIM and Frankfurt Stock Exchange listed resources exploration company which currently has a number of prospective licences in Greenland, Austria and Finland. The company came to the London market in December 2013 following the £7.7 million reverse takeover of Centurion Resources. This brought with it a major shareholder in the form of ASX-listed nickel producer Western Areas, who we will discuss in more detail later, and which put up £1.8 million into the £3.4 million IPO placing at a price of 5p per share.
Having an initial focus on a range of early stage copper assets, shares in FinnAust fell steadily over the two years following its IPO as a result of a 35% fall in the price of the metal. However, a move into titanium in December 2015, driven by new Managing Director Rod McIllree, caught the market’s attention and breathed a new lease of life into the shares, which are amongst the best performing on the whole of AIM in the year to date.
FinnAust’s current assets are as follows:
Finland – owns 100% of a portfolio of copper, zinc and nickel projects; the Hammaslahti CopperGold-Zinc Project, the Outokumpu Copper Project and the Kelkka Nickel Project. In January this year additional licences were granted over the project areas, increasing the land area by c.50%. While these are not the current area of focus FinnAust still sees value in the assets.
Austria – an 80% interest in the previously producing Mitterberg Copper Project in Salzburg. This is largely a legacy asset from the reverse takeover of Centurion Resources and FinnAust is currently looking at realising its value.
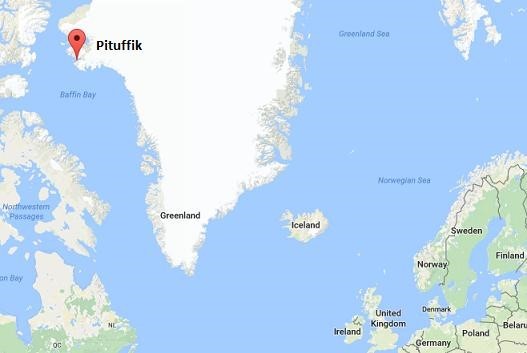
Greenland – the current focus of the company’s activities is the Pituffik Titanium Project in Greenland. FinnAust has an interest in the asset via its 60.37% stake in Bluejay Mining Limited, the 100% owner of the project, which was acquired in March this year.
The Greenland assets were added to in September this year when FinnAust agreed to acquire 100% of Avannaa Exploration from Capricorn Oil, a subsidiary of Cairn Energy, for £500,000 in new FinnAust shares. The two most noteworthy projects are the Disko-Nuussuaq nickel-copper-platinum project and the Kangerluarsuk SedEx lead-zinc-silver project. Located in the south-west of the country the assets had over $50 million spent on them prior to being bought by Cairn and are believed to have high-tonnage and high-grade base metal potential. The deal is conditional upon approval from the Greenland government and expected to be completed within the next few weeks.
Pituffik
Touted as a potentially world class asset, the Pituffik Titanium Project is located on the Steensby
Land peninsular in the north-west of Greenland, 83km south of the regional settlement Qaanaaq (pop. 656) and part of the Thule black sand province. Here, the coastline contains areas of high concentrations of the mineral ilmenite (the most commercially important source of titanium), on active and uplifted beach zones, which are the focus of Bluejay Mining. Bluejay holds exploration licences over 150km² of onshore ground and shallow marine environments at the project.
The acquisition price (for 60.37% of Bluejay remember) was a maximum of £905,607, paid for via the issue of 164,655,885 new shares in FinnAust at a price of 0.55p per share. Of these, 40,755,885 shares are deferred (see more below) and there is a four year option to acquire the remaining 39.63% stake (another point discussed in more detail later). The Bluejay vendors include, interestingly, FinnAust’s Managing Director Rod McIllree and Non-Executive Greg Kuenzel (of Noricum Gold fame). Along with the acquisition, a placing of 10 million new shares at a price of 2p each raised just £200,000 with major shareholder Western Areas putting in half of this.
As you can infer from the picture below, Pituffik is not somewhere you would want to go for your summer holidays, being located in the Arctic Circle and experiencing harsh climatic conditions. Despite the cold, Greenland has actually been warming up, with climatic changes causing its ice sheet to retreat and exposing new areas for minerals exploration and exploitation.
While originally being discovered in 1915 Pituffik remains an early stage exploration asset.
It caught FinnAust’s attention due to having high grade material and exploitation potential. Historic fieldwork by Bluejay, the Geological Survey of Greenland & Denmark and others has highlighted the presence of a very large and, according to the company, “unusually pure” titanium deposit at Pituffik. Active beaches in the region have demonstrated grades of up to 68% ilmenite, averaging between 38-40%, with the more expansive uplifted beaches averaging around 17%. Upon acquisition FinnAust’s CEO McIIlree gushed that Pituffik has the potential to “become one of the highest grade in situ deposit of ilmenite anywhere in the world.”
Key Areas.
There are two key areas which have been identified for further work at the project, Moriusaq and Interlak, located along an 80km coastline in environments including raised beaches, active beaches and drowned (underwater) beaches. Moriusaq is the most advanced area and has returned the highest ilmenite grades to date,with grades in some areas estimated to be in excess of 85% ilmenite. Interlak offers the largest volume of heavy mineral sands, with grade upside potential, with grades in some areas estimated to be in excess of 70% ilmenite. The plan is to advance Moriusaq first given that its marine environment could provide an opportunity to employ dredging (a simple and low cost method) to exploit the sands.
Latest developments
Following the initial agreement to buy the stake in Bluejay in December 2015 FinnAust quickly got its plans together for developing the asset, with the strategy being to capitalise on Pituffik’s near term production potential. In February, results from a bathymetry (underwater) and seismic profiling survey completed in 2015, along with a sea floor sampling programme, suggested that the shallow marine environment hosts very large volumes of potentially high grade titanium, with the results multiplying the amount of known titanium mineralisation significantly.
Subsequently, various technical consultants were hired in order to complete fieldwork over the course of 2016, including an initial resource calculation for the Moriusaq target and surrounds. With the nights (and days) getting colder, the work programme was finished in September, with more than 500 drill holes having been completed along with trenching and sampling across the project area. Results confirmed that the two target areas will remain the key focus. An Environmental Impact Assessment has been completed and a Social Impact Assessment is underway.
FinnAust is now in a position where it expects to publish a JORC compliant resource by the end of 2016, ahead of commencing an initial 30,000 tonne proof-of-concept bulk sampling programme in 2017, followed by the application for an exploitation licence in Q1 2017.
So far so good but valuation is materially out of kilter with the progression stage
To give FinnAust management credit the company has, over the past ten months or so, provided a text book example of how to promote s story, and they have done so with a relatively limited freefloat. A plethora of technically worded RNS’s with copious amounts of “pleasing” and “exciteds” peppered throughout these releases in relation to the Pituffik asset has pushed the stock price up nearly 15 fold since the beginning of the year. The shares have risen from 0.55p just prior to the Bluejay acquisition announcement to the current 7.5p, making FinnAust one of the best performing shares on the whole of the London markets in the year to date.
All well and good but we have a number of issues and questions.
Difficulties mining in Greenland
As a jurisdiction, Greenland has its attractions and is regularly ranked as one of the most attractive places for mining investment by various industry surveys, accepted. The government is becoming ever more mining friendly as it looks to take advantage of the island’s rich resources and, in contrast to the locations of many AIM listed junior miners, the country is politically stable. As mentioned above, climate change is causing ice sheets to retreat, creating the opportunity to study new potential resources.
But there are many challenges related to operating a mine in Greenland, mainly due to the harsh climatic conditions and remote location.
At Pituffik itself the average daily temperature in July barely reaches 8°C, with the winter months typically seeing temperatures of around -20°C. This creates a situation where certain activities can only be carried out at certain times of the year and makes for a more expensive operating environment. With pack ice forming in the early autumn the window for making shipments from Pituffik could be as low as five months.
Infrastructure in the country as a whole is limited, with there being no major road networks and most domestic transportation being conducted by air – Pituffik is located c.30km from the international airport and deep-water port of Thule Air Base which is operated by the US Air Force to the south-east and Qaanaaq domestic airport to the north.
Issue over deferred consideration and options shares
As part of the Bluejay Mining acquisition it was agreed that 40,755,885 deferred shares be paid to the vendors upon the grant of a mineral exploration permit over the offshore Pituffik project area. This was subsequently granted in July this year and satisfied one of two terms for the issuance of the deferred shares.
However, the second term requires that the issuance does not trigger a mandatory offer for the company by the Bluejay vendors under Rule 9 of the Takeover Code – ie. if their stake goes over 30% they will have to bid for the whole company. This situation would have occurred had the shares been issued given the Bluejay vendors’ current holding in FinnAust, so the company is waiting until any Rule 9 obligation ceases to exist before the deferred shares are issued. This can only come if the vendors sell some of their holding or, in the more likely case, their combined stake is diluted by further share issues.
There is also a four year option to acquire the remaining 39.63% of Bluejay for £594,393, to be satisfied by the issue of 108,071,388 new FinnAust shares to the Bluejay vendors. Again the situation is similar here in that the option will not be exercised if it were to trigger a mandatory offer or would trigger a reverse takeover under AIM rules. We note the RNS of 4th October in which Rod McIllree makes the statement “The Company now intends to review the mechanics of moving to 100% ownership of BlueJAy Mining Ltd (and hence Pituffik)…” and believe that this will be the “tell” that in fact unseats the stock price. The easiest avenue is simply to place the stake due to Blue Jay with a third party. As we point out below however, with a market cap approaching £50m without a JORC estimate at this point and no clear path to infrastructure build out, our bear case hinges almost entirely on this point – that is we doubt that a third party will pay anywhere near the current market cap in cold hard cash (the acid test for the industry’s perception of true value) for Blue Jay’s shares that are due from Finnaust and would thus absolve the takeover trigger. Of course they could apply for a “whitewash” if no third party steps up but all this does (assuming it was granted) is push out the date required for a liquidity event for the stockholders whilst not addressing the continuing cash needs of the company.
As we illustrate below in addressing our valuation concerns we suspect that any deal to place FAM shares for Blue Jay (if this route is taken) will be at a material discount to the current stock price if done in cash and still so if part of a strategic investor swap (which is what Western Areas is of course supposed to be…).
Director backgrounds
We note that certain Finniest directors have, shall we say “interesting” histories. Rod McIllree was the founder of ASX listed uranium explorer Greenland Minerals and Energy and its Managing Director up until August 2014. Australian newspaper The Sydney Morning Herald reported on several issues with the company including questions over its ownership structure (see here http://www.smh.com.au/business/unravelling–the–greenland–minerals–web–20091008–gp0w.html) and the rapid dilution of shareholders via the issuance and exercise of options. In addition, it would appear that McIllree and fellow director Simon Cato sold stock into the market immediately after exercising options – see here http://www.smh.com.au/business/a–cold–front–for–greenland
“In mid-April (2011) those two (Cato and McIllree), and Why brow, each received 4.4 million newly vested options. Earlier this month (May 2011), Cato and McIllree both announced that they had exercised some of their options, 1.55 million and 250,000 respectively, but their filings suggested that they must have sold them immediately because their total shareholdings remained unchanged.”
The share price performance of Greenland Minerals has been “erratic” to be polite– see chart below. But What Greenland Minerals has in common with FAM is that there was a concerted news blitz that increased the stock price materially before the company was laid low in large part due to the debt that was taken on. The problem with a heavily promoted bull story is that at some point the major stakeholders have to get out and if there is not a liquidity event to provide this gravity always kicks in.
We also point out that Greg Kuenzel, Non-Exec at Finniest, has a history of value destruction at AIM listed Noricum Gold where he is Managing Director. Since the company listed in December 2010 the shares have fallen from the IPO price of 4p to the current 0.12p after failing to prove a JORC resource at various projects.
We also add that we have posed a number of questions to Rod McIllree in relation to these points to which he has deigned to reply.
A mine of information from the 2016 results
While there was nothing really new in the company’s 2016 results regarding progress on the ground the P&L and balance sheet provided a wealth of information. It was revealed that cash as at 30th June stood at just £425,046, although this figure was boosted post period end by a £500,000 (preexpenses) placing. With monthly administrative costs being c.£52,500, and assuming placing fees of c.£25,000 we estimate that the current cash balance amounts to around £0.75 million. With this amounting to just over 1 year’s worth of admin costs there is clearly a placing ahead, we suspect in the first half of next year at the latest.
Non-participation of major shareholder in last 2 placings
Back to the placings… Finnaust has raised a total of £1.5 million since announcing the Bluejay acquisition – £1 million on 4th March at 2p per share and £0.5 million on 13th July at 5p per share. Our question is why has Western Areas, trumpeted as a cornerstone investor, not taken part in these placings? And why did it only put £100,000 into the original acquisition placing? WhileTakeover Code rules prevent Western Areas as a major shareholder (37.14%) from increasing its interest, we believe it could have at least maintained its holding noting that the Bluejay acquisition document states:
Following completion of the Placing and the Bluejay Acquisition, neither Western Areas nor the Bluejay Vendors will be able to increase their interests in the voting rights of the Company through or between a Rule 9 threshold without Panel consent.
Valuation
The main question here boils down to the valuation.
At the current share price of 7.5p the markets are valuing FinnAust equity at a shade over £37m million. But if we calculate the valuation using the fully diluted number of shares in issue (see table below) then we arrive at a figure of £49.6 million
Current shares in issue
494,400,804
Options & warrants
19,309,366
Bluejay deferred consideration
40,755,885
Bluejay option
108,071,388
TOTAL
662,537,443
While we do not deny that FinnAust’s assets have potential we firmly believe that a figure of approx £50 million is simply far too high given the company’s current stage of development.
Even a research note written by the company’s own broker, Optiva Securities, back in February admitted that valuing the company was “challenging” largely given the early stage nature of the operations. We quote:
“Given the early stage of the Pituffik project, limited exploration data and the fact that the deposit does not yet support a JORC-compliant mineral resource estimate, it is challenging to estimate a value for the project in its current stage, in our view.”
Here’s why we think the valuation is overheated.
Pituffik remains a very early stage asset. As yet there is no JORC resource, an exploitation licence to apply for, social impact assessment to complete, inevitable future placings to complete for working capital and the all important project financing to be raised.
Minimal asset backing on the balance sheet. Net assets amounted to £12.48 million as at 30th June, with most of these being in the form of £12.63 million worth of intangibles. These include £1.9 million attributed to the Pituffik licence. These values would have been hard tested by the auditors and is the first “tell” that the market cap is out of sync with the current stage of resource progression. Remember this value includes ALL the company’s assets too not just Pituffik.
Stripping out the book value of the non-Pituffik assets as at 30th June 2016 (£10.7 million) from the current valuation reveals that the market is effectively valuing Pituffik, an asset that was valued by the Bluejay vendors themselves at just £1.5 million only 10 months ago, at approx £40 million (on a fully diluted basis). We question whether the work done since acquisition has justified this 26-fold increase in value.
One valuation benchmark we can use is a November 2015 technical report compiled by consultants SRK which determined a valuation range of $0.6 million to $24 million for Pituffik based on a variety of variables. While the report excludes the offshore dredging element of the project we note that even the highest valuation of $24 million represents a value of just £18.4 million – less than half the fully diluted current market price.
Another valuation benchmark comes from the recently announced £215 million acquisition of mineral sands producer Sierra Rutile by Iluka Resources. The deal was completed on a historic enterprise value/EBITDA multiple of 16.2 times. Assuming a build out cost to FinnAust of say c.$20 million (£15.4 million) gives an enterprise value for the company of approx £65 million. Applying the Sierra Rutile exit multiple thus means that FinnAust needs to be making annual EBITDA of c.£4 million to justify anywhere near the current valuation.
We believe Finnaust has been a text book example in how to release news to the market in relation to a potentially positive mining opportunity whilst simultaneously keeping the free float tight. A classic squeeze if you wish.
But, once sell orders start coming through, which we suspect they may do as private investors look to take profits or, more likely, any strategic investor puts a very different valuation on the company’s assets given their current stage, the tumble downward could be rapid. While the deal in Greenland with Capricorn/Cairn is not yet complete when it is, we suspect there will be another £500,000 worth of shares in the market looking to be sold – we doubt Cairn will be looking to hold on to the stock given they wanted to be out of the assets at such a low price and they are after all much more financially resourced than FAM to develop them if they so wished.
The fact is that, while many have made large paper profits on FinnAust, liquidity remains low and a value event is needed for those gains to be realised. If the company itself needs an exit, if it is overvalued the industry simply will not pay up.