google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Andrew Dennan

  • NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    Commenting on stocks and shares can at times feel like a character from a Hans Christian Andersen tale, one in particular, “The Emperor’s New Clothes” springs to mind every time I read or see the utter shite constantly pumped on social media by various shysters on both sides of the fence, corporate and retail.

    It doesn’t take a genius to see the metaphors from fairy tales played out on City of London listed companies by traders and corporates alike who rely on ‘greed’ to blind ‘common sense’. The target being lumpen-proletariat small time mug-investors or as I call them ‘the meat in the liquidity sandwich’. The goal is to push the ‘tall tale’ using various ‘ruses/ploys’; such as ‘behind the scenes briefings’ to certain well known P&D merchants who take a position as well as small fees with ‘warrant packages’ then go out heralding the news of riches beyond your wildest dreams….

    Which brings me on nicely to Nu-Oil & Gas (AIM: NUOG) the current nudge, nudge, wink, wink is in full flow not least on the BBs and twitter sphere. NUOG are a shell they have absolutely no value whatsoever other than there listing value. The old Board of Directors are being paid out, then kicked out, with a new team set to come in post GM ratification. The ‘new deal’ is deliberately structured in such a way that a select group of Novum placees (no more than 4/5 individual connected investors) are taking 1,000,000,000 shares of stock at a 50% discount to today’s SP, while a newly formed corporate entity holds £2,500,000 of loan notes (again at a 50% discount) to flip out as and when you ‘the meat in the liquidity sandwich’ are buttered up into believing in ‘Fairy Tales’. Mugs buying in at 0.075p are paying a 50% premium to that placing and loan note package. £3,000,000 will be flipped out into the orchestrated rise. A rise that will be predicated on a ‘hope value’.

    If by now you haven’t worked out the implications then let me spell it out. You’re starting a race with a handicap. You can never beat the corporate flippers because they have a 50% head start with access to the news flow. If today you were 20% down on your stake bought at 0.075p they would still be 30% up. It’s a race you can never win.
    ‘Weaver’ Fumagalli?

    The company holding the £2,500,000 loan notes are C4 Energy Ltd. That paper company is the brain child of one Marco Fumagalli (Continental Investment Partners, Sound Energy, Coro, Echo) and Mr James Parsons (JP) (Sound Energy, Echo energy and Coro). Both are connected at the hip as is Mr Andy Dennan proposed director NUOG, (current CFO & Director CORO, Sound Energy Holdings Italy Ltd, Alpha Growth Plc, Baron Lux LLP). I know them all, have met them, broke bread with them and talked all things O&G with them. They’re decent people in their own way. But as corporates go I wouldn’t trust them with a ‘birds nest’. They are ‘corporate bastards’. NU-OIL, at this stage of its evolution, isn’t about finding oil or gas in Cuba, Mexico or some far field of a foreign land that’s forever England, it’s about corporates playing the system using a tried and tested method to make money regardless of finding oil or not. 

    …..  ‘Weaver’ JP? …..

    All of the above have made substantial sums of varying degrees, of a reputed £200,000,000 million generated from the Sound, Echo and CORO ventures. The largest slice of the pie going to the moneyman who finances the companies: Fumagali/Continental and their various offshore exotic mechanisms.


    The ownership of C4 Energy wasn’t disclosed in the RNS of 2nd October 2019. That omission was deliberate. It was a calculated ploy to set the NUOG shareprice to spike in an attempt to replicate the fantastic gains of the early days of Echo Energy. Pump and Dumpers were briefed to scream it from the rafters. It ultimately failed. 

    Sadly all three companies Sound, Echo and Coro ‘ultimately’ bombed. Now that isn’t a critique of any wrong doing. Far from it. In the real world the best any investor can ask for is a company does what it says on the tin: i.e. They get their licence, and drill it. All 3 companies have done exactly what they said they would do. They have ran and continue to run within the rules and regulations. On the whole their biggest failure has been geological and it’s geology that determines financial success or failure for shareholders. However it’s not the geology that determines success or failure for corporates it’s selling heavily discounted stock into ascending share prices.

    The whispered Cuban licences for NUOG are a fantasy. One only needs to do what Liargas did with his ‘Fairy Tale’ and speak to the British Ambassador to Cuba who explained that O&G exploration in Cuba was 15-20 years away due to the Geo-political situation vis-a-vis the USA. Exit stage left Liargas from Cuban oil into cannabis.

    Based upon historical performance of those now taking control of NUOG if it runs true to form then it’s nothing more than a corporate carve-up pre change of control…….

    So, the questions are many. Too many for this blog. But questions will be put to those running the show and answers sought next week. Such as: Since when did an Oil & Gas CEO (JP) decide that issuing vulture finance packages and organising a select placing at ‘mates rates’ to mates, become more productive than finding oil and gas?
    Viva


    Dan


    N.B:  Kejserens nye klæder) is a short tale written by Danish author Hans Christian Andersen, about two weavers who promise an emperor a new suit of clothes that they say is invisible to those who are unfit for their positions, stupid, or incompetent – while in reality, they make no clothes at all, making everyone believe the clothes are invisible to them. When the emperor parades before his subjects in his new “clothes”, no one dares to say that they do not see any suit of clothes on him for fear that they will be seen as stupid. Finally a child cries out, “But he isn’t wearing anything at all!” The tale has been translated into over 100 languages.
  • Coro Energy: The Shambles Part 2. Placing Update!

    Coro Energy: The Shambles Part 2. Placing Update!

    Shambles Placing

    One of my favourite sayings that I often use when it comes to the fakirs and shysters that operate on both sides of the corporate fence, is “Oh what a wicked web we weave when we practice to deceive”,. The tricks and manoeuvres never cease to supply me with a barrel of laughs. CEO’s, Directors buying a pittance of stock, clarion calls, emails and text messages to the gullible, Chief Operating Officers rocking up on cowboy podcasts to deny funding, twitter DM groups infiltrated by the company PR to monitor how the deceits are being swallowed. Mass tweets of the‘veritable’ paid pumpsters such as Total Market Shite (TMS). It really is testament to the power of honesty that one man exposing the shambles of companies can have such an effect.

    I’m reminded of that well known line in the exorcist: “The Power Of Christ Compels You” Ergo, The Power Of Dan Compels You…. AIM companies just need to be honest. It’s as simple as that. Honesty is the best policy. You duck, dive and deceive then you pay the ultimate price. Loss of your share-holder base. Such is the ‘Jackanory‘ on Coro.

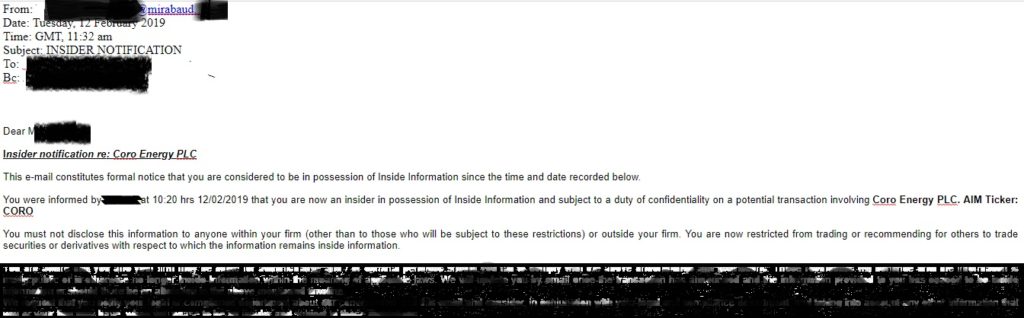
    Yesterday those that had been made inside on the Coro Energy (LON: CORO) placing were ‘cleansed’ Mirabaud, Company and Nomad emails went out ‘en masse’ and the CEO bought a handful of confetti which means that Coro have, after being exposed on here, done an Angus Energy (LON: ANGS), delayed and walked back their placing and we all know what happened there, which will happen here. Coro will try to puff up their SP then when the coast is clear they’ll drop their Placing. It’s a ticking placing bomb on the heads of those daft enough to suck up the guff. Hence why the 5 day ‘silence of the gullible’ was broken by a plethora of corporate denials, but you can, like Angus, only delay the inevitable for so long. The cash position is woeful. Their balance sheet reveals the two ‘fundamental’ truths. The shine of my good com padre, James Parsons has some what dulled and £14M has all but gone…….

    Which leads me on to another snippet of news. Just why have Coro paid circa £18,000 (Flights, Hotels, Wine & Grub not included) to attend a ‘one to one’ direct corporate investor funding shindig in Hong Kong?

    1/ Because Coro have got lots of cash?

    2/ Because Coro have spunked away £14M?

    It’s a bit like speed dating but in this case it’s speed ‘debting’. As for the Euro Bonds for Gas, any one with half a brain knows that Lombard ‘odious’ and Rob Giles are vulture financiers. This is death spiral funding. Euro Bonds for gas? Would that be laughing gas? As sure as night follows day, however much they ‘delay’ theirs a placing coming.

    It’s a Shambles. Like venereal disease, take precautions. Protection helps.

    Viva!

    Dan

  • ‘Seeking Alpha’ (Growth) I Accuse!

    ‘Seeking Alpha’ (Growth) I Accuse!

    Image result for alpha growth logo

    “Oh, what a tangled web we weave… when first we practice to deceive” That pithy saying could almost have been exclusively written for the Alpha Growth Chief Operating Officer (COO) Mr Daniel R Swick.

    I was an investor in Alpha Growth (LON: ALGW) on their IPO. I liked the company it had a good business plan, a Board of Directors that passed muster and a very capable investor relations team who got their message across. If it could do what it set out to do, then the SP would rise and rise it did. Hitting over 5p in 2018 from its IPO price of 1.2p. Indeed, their SP is still trading over 70% up from the IPO price, that is good news. I sold out way back last year when it became apparent to me that they were in contractual difficulties signing up on the major contracts that were being promised, taking a modest profit of circa 40%. I needed cash for a property investment renovation. But I never stopped following or researching them as they could always be a contender for a blog post etc.

    Broken Promises

    Alpha Growth came to the market promising great things in the Longevity sector, a fancy word for buying peoples pensions/life insurance policies at a discount. Trumpets were heralding major company making deals just around the corner, unfortunately one can only blow one’s trumpet for so long before lips blister and you run out of ‘puff’ and after 14months of ‘blowing investors trumpets’ the clarion calls have faded to a weak squeak. Credibility is now on the line for the company. And it is credibility that I draw investors/trader’s attention too.

    Now, this is an important point to understand, which becomes self-explanatory further down this article, Alpha’s business is all about ‘Contracts’ and their ability to not only sign contracts to close deals, but to stick to the terms of a contract. Contractual breaches are not good business when you’re in the Longevity sector. Doesn’t matter what the contract pertains to or who it’s with. You breach & it gets out then you’re in difficulty and your ‘Longevity’ as a company comes into question.

    Placing

    My sources and research indicated that the Company were running up debts, having contractual difficulties, failing to close deals and needed to raise cash in the not too ‘distant’. In short potential Contract Failures/Breaches of some kind or another etc. Recently having spoken to probably one of the most diligent FCA regulated broker/nomad outfits to clear up the ALGW placing rules I can confirm thus: The amount they can raise (being a standard listed entity) is a percentage (20%) of their shares in issue in any one 12-month period.

    “Companies quoted on the Standard List have greater restrictions on the issue of new shares than those on the AIM (cess-pit).  Once a company is listed, it can only increase the number of shares that are admitted to trading through either a placing or from the conversion of convertible debt or exercise of warrants (unless issued prior to June 2017 in both cases) is limited to 20% of the shares already admitted to trading on a rolling 12-month basis.  The only way around this is to issue a new prospectus.”

    There is a temporary work around in that for shares quoted on the Standard List, a company can issue the shares (or shares that may result from a convertible) and not admit the shares for up to one year.  This means that the shares cannot be traded, but only a fool or someone confident of a huge rise in value would agree to this.

    Material Uncertainty

    With a declared cash balance of £237K, as of last year Dec’ 2018 they can only issue 20% of 126,335,000 shares in issue. That equates to a total placing of shares of 25,267,000 in their next 12-month window. Being an extremely generous type let’s say they raise cash with a small 20% discount at 1.6p. That’s circa £400k in cash over the next 12 months bearing in mind that they burnt through close to £500,000 up to August 2018 (8 Months) and generated zero cash then they have for the next 12 months a miserly £600,000. Which is why their Auditor issued a “Material Uncertainty” as a going concern. Alpha Growth must raise cash.

    Contractual Breach

    Now that brings me on nicely to one of the known on-going legal disputes regarding a breach of contract to a ‘service provider’ that’s snowballing into a full-blown court case. How do I know this? Why it came directly from Mr Danny Swick who passed confidential information, in breach of contract, to one of Alphas ‘Cornerstone Investors’ on 23rd/24th December 2018. (It also embroils the Cornerstone Investor into a legal dispute) So, my source, on the now known legal dispute, is ‘Swick the Dick’ who made wholly unsubstantiated, malicious claims that the service provider briefed me, thus breaching the contract. Laughable, as it is deceitful, to try to deflect away from their parlous, pecuniary position and their failure to ‘pony up’ and pay their debts, ‘Swicky’ has told a pack of lies to the service providers solicitors! Ho! ho! ho! Talk about digging a hole……

    Of course, I’ve provided the solicitor (who contacted me directly) with the name of the Cornerstone ‘geezer’ and a full verified transcript of the twitter conversation, that is as you say “f**king damning” while completely exonerating myself and the service provider from ‘Swicky Dicks’ lies.  One thing it does, is prove 100% that the leaker of confidential information is Mr Daniel R Swick.

    Caveat Emptor

    Image result for pump & dumpWhat’s going on here is simple: The feeding of ‘green bananas’ (Promises of contracts/deals worth £100Ms) to the BB ‘Howler monkies’ in order to artificially manipulate their share-price so that they can raise cash at higher levels. Then dump a placing on the mugs who buy in at the higher SP. By way of example: This is the dichotomy: “Alpha Growth plc is a financial advisory business providing specialist consultancy, advisory and supplementary services to institutional and qualified investors globally in the multi-billion dollar market of longevity assets”. Says the blurb on their website. This is their financial position: Just over £200K, No revenue, No big contracts signed, Contract Breach, Legal Jeopardy, with qualified accounts containing their Auditors ‘Material Uncertainty’.

    Big Red Flags

    Alpha are a company that deal/trade in contracts. A contract is a legally binding agreement based on honesty and integrity. Breaching a contract simply because you do not have the cash to pay is bad business practise but breaking the confidentiality of that contract then lying to a solicitor is about as big a red flag as an investor can get. If a COO of a company is prepared to cheat another company out of their fees, tell a pack of lies to a solicitor while giving out confidential information to ‘privileged’ investors then one has to ask what else has this company lied and cheated about?

    Questions

    1/Who else hasn’t been paid? 2/Why haven’t the so called ‘big deals’ been concluded? 3/How many others has Swick been passing confidential information too? 4/What are the implications of cornerstone investors being given sensitive information before the bread & butter investors? 5/Is this endemic of their business? And 6/What will happen when their potential business partners learn that the company, they’re looking to sign a contract with breaks confidentiality, lies to solicitors, doesn’t pay up and ‘could’ be on the hook for literally £100,000s in legal costs if it ever gets to the High Court? It’s a fooking minefield! I could go on and on with the legality and drag in The FCA rules on disclosure and market manipulation, and why Swick needs to ramp up the Alpha SP etc. But I fear information overload for the reader…. Swick has been heavily involved in the formation of Alpha Growth and the IPO from day one. He wasn’t plucked out of the ether or head hunted. Swick was running around London in 2017 engaging with brokers and corporates pre IPO on ALGW business.

    Suffice it to say that I’m now all over this lot speaking to journalistic sources in the USA and their potential business partners.

    I promise you this ‘Dear Swicky’ should you or any of your team appear at any investor presentation in the United Kingdom then ‘Yours Truly’ will be attending to rip you and your company a new arse hole in public and in front of your investors (Mugs)

    Blow My Own Trumpet

    And that Ladies & Gents is why I’m the 2016, 2017 and fingers crossed (Vote for me), the 2019 ADVFN International Financial Blogger par excellence…….


    Image result for advfn 2017 international financial blogger photoViva!

    Dan

    X


google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights