On New Years Eve 2019 an RNS landed, when I say ‘Landed’ I actually mean it was forced (greenmailed) out of Anglo African Oil & Gas (LON: AAOG), by a group of what can politely be described as ‘Corporate Bullshiters’. The RNS went on to explain a ‘proposal’ to basically buy all AAOG (Riverfort) at 1p per share and £5,000,000 of funding. That information, that was forced out of Anglo African Oil & Gas, caused a huge spike in their lowly Share-Price.
That rise, along with the buying of stock previous to the RNS release and the subsequent selling of the stock needs to be investigated by the AAOG Nomad. And here’s why.
The Group who made the offer are headed by Mr Adam Dziubinski of the one man band, or is it 2? Brokerage Jub Capital whose history is one long story of ramping stocks on social media, email, twitter and private message groups then selling out on the quiet, leaving mug punters holding the very stock that Jub sell. Jub Capital is well known to me and every serious trader/investor. Mr Dziubinski is a known corporate flipper of stock on the Alternative Investment Market. He has no oil or gas experience. None whatsoever, unless ‘flatulence’ qualifies to go on a CV.
What in my honest opinion is happening here is nothing short of farcical.
Questions need to be answered by Jub Capitals’ Mr Dziubinski as to the veracity of their proposal, which has fundamental ‘SkoolBoy’ flaws in it. Are Finncap, shareholders and the BOD of Anglo African aware that:
Oxford Energy Ltd has no cash whatsoever, no office, no assets and has no experience in O&G other than the word ‘Energy’ in the companies name?
Are they aware that Oxford Energy have no accounts and are in the process of being Struck Off as per United Kingdom companies house gazette notice?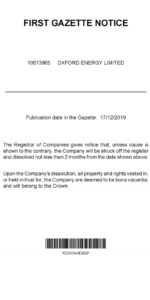
How can a company that’s a piece of paper, with absolutely nothing, zippo, no accounts, no cash and in the process of being Struck Off be allowed to claim in an official RNS that it’s going to pony up £5M? It is farcical in the extreme….
As for the proposed directors coming on the Board of AAOG. The appointment of Alex MacDonald and Matt Thompson that in itself is no less farcical.
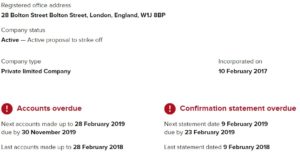
Thompson has three directorships showing. The (soon to be struck off) £100 Oxford Energy Ltd. Adventure Power Ltd, 18 days old, value £100 and the creme de la creme 20 day old Grosvenor Energy Ltd. Value? £2…..
While ‘Old’ MacDonald has one directorship and 1 share in? Yes you’ve guessed it Grosvenor Energy Ltd. The £2 company.
These are serious failings on the veracity of this ‘groups’ proposal. One has to ask what the fook Align Research and Richard Jennings are doing teaming up with this crew?
As for ShareProphets & Tom Winnifrith **it’s a case of too much cooking sherry over Xmas! How could TW fail to spot such a pig in a poke? Particularly as he’s well aware of the historical Pump & Dumping of Jub Capital…. And Dziubinskis’ use of Chris ‘Oil’ Williams’s funds. The majority of funds currently on deposit within Jub Capital belong to Mr Williams. Indeed Chris Williams ‘IS’ by de facto a major shot caller at Jub Capital in all but name. Without his money they’d be struggling day to day. I don’t need it confirming but I can say with a degree of certainty that Mr Williams will have been approached re AAOG funding pre the forced RNS…. Take that as read!
I’m a substantial shareholder in Anglo African Oil & Gas via Sefton Resources. I look at this proposal as both a CEO and a shareholder. How in Gods’ name can a struck off Oxford Energy take a loan out of £5,000,000 secured on 100% of the shares in AAOG Congo? Oxford Energy don’t own AAOG Congo. It is farcical.
It’s all about one thing and one thing only. Jub Capital and their cronies using AAOG as a vehicle to dump artificially inflated stock on you the Lumpen-proletariat.
The Tilapia asset is in deepest, darkest Congo, central Africa. Pray tell share-holders Jub Capital, exactly what’s your experience in organising an O&G drill in Africa? The Congo is a dangerous country to operate in. It’s to the credit of AAOG that they got as far as they have. You need to be able to operate , organise and communicate with various factions within and out of Government. Capabilities that this ‘group’ doesn’t have and never will have. Going on the piss in the flesh pits of Bali, Thailand and Mexico, to name but three of the recent haunts Dziubinski has rocked up in, is yet again indicative of the farcical offer. Zero experience.
So in a nutshell the choice for the Board, shareholders & Finncap the Nomad is which company or group are best able to deliver some value back to Anglo African Share-Holders?
1/ Zenith Energy a proven, albeit, small, producing oil company that operates the largest onshore oilfield in Azerbaijan by cumulative acreage who also have a Production Sharing Agreement with the State Oil Company of the Republic of Azerbaijan (SOCAR). Zenith are a London standard listed Company with a medium to long-term credit rating of “B+ with Positive Outlook” issued on October 9, 2019 by Arc Ratings, S.A. And a “B+” with Stable Outlook debt issuer credit rating issued by Rating-Agentur Expert RA.
OR
2/ The tiny P&D Brokerage Jub Capital and its cronies such as Oxford Energy a company with no O&G experience, no assets, no cash, no accounts, a nominal paper value of £100 and due to be Struck Off within weeks?
There are a myriad of Serious questions not raised in my article, to be asked and answered here by the Nomad Finncap. This Open Letter has been emailed to them. I trust that they will now follow up and as they say ‘follow the money……’
It stinks!
 Viva
Dan
**NB. I’ve altered this joke as I’ve had a complaint (Over-Reaction) from Mr Tom.