google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Colter

  • Andalas Energy & Power. Take The Deal Mr Gorringe!

    Andalas Energy & Power. Take The Deal Mr Gorringe!

    Andalas Energy & Power (LON: ADL). What’s going on within and out-side of the company? It would seem that there’s a very slow tick up of the SP underfoot. News has been reaching ‘Yours Truly’ that Andalas are the target company of at least one and possibly ‘others’ who are sniffing around to take full Board control of the Company. I won’t go into each individual group as they may or may not be in direct talks with ADL. What I will do is disclose my take on one of the groups who HAVE made an approach (I believe pre or during Colter drill) and are in contact with some of the Major Share-holders.


    It could be about to hot up at Andalas Energy. Now the emphasis is on ‘could’. So I’d ask investors/traders to keep that word in mind. There’s reasons for that. The chief one being the corporate world of ‘wheels & deals’ doesn’t run to the time-line of you/me, it can get and does get snagged up in back-room compliance/negotiation. That is to say nothing is certain until it’s what’s known in corporate speak as ‘Inked. (Signed sealed & delivered).

    What I do know from my research is that a group have approached the ADL Board, seeking a corporate takeover via the introduction of $10M of assets/cash. It’s known as a ‘Plug & Play’ package, if that deal happened then ADL would have rocketed upwards, probably over 1p. For whatever reason/s those talks petered out but I can now exclusively reveal that those talks have been reignited with ADL Major Shareholders. Whispers are again surfacing that Major shareholders are now aware and have been approached for the 1st time by well-known successful corporates with a proven track record not only with the drill bit but with increasing SP value for their share-holders.

    Major shareholders were not informed by the Board of ADL on the first approach. I have an ‘idea’ of the names of those corporates having had many cagey conversations with various market sources. The asset/s from one of the groups are rumoured to be Cuban/Mexican. I can’t confirm that but what I can confirm is that predatory moves are almost certainly going on in the back-ground. At what stage they are and if they’ll ever come to fruition is as I said further up in this piece subject to ‘back-room compliance/negotiation’. Nothing is certain until it’s ‘Inked‘ .
    Target ADL?

    ‘Plug & Play as some will recall is what was used on a company called IRG which had a meteoric rise when the new board and initial investment/assets was announced. For a ‘plug and play’ to work any investment group have to find a relatively low value m/cap company £1-4M, to offer the financiers potential multiple returns on initial investment just as IRG did. ADL has a current m/cap of £1.5M , the listing on the exchange itself is worth £600/800K. Cash at hand is circa £500K. Ergo it doesn’t take much to realise why ADL are being targeted, either officially or unofficially. But ‘Target’ they are. Companies at shell value can, on a slither of good news spike, secondly there’s always predatory action in the back-ground that can also re-rate the shell. Hence why I took a ‘slug‘ of shares. Even on no news ADL will slowly tick up.

    So, bearing in mind how convoluted and difficult it is to predict with any degree of certainty the outcome of back channel discussions, I think it’s well worth a small punt.

    Take The Deal!

    As I see it the main sticking point to any deal getting Inked is the current Board who like all corporates don’t want to get off the gravy train unless their nest is feathered with downy £50 notes. I’ve tried to contact the CEO Simon Gorringe many, many times, he has thus failed/refused to make contact. Contact I might add with one of his small Major share-holders. That tells me that Simon is the sticking point to any deal. If you’re reading this Mr Gorringe, then do the right thing for share-holders. Get in-touch with the Cuban/Mexican Plug & Play group and take the deal!

    Worth a small punt!

    Viva!

    Dan

  • Andalas Energy & Power. Honesty Is The Best Policy! Hold For Colter

    Andalas Energy & Power. Honesty Is The Best Policy! Hold For Colter


    Today’s RNS from Andalas Energy & Power (LON: ADL)  all but confirms recent speculation that there are ‘issues‘ on the Bunga Mas (BM) transaction. Now the company will spin that it’s not their fault and the renewal of the PSC from the Government Of Indonesia (GOI) is onerous, but surely after all the ‘fookery‘ from the previous miss-management the new team must know that there are always problems when conducting business in Indonesia. It is par for the course. You can’t sign a PSC unless you have the cash or can prove that you can get the cash. The quality of the licence is immaterial.

    Bunga Mas is a good asset. It has huge potential to flesh out any small oil minnow with real production. I know this because I have been on site and have had access to all the data available to me at that time. Nothing is set in stone when it comes to O&G, but basic economics and how to do business in-country, in Indonesia has to be learned. By now you’d think that ADL would be past masters at it! Investors need to realise that Bunga Mas will progress at the Indo’ pace not the Nutter BB pace. Andalas are not a one trick pony. Investors should hold for the results of the Colter drill, which is like BM, a potential company maker.

    However, credit where credit is due to the Company and their head honcho Simon Gorringe. Who’ve came out and updated the market ‘Pronto’. That may be some what ‘cold comfort’ for shareholders but it does show that being honest, going forward, and updating your investor base in a timely fashion, no matter how unpalatable it may be, is a medicine few like to swallow even when it helps your recovery. So, it’s well done ADL on today’s RNS. Honesty is the best policy. 

    Now remember, Rome wasn’t built in a day. The Colter drill is on track and hasn’t been valued into the ADL SP. Should that come in then I can see the SP heading way over 2p, maybe even 3p. So it’s not bad news today. It’s as you were and let the Board get on running the company in the correct way. Hold for Colter. Common-Sense!

    Viva!

    Dan

  • #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    There’s a ‘hefty‘ lot of  Reabold Resources (LON: RBD) investors/traders out there, awaiting news on the company’s up-coming drills. Wick & Colter. If you don’t know what those drills are then I suggest you get researching because unlike certain other UK Onshore Oilers the RBD drills (Offshore UK) are the real deal. A ‘Roll of the dice’ with a decent chance of success (COS) on BOTH drills, particularly Colter. Which, once they actually get to rig ‘mobilisation stage’ will push this SP much higher. I personally hold some stock here, so am always on the hunt for information. The problem is the company are not releasing the news. Good or bad I publish what it is. You can moan all you want but it’s better to know what’s going on than not. It’s how you make money and it’s how not to lose money. It was pencilled in for a 12 noon release but I’ve been cashiered into 12:30pm ’cause one of the ‘twittermen‘ has to finish his go-karting with the family. What a nice guy I am….  🙂

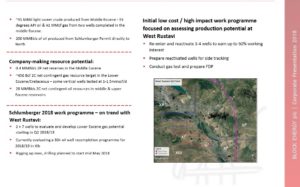
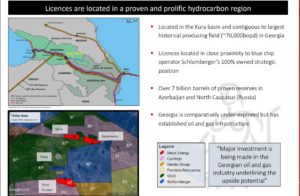
    Now it’s been a long time since I wrote on Reabold and new information has come my way via the BMD ‘sauces‘ pipeline. There’s a major whisper that this company are farming into a Georgian gas asset which is ‘controlled’ by, the soon to IPO, Block Energy. Fortunately I’ve managed to get my hand on not one, but three Block Energy prospectus’. The Georgian gas asset is flagged up as “Substantial potential from 608 Bcf 2C gross unrisked contingent gas resources at West Rustavi, analogous play being tested by Schlumberger in 2018 and 2019 on adjacent licence”

    This is more good news if it comes to pass, as it further flesh’s out RBD with another potential quality licence farm-in. A value driver.

    In the constant hunt for good returns, Reabold, sub 1p, could provide excellent returns. The SP could hit 2p/3p/4p/5p dependent on how successful they are. It will almost certainly break through 1p soon enough.


    Fully funded with a big following and an even bigger following waiting on the side-lines to jump in once the drills start to crystallise as a reality. The placing has been done so unless they’re running a ‘double bluff‘ holders should be able to sit tight and wait for the move upwards. Of course the placing flippers are still at work exiting, however most of them will now be out. Good place to start researching is HERE

    This is going over 1p soon enough. The only question is when? Not if! But as ever do your own research etc. Remember I hold stock as such I could be construed as a Rose Tinted Spectacle wearing leftie… 🙂


    Viva


    Dan


  • Reabold Resources. Placing Ahoy!

    Reabold Resources. Placing Ahoy!

    It’s not looking good for holders of Reabold Resources (LON: RBD). News has reached ‘Yours Truly’ from strong City sources of an orchestrated ramp & dump, pre an imminent Placing. Of course they’ll now deny it and maybe they’ll put it back a week or so. But placing they are…..

    Yes folks there’s a placing on the way for a minimum of £2,000,000+. In fact they need £4,000,000 just to stand still. (Explained Below). I’ve been watching the order book price action over the last fortnight which tipped me the wink that some thing was afoot. On research now undertaken, sources and I mean multiple City of London sources have confirmed that there’s a placing on the way! Which is why some of the ‘choice’ P&Ders are quietly off-loading their positions in-order to reload up in the placing. And make no mistake a placing IS coming! If you don’t believe me then ask the one man band bullshitter Adam ‘Dubious‘ of Jub Crapital the sacked broker of ‘Lord’ @ChrisOil or the House Broker ‘Turner you over Holy Pope’. As a matter of fact ask each one of them to sign a legal binder that RBD aren’t placing. You’ll get the usual ‘corporate waffle’. That’s because they’re selling! Why? Because they’re organising the placing!

    Now that’s not to say that Reabold don’t have potential, I tipped them on J&H and if you’d have listened to me then you’d have made good money. They have a decent story but that story is deliberately being used to sucker in the gullible to keep the share-price up so that they can get away another placing. Well that’s just not ‘cricket’ in my book….

    The last half-yearly report stated RBD had cash in hand of £353,000. The new team of Stephen Williams and Sachin Oza raised a further £5,720,000 in 2 placings ( £3.96M & £1.76M ) which fleshed the company coffers out with circa £6M in cash. In November 2017 £1.5M of that cash was quickly gobbled up via a 35% stake in the private Oil company Corallion. Following on from that in December 2017  a further £1.5M was gobbled up in an ASX listed company called Danube Petroleum to buy a stake of the Parta Gas project. It’s the worst kept secret on the London Alternative Investment Market (AIM) that they’re also looking to bring in another asset, which if they run true to form, will cost £1M+  if we consider the same level of investment in this new asset at say £1.5m that leaves cash at hand of £1.5M. Now don’t forget that the Colter drill is being touted for April 2018. The rig for that will wipe out the cash. Indeed the deposit will do that in itself. Placing.

    KILLER THAT NAILS IT!

    The killer fact that nails the placing is thus: Corallion are currently in the City of Mammon trying to raise between £3.5M-£6M to fund drilling of their UK license P1918 which includes the “Colter” asset. If Reabold don’t want their 35% stake heavily diluted then they will have to come up with at least £1.6M-£2.1M in cash to keep their 35% stake of Corallion and the assets. This would then leave Reabold with a negative balance of -£590,000!

    PLACING

    Answer. A Casino! Where the House (Corporates) tell lots of lies…

    Common sense dictates that to keep the lights on with say £1m cash at hand Reabold will need to raise at least £1.6M that’s before any cash calls from Corallion or Danube for project development and cash calls will come. Placing. To keep the company progressing its investment opportunities the company must raise £4m! Which is why they’re secretly trying to keep the SP up. Expect lots of ramptasic horse shit with denials from paid promoters. Then a placing.

    Shares are trading circa 0.65p which gives a market cap’ of just over £10m.  Cash raised will have to be at a discount which is par for the course on the AIM Casino. That means a potential whopping 20%-40% discount to current levels.

    Sell & buy back in the Placing. Because that’s what the P&Ders are sneakily doing!


    Viva!


    Daniel

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights