google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Congo

  • Zenith Energy. Congo Update!

    Zenith Energy. Congo Update!

    Just a quick update on Zenith Energy (LON: ZEN). Those that follow this blog will be aware that I’ve been tracking the company for quite some time. You’ll also be aware that, unlike others, who’ve told a pack of lies and have ‘flooded’ the super information highway with malicious musings, which have been completely wrong, ‘Yours Truly’ has called this stock correctly as well as the ‘machinations’ within, outside and online ‘correctly’.

    Zenith has a range of assets: Tunisia, Italy and the one that should interest you, Tilapia, situated in the The Republic of the Congo. For those that don’t know the Republic of Congo is one of Sub-Saharan Africa’s largest oil producing countries with circa 1.6 billion barrels of proved crude oil reserves, 3.2 TCF of proved natural gas reserves, and a daily production of approximately 300,000 barrels of oil per day. It has an established history of prolific oil production operations, specifically by majors including ENI and Total who have been operating in-country since 1968.
    Now I like Tilapia, I think it’s a ‘company maker’ and the chance of success (COS) is certainly much higher than is understood at present. And here’s one of my reasons. The Align Research Note on Tilapia when the licence was held by AAOG, African Oil & Gas. This is what Richard Jennings wrote in January 2019:

    "Anglo African Oil & Gas (AAOG) joined AIM in March 2017 and
    subsequently acquired a 56% stake in the Tilapia Field in the Republic of
    the Congo for US$5 million. This was a cracking deal as Tilapia is a proven
    producing asset with substantial upside potential in the Lower Congo
    Basin, an established and prolific location for hydrocarbons. Multiple
    discoveries have been confirmed from the TLP-103C well in the R2 and
    Mengo reservoirs and now the well is being drilled deeper.
    Mengo discovery and R1/R2 look set to boost production to 750 bopd
    A 44m oil column in the Mengo has been confirmed - nearby fields produce
    500 bopd per well with stimulation. Experts believe that 400 bopd is
    achievable with water flooding from the TLP-101. Added together, this
    suggests a minimum of 750 bopd, making AAOG nicely cash flow positive.
    Djeno is the big prize and success here could be transformational
    TLP-103C is now targeting the Djeno, a reservoir where Eni, TOTAL, CNOOC
    & SOCO are all producing nearby at a naturally pressurised 5,000 bopd per
    well. Even if AAOG miss it this time round, lessons learnt will be invaluable
    in drilling TLP-104, planned to be drilled back to back with TLP-103C.
    Existing infrastructure allows discoveries to go into production rapidly
    AAOG is shaping up to be a profitable company, even ahead of any success
    in Djeno. The company benefits from having existing topside infrastructure
    which allows the team to quickly turn confirmed resources into production.
    Risked NPV suggests upside of more than 170%
    Our conservative valuation shows the potential. We initiate coverage of
    AAOG with a first target price of 28.23p and a Conviction buy stance."

    And here’s what FinnCap wrote in June 2018

    "3 in 1 oil. This well is targeting three separate reservoir horizons with a range of risk/reward – low risk appraisal of 2mbbls of producing reserves in the R1/R2 sands (6.3p/sh), appraisal of an 8-24mmbbl undeveloped discovery in the Mengo sands potentially worth 18-45p/sh on a risked basis, and a deeper exploration prospect in the Djeno sands, assigned gross prospective oil resources of 16-42mmbbls. This final target carries higher risk (25% CoS) but also higher reward. Our risked valuation range for the Djeno of 16-39p/sh rises to 69-159p/sh when fully de-risked."

    So, regardless, of who wrote what and when it was written, the value which was assigned to AAOG by the two research notes is by irrefutable ‘Vulcan logic’ transferred to Zenith Energy. To say that this point has been lost in the vitriol that’s plagued ZEN is an understatement. Tilapia is a big play with potential oil flows of 1,000 bopd, from a low case of 26M barrels to the high case of 5,000bopd from circa 70M barrels of oil.

    Further more you may have noticed that a delegation from Congo was in Italy having meetings with Zenith and were visiting the companies Italian gas assets. I’m hearing that the delegation went away impressed with the site visits and the company’s abilities in the O&G sector. Now that’s important because there’s further upside in Congo vis-à-vis Congolese gas and it’s my gut feeling that Zenith will be invited to take part as a preferred bidder in any licence rounds that may come up in the future. 

    So with all that said I’m currently trying to arm twist Zenith Energy into allowing me a site visit to Tilapia. It’ll more than likely fall on deaf ears but should it happen, I’m now throwing out a challenge to ‘The ShareProphet’, Tom Winnifirth. I will foot all Toms costs if he wishes to accompany me to the Tilapia  drill site in the Republic of The Congo. Do please pass it on to Tom.
     

    Viva


    Dan


  • ShareProphets, Tom ‘Pepper’, Red Faces All Round on Zenith Energy!

    ShareProphets, Tom ‘Pepper’, Red Faces All Round on Zenith Energy!

    It’s an absolute shocker today for the ‘erstwhile’ writers at ShareProphets and Mr Marmite, Tom Winnifrith.
    For month upon month over a considerable period of time, they’ve ran ‘interference’ (LIES) on Zenith Energy & the CEO Andrea Cattaneo. A campaign of spite and hate has today been exposed by Zenith’s successful award of the Tilapia2 Congo licence.

    For those unfamiliar with the ShareProphets ‘Jackanory’ here’s the basics. TW has been attacking Zenith at every opportunity not only by claiming numerous times on ShareProphets & Twitter that the company had lost it’s Tilapia licence but by constantly making unfounded complaints to the FCA. The campaign has culminated in decimating the Zenith Energy SP, to all time lows, Shareholders have paid the price and lost huge amounts of cash on the, to put it mildly, ‘Ravings’ of Tom that Zenith had “lost the Tilapia licence.” 

    I warned Tom that his ‘Ravings‘ were inaccurate not only damaging to Zenith but their Shareholder base. Zenith never ‘lost the licence’, they were in a renegotiation with the Republic of Congo. At worse and at best, It was a binary outcome. However to refuse to change course, away from the lies and objectively ‘tell it as it is’ has now resulted in one almighty embarrassment for ShareProphets & Red face TW. ‘Cause believe me Tom Winnifrith will be cringing today.. Oh to be a fly on the wall at Winnie Towers….

    If they had told it as it was the SP of Zenith would probably be 2/3p today. There failure is a failure of truth. To ‘bear false witness against they neighbour’  serves nobody, especially when it comes from several malcontents who were feeding your ego with spurious lies, greedily swallowed by ShareProphets for nothing more than clicks & subscriptions. But that ‘Click Bait’ has now come full circle to bite your arse. Did I tell you Tom or did I tell you?

    Tom Winnifrith now owes each & every Zenith shareholder an apology. A full ‘mea culpa’ with an even bigger personal apology to the CEO who has conducted himself with gentlemanly aplomb.

    But don’t hold your breathe, the only thing that’ll come will be Weasley words…

    Time to ‘fess up’ Thomas Pepper, admit that you got it wrong ‘Bigly’. Pack in the Hate Campaigns. Base your articles on known, verified parameters.

    Then you too can be like me. Telling it as it is, good or bad. The Truth will set you free! 


    Viva


    Dan

    x


  • Zenith Energy Update. Binary Play….

    Zenith Energy Update. Binary Play….

    It was good news yesterday for the much beleaguered UK and Norwegian shareholders of Zenith Energy (LON: ZEN). The Company returned from their self-imposed suspension after the audited financial results for the year ended March 31, 2020 were released. And lets face it, 2020 hasn’t been a ‘vintage’ year for the markets in general, not least the Oil & Gas sector which is still struggling to come to terms with the Global Covid 19 pandemic and a wayward (Falling) oil price.

    So, that being said lets get into the nuts and bolts. As I see it at the moment for me it’s a binary play. I’m stripping out Tunisia, Nigeria etc. The jewel in the crown is Congo, reports of the loss of the Tilapia licence have to coin a phrase ‘been greatly exaggerated’. The Congo licence expired as per the terms of the licence. (Which was known by every serious O&G investor, writer and market watcher before ZEN bought it for peanuts).

    It’s custom & practice on ALL O&G licences, they expire. Standard operating procedure on expired licenses is a renegotiation if both parties,  Ministry of Hydrocarbons of the Republic of the Congo and Operator wish to go forward. That’s exactly where things are as of today! There’s also the small matter of the return of $5.3M back to the Company, which has to be, again, negotiated.

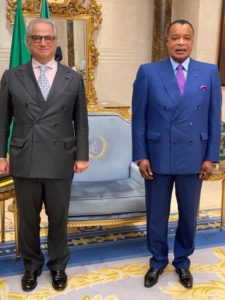
    Mr ‘Zen’ & Congo President Denis Sassou Nguesso. He gets about does Cattaneo!

    One, even begrudgingly, has to admire the dedication of Andrea Cattaneo (CEO), in spite of the ‘relentless Tom Winnifrith hate campaign’ he’s been ‘in situ’ Congo for over 6 weeks working tirelessly for his shareholders. I spoke to him yesterday.

    To give you an idea of his schedule; 7am Business correspondence, transport organisation for various government meetings. 9am Breakfast. 9:30am-4pm is taken up with various visits & meetings with government depts. Once back at his hotel he liaises with Tunisa, Nigeria etc For updates and also updates staff at the ZEN office. 5;30pm late lunch, 9pm shower, light meal, then more calls and email correspondence 11pm bed. Wake up start again. That’s a gruelling schedule in 30 degree heat. So let it not be said that ZEN are sat on their arses….

    Should Zenith Energy come back with the goods then their SP will rocket. Tilapia is potentially the make or break deal. I can see see 2p-4p with the proviso of a successful outcome.

    As I understand it negotiations are soon to be concluded. That’s the ‘binary play’.

    ‘Ya pays ya money ya takes ya chances’.


    Good luck


    Dan


  • Anglo African Oil & Gas  Watchlist/Research!

    Anglo African Oil & Gas Watchlist/Research!


    HomeApologies to all this one should have gone out on Jekyll & Hyde pre-IPO.  Unfortunately the ‘Securitate’ deemed it too sensitive and conflicted. Hence why it’s now going out on Guerilla Investing. Some minor changes post IPO… You can join the UK’S Premier Tip Sheet Jekyll & Hyde by CLICKING HERE

    Get Anglo African Oil & Gas (LON: AAOG) on your watch lists and research it! START HERE. They came to market yesterday. What I like about this one is that the placing ended up hugely over-subscribed.  It’s always a good sign. They have great potential  going forward very quickly to increase production in 2017. The management are a decent lot and have been working for two years on their IPO. The Directors intend to distribute free cash to shareholders through regular dividends, once production reaches a sustained level of 1,000 bopd and provided that oil prices are not less than USD 30/barrel. Now that’s some thing no other AIM oiler will do. It’s a good pointer. Also some of their close neighbours such as ENI have production of circa  5000 barrels’ a day from basically the same geology/horizon as Anglo plan to drill.

    Anglo currently produce 38 bopd but it is in their potential to increase this to circa 750-5,000 bopd that could push their SP much higher. Now if they get anywhere near this figure then the SP will correspondingly move upwards. Everything is now in place. Assets, infrastructure, funding and more importantly sentiment. Which is very strong. The only drawback when I first penned this piece was their website which looked like it’s came out of Noah’s Ark. Thankfully the powers that be responded to this concern and updated it to a nice healthy one. In line with the rude health that AAOG are now in.

    The assets are located in the Republic of Congo (RoC). Development of the near offshore Tilapia field could significantly increase production in the near term to circa 250/750bopd. “The company also aims to conduct exploration and appraisal of proven deeper reservoir targets to raise production to in excess of 5,000bbl/d in the medium term. The acquisition of Petro Kouilou would result in AAOG gaining extensive onshore surface infrastructure comprising: 5,000bbl storage tank, separator, in-field pipelines and other associated facilities. These facilities would cost US$15-20m if they were constructed today. Consequently, the company will not need to spend any other capex than that associated with the proposed work programme. The new wells can simply be connected and new production can brought onstream almost immediately.  Low-cost workover programme. AAOG intends to workover two wells on Tilapia field at a cost of US$300,000 which would increase production from 38bbl/d to 250bbl/d. On the assumption of a successful IPO this work would be conducted during 2017.”

    So the drivers of the share-price are many and varied. There’s existing production, increasing production, multi million-barrel potential from existing production and multi million-barrel exploration potential. The IPO price was 20p. If you can get in as close to this as possible then hold for news on increasing production/exploration. How high could it go? On any where near 5,000bopd it will rocket. On a bread and butter 250-750 bopd it should get to 50/60p. 25p-40p should be your near term target. Remember profit is the game. It doesn’t matter if you make £100s or £1,000s derisk as you go. Good solid little oiler that could/should be financially self -sustaining by the end of 2017. By that time the bopd will be many multiplies of where it is today.


    Viva!


    loginDan


google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights