google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Debt

  • Nostra Terra Oil & Gas. Fraud with a capital ‘F’. ‘Gone for a Burton’.

    Nostra Terra Oil & Gas. Fraud with a capital ‘F’. ‘Gone for a Burton’.

    Investors really need to take note of the lies and deceits of the well known fraudster and liar running the scam that is Nostra Terra Oil & Gas ((LON: NTOG). I’ve high-lighted this POS many times and each and every time I have been correct. Two weeks ago the Ex Estate Agent Mormon shyster, (Twat) Matt Lofgran, was running around with that other well known shyster outfit Total Market Shite (TMS) telling all & sundry that they would not be raising money and didn’t need too. While at the same time organising another placing. This was tweeted, posted and cowboy-casted out over all the financial platforms by the paid P&Ders.
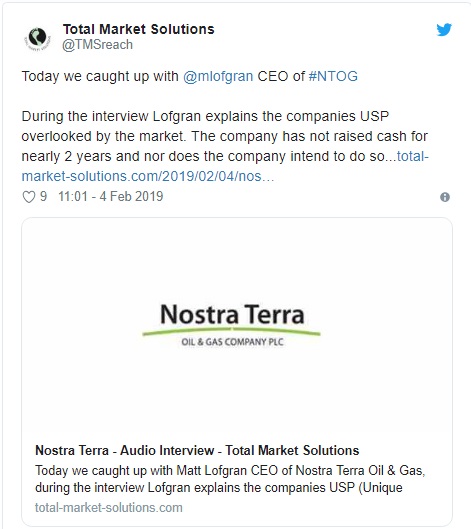
    Lies, Lies & More Lies….
    Total Market Shite! Strikes Again!

    Total Market Shite is the brain-child of one Mr David Burton, who was booted out of Vox Markets, when they decided to clean up their act severing all ties with him & the P&Ders he’d introduced to the Vox platform. Now that’s fact. So it should be no surprise that TMS and the Burton Pump & Dump crew all found comfort together again taking payments from shyster companies, like Nostra.

    Misleading investors into proven shite companies, taking backhanders, trading the stock while heavily promoting company changing events is nothing new. The best way to think of it is as a bit like the ‘Time Share’ scam. Suckers get sucked in, fed horse-shite, part with cash. Leave with a head full of magic clutching worthless timeshares, then get wiped out. It’s only after the event reality bites. The scam moves on focusing on the next set of suckers. Rinse repeat ad-infinitum.
    The Crook Of Mormon.

    The simple truth on Nostra is as plain as the nose on your face. Lofgran has raped, lied & deceived gullible investors in the company for 10yrs. He’s wasted tens of millions of your cash. It’s had more bullshit assets, trumpeted as company changing plays than you’ve had hot dinners. RNS’s galore, Placings galore, Consolidations galore, Dilution galore. Debt galore, Assets galore. Production has never ever covered costs. It’s stripper well production. Marginal, exhausted fields/wells bought for a few thousand dollars to ‘Flesh out’ the ‘Jackanory’ are never going to transform a company. It’s cash burn out-strips it’s highly costly minimal stripper well production. It will always dilute and place to raise cash because there’s always debt. Here’s a prediction. Shares in issue will yet again double from where they are now. Then they’ll double again eventually breaching one billion etc. etc. etc. That’s the ‘Modus-Operandi’. Rinse repeat Mug Punters and always keep changing the ‘Jackanory’.

    Take some advice all you ADVFN/LSE/III Posters. Walk away there are plenty of decent oilers out there. This isn’t one of them. It’s a Fraud with a capital ‘F’.

    If you had invested £100,000 in Lofgran on day one of his tenure then you would have less than £100. You put money into NTOG then you will ultimately lose the lot. It’s run by a liar who shorts his own company and will carry on diluting and placing until you’re all ‘Gone for a Burton’.

    Work it out!

    Viva! Dan
  • Nostra Terra Oil & Gas Same! Same! Ramp, Pump & Dump to Disguise MORE DEBT!

    Nostra Terra Oil & Gas Same! Same! Ramp, Pump & Dump to Disguise MORE DEBT!

    Oh what a difference a day makes…  Yesterday the lying CEO of Nostra Terra Oil & Gas (LON: NTOG), Matt Lofgran the ex estate agent released an RNS. In yet another attempt to ramp the company share-price in-order to get the NDOG SP to a place that could allow him to pass the begging bowl around yet again. Make no mistake NTOG are desperate for cash and running on vapours. They will place as soon as they can get one away.

    Liar! Liar! Shorts his own company! Secret Payments to Ben(T) Turney

    The history here is one of total pump & dump, lies, ramp, secret payments to twitter supporters, shorting their own stock, placing upon placing, dilution upon dilution, consolidation upon consolidation, debt upon debt, flogging off assets to keep the lights on as well as failing to report the 50%/60% decline in East Ghazalat oil production, we’ve had the utter fantasy that is Pine Mills, a clutch of Stripper Wells onshore USA marketed as the next best thing since sliced bread. Stripper Wells are marginal wells deemed at the end of their economic life. Each well at Pine Mills is producing a few barrels of oil a day. They need constant workovers which again is capital intensive. The CAPEX spent by far out strips the return. They will never be in profit in the near, not so near or even the foreseeable future. Then there’s the ‘Eye of Sauron’, yes the AIM Regulation Team who’ve been inundated over the last 2 years with complaints regarding the Shysterism perpetrated by Lofgran. The exposes on shorting his own company, making secret payments to the self confessed drug dealer Ben(T) Turney. Jesus the list is endless.

    The usual paid for mouthpieces were out in force tweeting and podcasting hammering the BB boards with the usual utter shite. The SP had a spike to way over 3p. Today the sp is in freefall as the reality of exactly what a hedging facility is and why they have to have it sinks in. They are taking on more Debt because they have no cash and production is down to slurping out a few barrels of oil out of 20/30 stripper wells. No revenues from East Ghazalat which is mired in legals, debt and accusations of fraud with a declining production of over 50%.

    Nostra Terra Oil & Gas haven’t got a pot to piss in and on top of the massive Debt that they already have, they’re taking on more Debt. Their liabilities and historical losses are in the tens of millions of dollars. That is a fact. So the hullabaloo about a hedging facility can be summed up in a Nutshell. One of the terms and conditions to taking on yet ever more Debt is having the facility that helps to protect the Lender not the Company! A hedging facility works thus: NTOG pay fees to the provider of the hedging facility to insure that if the oil price drops below lets say $50 per barrel to $45 then the provider of the hedging facility makes up the difference i.e. They pay the shortfall which would be $5 per barrel. NTOG have to pay all oil revenues to their new Lender to not breach the new Debt Agreement and pay their hedging fees regardless of where the oil price is. Not exactly a game changer is it? Back to where you came will go the SP. Below 1.5p. Worth about 0.50p listing value only. Beware of the ever present danger here. They’ll Place as soon as they can get one away.#POS

    It is yet another ruse to sucker in the BB poltroons and Melts. There’s ‘nowt’ quite like a BB Loon they’ll believe any old shite and pile in like the uneducated lemmings they are. Just another pump and dump. The dose of reality, although hard to swallow, usually takes a few days to be digested.

    Which in turn helps to flush out the stomach and we all know what comes out the other end…. 💩

    Viva


    Daniel

  • Bloodbath on the way. CEB/Andalas

    $600,000,000 FANTASYMAN
    $600 Million Dollar Fantasy Man. No wonder he’s smirking!

    Followers will recall that we published a piece over the weekend on the sham being perpetrated by the fantasy $600,000,000 man Dave Whitby. You can read that piece HERE.

    News has dropped from City of London sources that there’s yet another almighty ‘Kick up the AndalARSE’ on the way for holders of this POS. There’s a massive dilution about to drop. Over £2,600,000 worth of discounted shares at 0.45p-0.50p. That means that shares in issue, if it goes ahead, will be fast approaching 1.5 Billion. God only knows what warrant packages those involved with the massively discounted grab for cash will be.

    We do know that Corsair, the private company run by Whitby & his cronies, will trouser approx., 230,000,000 on top of the 31,250,000 shares they’ve already trousered. Punters do not know what other fees in cash Corsair have had? The Reverend Tom Winnifrith has beat me to the line on this. You can read what Tom has discovered HERE

    It’s going to be a bloodbath. Those foolhardy enough to have kept holding are now locked into the ticking time bomb that will explode very soon. They’ll need a 130% rise or (and a big almighty non-stop ramping campaign) thereabouts to get back to where it was pre suspension, if they relist at 0.45p/0.5p. Bearing in mind the low quality of the unproved, undrilled, Indonesian gas asset that’s in the pipeline. Value $1,000,000, It’s a case of hope rather than fact that CEB/Andalas will finish the day with a market cap of £20,000,000+. The real post readmission value, is cash at hand, listing value, plus asset. Which is approx. £2.5M. Being generous that equates to an SP of 0.20p or thereabouts.

    The Pumpers and Dumpers will be out in force on RELISTING DAY. Remember some of those are sat on massive losses and would eat dog shit live on National television if they thought it would push the SP up.

    Stay well clear. It’s a Bloodbath. Get in the popcorn.

    Viva

    Dan

    In for the spin.

  • ADL/CEB Another ‘TOE in the AndalARSE’ for Shareholders!

    EDL Pumpers & Dumpers!

    News on Andalas Energy ( LON: ADL) or AndalARSE as I like to call them, could be about to drop. Investors will remember it traded as the mega ramped pumped & dumped CEB Resources. It was, as CEB, a major disaster for those gullible enough to fall for the bullshit of the BB and twitter P&D crews, who were being whipped up into a frenzy by off record ‘title tattle’ from various people/organisations associated with the then CEB. One moron claimed that Whitby had turned NIDO Petroleum into a $600M company.  While others were spinning it as a $600M takeover. Complete Bollocks.

    Under AIM rules the company have to publish a readmission document in a matter of a week or so, otherwise it’s ‘goodnight Vienna’ off the AIM it will go. $600,000,000 fantasy man CEO Dave Whitby, is reputed to be offering all kinds of financial packages on broker fees, warrants and options in-order to grab the cash. The company recently got out of a bankruptcy hole when raising £500,000 of super expensive debt on March 31 2016 – Tom Winnifrith, the respected City of London financial journalist, described it as “The most expensive debt in AIM history”. You can read his article HERE. That debt is convertible into shares if Andalas relists, and the whispers are that the £500,000 now paying for the RTO and bloated PLC costs will not be the only dilution should they relist. A further £2/3 Million of hugely discounted shares may follow. That’s very bad news for those left holding shares in the suspended cashless, asset less, shell.

    $600,000,000 FANTASYMAN
    $600,000,000 Fantasy Man

    AndalARSE have no assets whatsoever other than some Indonesian options on options, assignment agreements and concession agreements. Any and all of those paper agreements will cost millions to sign off and work. Money they simply, as of yet do not have. Should they relist with a £2/3 Million super dilution then as sure as night follows day they will very quickly burn through it. The heads of terms agreement signed to acquire a 30% working interest in the aptly acronymic ‘TOE’,  Tuba Obi East oil and gas concession, will relieve them of approx. $1,600,000 which as we all know will rise substantially, this doesn’t add in the bloated PLC and corporate payments going into the pockets of the company and its advisors. Ergo de facto they’ll be looking to raise further capital within a matter of months of relisting.

    What’s interesting is that Corsair Petroleum, owned by team Whitby have already pocketed 31,250,000 CEB shares and have share payments waiting of 34,344,865 ordinary shares exercisable at 0.4p per share until the third anniversary of the Assignment Agreement (“Options”). In the event that Corsair is successful in the acquisition of at least one concession, CEB will issue up to 93,750,000 ordinary shares in CEB and up to 103,034,596 Options in three equal instalments. So Whitby, and cronies, in Corsair will be trousering over 270,000,000 shares. For little more than an introduction! Which again will further add to the dilution… and enrich the $600,000,000 fantasy man.

    The sensible should ‘Exit left’.

    The pump and dump fest from the usual names will begin almost immediately on twitter and the financial BB sites on relisting.

    Avoid the Whitby ‘TOE in the AndalARSE’ Do not be suckered into this POS.

    Viva

    Dan

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights