 Just a quick update on Zenith Energy (LON: ZEN). Those that follow this blog will be aware that I’ve been tracking the company for quite some time. You’ll also be aware that, unlike others, who’ve told a pack of lies and have ‘flooded’ the super information highway with malicious musings, which have been completely wrong, ‘Yours Truly’ has called this stock correctly as well as the ‘machinations’ within, outside and online ‘correctly’.
Zenith has a range of assets: Tunisia, Italy and the one that should interest you, Tilapia, situated in the The Republic of the Congo. For those that don’t know the Republic of Congo is one of Sub-Saharan Africa’s largest oil producing countries with circa 1.6 billion barrels of proved crude oil reserves, 3.2 TCF of proved natural gas reserves, and a daily production of approximately 300,000 barrels of oil per day.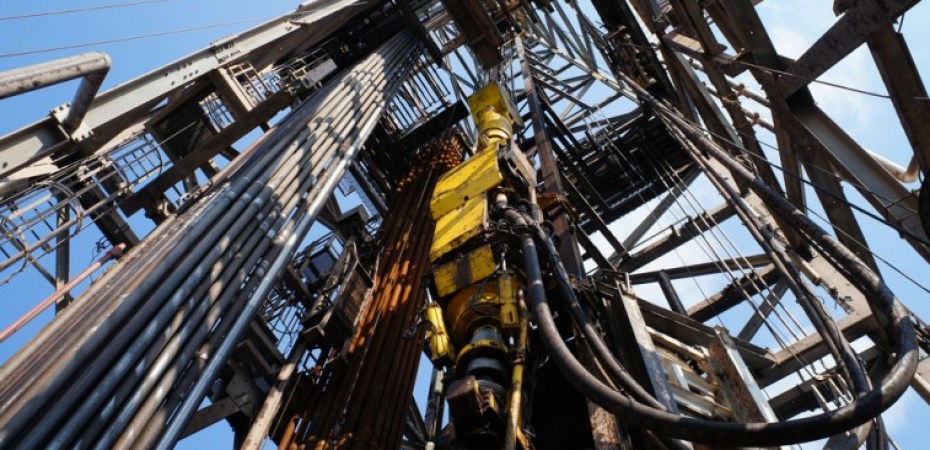 It has an established history of prolific oil production operations, specifically by majors including ENI and Total who have been operating in-country since 1968.
Now I like Tilapia, I think it’s a ‘company maker’ and the chance of success (COS) is certainly much higher than is understood at present. And here’s one of my reasons. The Align Research Note on Tilapia when the licence was held by AAOG, African Oil & Gas. This is what Richard Jennings wrote in January 2019:
"Anglo African Oil & Gas (AAOG) joined AIM in March 2017 and
subsequently acquired a 56% stake in the Tilapia Field in the Republic of
the Congo for US$5 million. This was a cracking deal as Tilapia is a proven
producing asset with substantial upside potential in the Lower Congo
Basin, an established and prolific location for hydrocarbons. Multiple
discoveries have been confirmed from the TLP-103C well in the R2 and
Mengo reservoirs and now the well is being drilled deeper.
Mengo discovery and R1/R2 look set to boost production to 750 bopd
A 44m oil column in the Mengo has been confirmed - nearby fields produce
500 bopd per well with stimulation. Experts believe that 400 bopd is
achievable with water flooding from the TLP-101. Added together, this
suggests a minimum of 750 bopd, making AAOG nicely cash flow positive.
Djeno is the big prize and success here could be transformational
TLP-103C is now targeting the Djeno, a reservoir where Eni, TOTAL, CNOOC
& SOCO are all producing nearby at a naturally pressurised 5,000 bopd per
well. Even if AAOG miss it this time round, lessons learnt will be invaluable
in drilling TLP-104, planned to be drilled back to back with TLP-103C.
Existing infrastructure allows discoveries to go into production rapidly
AAOG is shaping up to be a profitable company, even ahead of any success
in Djeno. The company benefits from having existing topside infrastructure
which allows the team to quickly turn confirmed resources into production.
Risked NPV suggests upside of more than 170%
Our conservative valuation shows the potential. We initiate coverage of
AAOG with a first target price of 28.23p and a Conviction buy stance."
And here’s what FinnCap wrote in June 2018
"3 in 1 oil. This well is targeting three separate reservoir horizons with a range of risk/reward – low risk appraisal of 2mbbls of producing reserves in the R1/R2 sands (6.3p/sh), appraisal of an 8-24mmbbl undeveloped discovery in the Mengo sands potentially worth 18-45p/sh on a risked basis, and a deeper exploration prospect in the Djeno sands, assigned gross prospective oil resources of 16-42mmbbls. This final target carries higher risk (25% CoS) but also higher reward. Our risked valuation range for the Djeno of 16-39p/sh rises to 69-159p/sh when fully de-risked."
So, regardless, of who wrote what and when it was written, the value which was assigned to AAOG by the two research notes is by irrefutable ‘Vulcan logic’ transferred to Zenith Energy. To say that this point has been lost in the vitriol that’s plagued ZEN is an understatement. Tilapia is a big play with potential oil flows of 1,000 bopd, from a low case of 26M barrels to the high case of 5,000bopd from circa 70M barrels of oil.
Further more you may have noticed that a delegation from Congo was in Italy having meetings with Zenith and were visiting the companies Italian gas assets. I’m hearing that the delegation went away impressed with the site visits and the company’s abilities in the O&G sector. Now that’s important because there’s further upside in Congo vis-à-vis Congolese gas and it’s my gut feeling that Zenith will be invited to take part as a preferred bidder in any licence rounds that may come up in the future.
So with all that said I’m currently trying to arm twist Zenith Energy into allowing me a site visit to Tilapia. It’ll more than likely fall on deaf ears but should it happen, I’m now throwing out a challenge to ‘The ShareProphet’, Tom Winnifirth. I will foot all Toms costs if he wishes to accompany me to the Tilapia drill site in the Republic of The Congo. Do please pass it on to Tom.
 Viva
Dan