It’s time to get the popcorn in. Tom Winnifrith’s ShareProphets are going for the ‘Zoetic jugular’. Claims of Corporate malfeasance are now doing the rounds at The FCA, City of London, as well as Stateside, The Food & Drug Administration who, make no mistake, are both investigating the ‘ShareProphets Zoetic Dossier‘, which I might add looks DAMNING….
Dossier Link
Claims of health benefits on their website have ‘vanished’ into thin air…. For those of you that don’t know the history here it’s basically TW claiming Corporate wrong doing on an Industrial Scale; “An attempted mass cover up of multiple LIES told to regulators, investors and consumers”. A share price rise from 3/4p to 82p in the space of 12 months on sales of ‘nuppence’
Zoetic Revenues
£81,000 in the 12 months to September 2020 and only £450,000 cash. The Market Cap’ is a whopping £162m, their SP is 83p as of writing. There’s no way on God’s green earth, that this valuation is based on fundamentals or reality. Even on sentiment or ‘Hope Value’ it’s an affront to ‘Vulcan logic’.
TW 60 Red Flags Link
ShareProphets state; “A multitude of red flags across the business have been identified”,. The rise now sits at 2400%. on a CBD infused chews & smokable cigarettes, business. ShareProphets give Zoetic (LON: ZOE) a 5p valuation based on contemporaries in their sector.
In Zoetic’s defence they state that their ” ‘Prepare for Lift Off’plan, works in close partnership with distributors to orchestrate a successful rollout and to implement best practices across appropriate marketing, trade spend, advertising, in-store display, education, and speed to market.”
The Financial Advisor is Allenby, people that follow me, or ShareProphets will note that Allenby, the well known AIM Nomads, will be taking the SP allegations seriously. They’ll also know that TW is usually correct, having came up against him many times. Whoever is ‘chewing’ or blowing CBD smoke up the retail investor arse, you can be assured Allenby will get to the…… ‘Bottom’ of it…
Tom Winnifrith is very well known and feared, regardless of what some may think, he has a huge following both Retail & Corporate, having exposed major ‘Jiggery Pokery’ at Globo, The Woodford Fund and Quindell to name but three. CEO’s, Journalists, Brokers, Directors, Analysts and even the BBC, SKY, Russia Today etc Make pilgrimages to his ‘Welsh Hovel’.
His phone never stops ringing and his email never stops pinging. I know this because I’ve witnessed it on numerous times, in person.
It’s Groundhog Day once again at ShareProphets……..
Not so long ago Tom Winnifrith had to boot out his editor Ben(t) Turney, after ‘yours truly’ exposed his drug dealing to teenagers the length and breadth of the United Kingdom. The Drug Dealer who rode into ShareProphets…. Of course TW being TW he publicly defended ‘Druggie Boy’ then quietly gave him the order of the boot several weeks later. On the plus side Turney was man enough and had the ‘guts’ to admit it.
So lets see how Tom deals with this one.
It’s an absolute fucking scandal.
First let me state that I don’t believe ShareProphets knew that one of their ‘Financial Commentators’ and I use that term VERY loosely, has been operating ‘covertly‘ pumping, dumping and ramping stocks masquerading as a ‘mug punter. It’s been going on for at least 2 years
‘STINKY PETE’ BRAILEY
“Ohoo what a wicked web we weave when we practice to deceive”
Take a bow gobshite ‘Stinky Pete’ Brailey who anonymously posts on a whole host of financial BBs, while failing to declare his identity as a Paid ShareProphets hack.London South East being Stink’s current favourite.
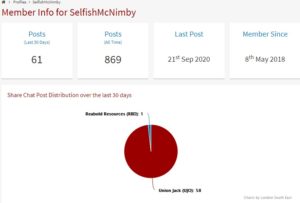
A quick check of Brailey’s ‘covert’ LSE account ‘SelfishMcNimby’ reveals that the operation began in May 2018 the anonymous account is a litany of Pumping & Dumping, dependent on his interest/financial position taken. No doubt Stinky Pete has correlated his ‘Attacks’ and ‘Big Ups’ of London listed companies in tandem with his ShareProphets & twitter ‘musings’. There are nearly 900 posts on that one fake account.
As I’m sure Tom Winnifrith is aware: In the world of journalism, especially financial, it’s a deliberate deception for any journalist, blogger, writer, columnist, amateur or professional, to anonymously post ‘copy’ good or bad on investments, regardless of whether they invest, short or not. There’s also the small matter of FCA Market Abuse Regulations (MAR), as well as bringing ShareProphets into disrepute. Stinky has been working at ShareProphets for just over a year.
A quick check of Braileys’ twitter reveals he’s following and followed by virtually every known PUMP & DUMPER. In 1 tweet Brailey accuses Malcolm Graham Wood of being ‘Compromised’. Well how compromised are ShareProphets now?
Of course Stinky Pete will deny it when confronted by ShareProphets of that there’s no doubt. You can take it as read it’s him!
There are a whole raft of unanswered questions for the ‘Holier Than Thou’ TW. Not least, are there any more SP ‘Financial Commentators’ balls deep in ‘other’ covert operations not only attacking companies as well as trolling (mostly) small time UK punters trying to make an honest gain?
This will come as a shock to Tom and I expect he’ll do the right thing if he wants his platform to remain free of scandal: Your paid financial commentator has been deceiving UK Investors on financial Bulletin Boards and the ShareProphets platform.
I’ve been sat on some of this information for quite some time, as a matter of fact since 21st April 2018. Now remember that date, (which I’ll explain later down the thread). I’ve been waiting for a big enough example of the disgraceful, wholesale lies and fraud perpetuated by the main ‘players’ to appear and yesterday’s Nostra Terra Oil & Gas (LON: NTOG) so called ‘MM short’ that has been pumped out over the twitter and BB sphere now gives me the easiest example of the many failed Pump & Dump attempts this lot have perpetuated (not only on NTOG) on the gullible investors/traders, that can be duped into swallowing the utter ‘horsepox’ the band of not so ‘Merry Men’ perpetually scream online.
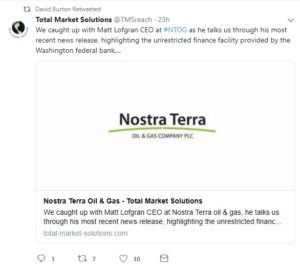
Yesterday and no doubt today, which isn’t the first and won’t be the last, there were five accounts on twitter and various accounts on London South East & ADVFN, pushing yet another Nostra Terra Oil & Gas SP manipulation. Come on down the ex-Vox booted director David (pay me, I’ll Ramp 4U) Burton, ably assisted by his ‘Clowns’ Ben Turney, Alex McKinley & Mikey Whitlow and last, but not least the NTOG shorting CEO, proven Liar and bullshitter Matt ‘scumbag’ Lofgran. All five are on twitter and four of the named individuals have separate platforms that blast out utter spurious guff, masquerading, as financial AIM market commentary 24 seven.
Apparently, according to ALL of the above, including the CEO of Nostra there’s a Market Maker (MM) short of stock in NTOG, inferring a ‘short squeeze’. One may ask how all 5 of these chaps came to that CONclusion? Bearing in mind that there’s absolutely no truth whatsoever to this unsubstantiated claim. Just quite what a CEO is doing on twitter stating such nonsense breaks every AIM rule in the book on sensitive financial disclosures…
Well let me tell you. On the 21st April 2018 the day of the UK Investor Show, four of the above met in a public house (Mr Burton, Mr McKinley, Mr Whitlow & Mr Turney) where they agreed, among other things, to form a ‘mutual self-help society‘ i.e. they made a pact and conspired to ‘Promote’ each other’s tweets and blogs/articles/podcasts. Sources who witnessed it also tell me that they believed they could become a force greater than ShareProphets. The deluded ‘Wannabees‘ thought they were going to take over the world of micro-‘crap’ info……
The terms of said ‘Clown Pact’ were/are to retweet and back up each other’s tweets/blogs/news/articles/podcasts. If you check all four twit timelines, (Deletions galore post this blog) you’ll notice an unhealthy correlation between ALL four accounts when it comes to certain stocks. Take for instance Nostra Terra Oil & Gas the piss poor microcap that cannot self-sustain without continually raising cash. It has to duck & dive via placings, warrant sales, it’s in debt up to its eyeballs, mired in legal disputes ad infinitum and has piss poor stripper well fields, which are touted as ‘company makers’. (Stripper well fields contain wells deemed economically at the end of their productive life and require constant cash burning workovers to slurp up the remaining dregs of oil left. Such wells produce a few barrels of oil per day, at best, then require shut-in for workovers etc.).
The economics of stripper well production when combined with the cash burn of an AIM listed company to flesh out the ‘Jackanory’ has one purpose and that is to fool the mugs into trading the stock to increase the liquidity so that the company can place and keep the balls in the air. ‘Balls’ being the fat fees those running the show take! Those that assist with the bogus promotion often trade into the rises and some like Turney & Burton and no doubt the others get paid or have been paid by the CONpanys. It’s nothing short of a scam.
The history of Lofgran is one of total failure and scurrilous lies. There is no short squeeze here. No Market Maker desperate for stock to close a short. It is sheer fantasy to enable, nay manipulate, the SP upwards for the yet again Placing that is inevitable. The shorting Shyster has been running around the City gauging the appetite for a Placing. Hence the continual ramptastic horseshit of the Band of not so ‘Merry Men’.
The Gang of four will no doubt deny it, however using NTOG as the example just check how many tweets, blogs, articles and podcasts there’s been on this POS from the ‘Merry’ men that’s been cross pollinated between themselves. Of course it could all be just a coincidence….. Sadly, the form book on other stocks they’ve all been cross-pollinating and ramping kills that Trumpian defence stone dead. As does their ‘Meeting’ in the boozer at the UK Investor Show on the 21st April 2018. Witnessed and 100% correct!
The ringmaster of this ‘circus of lies?’ David Burton of Tell Mugs Shite (TMS). The sad clowns perform for a few shekels…… Oh, what a wicked web we weave when we practice to…… Tell Mugs Shite!
Now not a lot of people knew this, but they do now!
Further update on client recoveries and distribution,
client data notifications (GDPR) and cessation
of ISA manager status
Private & Confidential
To the Firms’ clients
Dear Sir/Madam,
Beaufort Securities Limited (“BSL”) in administration; and
Beaufort Asset Clearing Services Limited (“BACSL”) in special administration
(together the “Firm(s)” and the “administrations”)
We are writing further to our notification of appointment of the joint administrators dated 15 March 2018, in order to provide a more substantive update on the work we have been undertaking, the preliminary conclusions that we have reached and how we currently envisage being able to commence distributions to clients.
Events leading up to the Firms’ cessation of trade
Due to the circumstances surrounding the insolvency of the Firms, the appointment of the joint administrators occurred with very limited notice, which was unavoidable. Consequently, there was no time to make any plans as to how the disruption to clients might be minimised and the return of client assets could be expedited. As clients will be aware, BSL was (alongside certain other parties) charged with securities fraud in the United States of America. The Financial Conduct Authority (“FCA”) had also imposed various regulatory restrictions including a prohibition on all investment activity immediately prior to the Firms’ insolvencies.
Prior to the administrations, the Firms had submitted to the FCA, on a routine basis, various regulatory confirmations regarding the status, quantity and amounts of client money and client assets held by BACSL. We have examined these regulatory confirmations and they have provided an important starting point for the joint administrators to review and assess the sufficiency of the client money and assets held for clients as compared with what is owed to them. They do highlight some relatively modest deficiencies in both client money and client assets. The Firms had, however, sometime previously switched over to a new accounting and record keeping system. These issues, together with the complex nature of the administrations, may create further challenges in the tasks ahead of returning client money and assets to clients.
Steps taken immediately following the joint administrators’ appointment
Immediately upon our appointment, as we have previously advised, we took steps to safeguard the Firms’ data and systems as well as their assets (those held for clients and their own). We have materially reduced the scale of the Firms’ operations and brought in relevant experts to assist us in the conduct of the administrations.
We have also secured funding to ensure that all critical operations can be maintained in order to facilitate the return of client money and assets, in accordance with the proposed courses of action set out below.
Preliminary conclusions
We have carried out a full assessment of the Firms’ records, which enables us to reach the following preliminary conclusions:
in the absence of a surplus of funds within the Firms’ segregated resources and in accordance with governing legislation, relevant costs will need to be deducted from clients’ entitlements to client money and client assets.
client money and client assets were, as at the date of administration, substantially complete save for a very small number of isolated deficiencies.
a large number of the client securities are made up of illiquid or potentially nil value positions which will complicate the basis upon which costs may be levied against them.
in view of the issues identified, we have reluctantly ruled out an expedited return of assets without the statutory protection offered to clients and the joint administrators through a formal bar date and distribution plan.
a distribution plan is being developed (see below) as a matter of urgency and a realistic timeframe to commence returns for the majority of clients will be September 2018 at the earliest.
the FSCS will aim to make compensation payments to a client population who had only small client money balances with BACSL during May 2018.
the basis of allocating costs is also being developed and is likely to be levied by reference to value of the client portfolio and charged on a sliding scale (so that higher value portfolios will contribute more in absolute terms but proportionately less of the overall value of their portfolio of client money and client assets).
with a majority of clients likely to be eligible for Financial Services Compensation Scheme (“FSCS”) compensation with shortfalls and costs falling within the £50,000 compensation limit, we believe the substantial majority of clients will recover their portfolios in full in due course.
we do, however, estimate around 700 clients with client money and client assets together valued in excess of approximately £150,000 may experience a loss on their entitlements in excess of the FSCS’s £50,000 compensation limit.
clients who do not fulfil the FSCS eligibility criteria will not be entitled to receive FSCS compensation and will, regrettably, face a loss on their client money and assets.
Revised estimate of securities value
The indicative figures first published as to the value of the securities in the client assets portfolio have now been subjected to an initial independent valuation. This has highlighted a number of important issues, including as noted above the fact that a number of highly illiquid and potentially nil value positions are held. The carrying value used previously was based on a historic price which we do not believe appropriately reflects a more cautiously assessed valuation. The more conservative value for this assessment is in the region of £500 million.
Corporate actions
We have put in place new interim arrangements to manage the portfolio of custodied assets for corporate actions arising since our appointment, be this receipt of dividends or otherwise. We will provide an update at a later stage on our plans for dealing with clients’ accruing interests.
Clients owing funds to the Firms
A number of clients are indebted to one or both the Firms. Those amounts will need to be collected from the relevant clients as part of the client assets distribution programme referred to below.
Access to the Firms’ Client Portal
Shortly after our appointment, we suspended access to the Firms’ online Client Portal. We are in the process of updating the Firms’ records for the work detailed above and making other necessary changes to it. Once these are complete, we will provide access.
Plans for distribution programme
FSCS summary and overall client outcome
Irrespective of the method of allocating costs among clients, it is clear that clients will face shortfalls as a result of the Firm’s insolvency and ensuing special administration. In accordance with applicable legislation, however, we have worked closely with the FSCS and are able to confirm that, where clients have client money and assets held with BACSL with a shortfall (including reserves for costs) of up to a value of £50,000, the FSCS will seek to provide compensation to eligible clients without it being necessary for a claim to be submitted in most cases. Further information on FSCS eligibility is available here: www.fscs.org.uk/what-we-cover/eligibility-rules/.
Proposed distributions
We are developing on an urgent basis two strands to an overall programme of distributions:
We have worked closely with the FSCS to identify approximately 2,700 BACSL clients who held client money only, each of whose claim is less than £2,000 in value. FSCS will aim to compensate these clients in full during May 2018, without the clients having to submit an application form. No reserves for costs will be deducted in this context. FSCS compensation will compensate these clients in full, and they will have no further claim against the Firm in the special administration. A notification will be sent to qualifying clients separately. This notification will include details of the cash sum to be returned along with limited bank details (if any) and affected clients will have an opportunity to reject the distribution or notify the Firms of any amendments. (Any rejected claims will be deferred for distribution under the distribution plan described below); and
A statutory “distribution plan”, pursuant to the applicable insolvency legislation, designed to facilitate the return to clients of the balance of the client money and securities held by BACSL, running alongside a process of returning client money not covered by the distribution referred to above.
The applicable procedure laid down for the distribution plan by the relevant insolvency legislation entails the joint administrators:
Firstly, setting a bar date for claims in respect of securities: That bar date will be set by means of a notice currently expected to be distributed to all clients during May 2018. We presently anticipate that the bar date will be set for some time in June 2018. Under the applicable legislation, the effect of the bar date is that claimants who submit their claims after the bar date are not guaranteed to have their claims taken into account when distributions are effected, albeit the joint administrators will in any event take into account clients’ entitlements insofar as they are reflected in the Firms’ books and records. When notifying clients of the bar date, we will explain how clients can access a portal on the Firms’ website, designed to show clients what the Firms’ books and records show their entitlements to be, so that clients are in a position to submit any corrections or other information or documentation that they consider the joint administrators ought to take into account, prior to the bar date.
Secondly, preparing and circulating to clients (and the FCA, among others) a document setting out how they propose to go about returning the client securities in BACSL’s possession: This will be a detailed document and it will take some time to prepare. We set out below some of the substantive features that we currently expect it will have.
Thirdly, seeking and obtaining approval of the above document from the creditors’ committee: The joint administrators will be circulating details of an initial meeting of creditors and clients of BACSL. One of the purposes of that meeting is to constitute a committee, made up of creditors and clients of BACSL, which can then represent the wider constituency of creditors and clients during the remaining course of the special administration. It is a requirement of the applicable insolvency legislation that the statutory “distribution plan” be approved by the creditors’ committee, prior to being put into effect. Following the constitution of the creditors’ committee, therefore, there will need to be a meeting of that committee during which the joint administrators’ proposed distribution plan is considered and approved.
Fourthly, seeking and obtaining the approval of the above document from the court: It is a requirement of the applicable insolvency legislation that the statutory “distribution plan” be approved by the court, prior to being put into effect. Following the approval by the creditors’ committee of the draft distribution plan, therefore, the joint administrators will need to make an application to court seeking its approval.
As noted above, the statutory “distribution plan” applies to securities, as opposed to client money. In practice, however, in order to expedite the process of returning clients’ investments (of whatever nature) to them, the joint administrators are planning to deal with client money in parallel with the process for returning client securities. That parallel process will also entail the setting of a bar date and may also involve one or more applications to the court for approval of particular aspects of the process.
These procedures are important for the following reasons: if cash and/or securities were to be distributed to those clients to whom the Firms’ records indicate they are owed, without these procedures first having been implemented, it is possible that competing claims (not reflected in the Firms’ books and records) could subsequently be asserted by clients or other counterparties of the Firms; and that those asserting such claims might contend that the earlier distributions of securities ought to be disturbed, or that client money already distributed ought to be recovered from the clients to whom they were originally paid, for the purposes of meeting the late claims.
In the circumstances, a significant advantage to clients that will be secured by the joint administrators following the procedures set out above is that, once clients receive their cash and/or securities from BACSL in accordance with such procedures, the applicable insolvency legislation expressly provides that such distributions cannot be disturbed by late claimants who later assert that they were entitled to share in the relevant stock lines and/or cash pool (e.g. the clients will receive good title to the securities).
As appears from the above, however, the statutory process is necessarily complex, involving as it does a number of steps, including one or more court applications. There will inevitably be material costs associated with this process and such costs would ordinarily need to be paid for out of client money and assets, though the FSCS may be able to provide compensation in relation to the resulting shortfalls of eligible clients. The complexity, as well as the timeframes specified in the rules themselves, will also mean that there is a certain amount of unavoidable delay associated with the return of cash and securities.
The joint administrators currently anticipate the statutory “distribution plan”, and their parallel plan for distributing client money in accordance with the applicable rules will involve, among other things:
A transfer for clients holding client money (who have not been compensated by FSCS in relation to a small client money balance) and/or client assets up to a certain limit to a nominated regulated broker. We are in the process of identifying a recipient broker and will communicate directly with those clients included within this programme. A client will be able to nominate another new custodian but that may delay the eventual transfer depending on the circumstances at the time. This is a complex exercise to arrange and execute. We anticipate, however, that it may in this way be possible to effect returns to a majority of clients by number and value. We have explored the possibility of effecting such a transfer outside of the statutory process described above (with a view to effecting it more quickly than will be possible within the confines of that process), but we have reluctantly concluded that such is not practicable or, in any event, in the interests of clients, particularly in light of the point made above as regards finality once distributions have been made (i.e. clients receiving good title). As it is, the joint administrators hope that a transfer of this nature may be achievable September 2018 at the earliest.
A plan for effecting distributions of all remaining client securities and money, possibly involving further bar dates and/or the liquidation of unclaimed or other client assets. Given that the clients and/or the assets to which this part of the overall plan will apply will be those giving rise to complexities of one kind or another (failing which they would have been included in one of the other methods of return referred to above), it is likely that this part of the process will be time-consuming and therefore the relevant returns to clients will inevitably take place at a later date than those referred to above.
A methodology for levying costs against client money and assets and as noted above this is likely to be by reference to value and charged on a sliding scale. Costs will need to be assessed on a prudent (high case basis) and allocated against portfolios valued on a conservative basis. The methodology will need to offer alternatives to avoid assets being sold to settle costs (which may need to be carried out as a last resort) and also set out how any rebate for costs will be returned to clients once the final costs have been settled and value of illiquid and potentially nil valued positions finalised.
How the Firms and clients will interact jointly with the FSCS in order to streamline claims for shortfalls arising on their client money and securities interests through costs levies or otherwise.
Regulatory matters
We are working closely with the FCA regarding the distribution of client money and assets. All distributions will be subject to the approval of the FCA.
As part of the above, we will be seeking various “know your client” information and documentation. We shall provide guidance where specific actions on clients’ parts are needed.
Other claims for compensation
We are aware of some 700 claims against BSL by clients for compensation in respect of various matters, including poor investment advice. It is possible that further claims will be made and we will (as appropriate) develop a programme for dealing with these in due course. As regards what (if anything) relevant claimants might recover in respect of such claims, we note the following:
Distributions (if any) to ordinary creditors of the Firms through the insolvencies are likely to be minimal.
Clients of BSL who believe they have a claim for example in relation to negligent advice can submit their claims via the FSCS online portal at www.fscs.org.uk/your-claim/ with any compensation being capped at £50,000 per investor. This is separate from any claim the client may have in relation to a shortfall in client money or assets that were held by BACSL, where there is a separate £50,000 cap per investor and the FSCS will seek to compensate eligible clients without the need for an application to be submitted.
Existing claims against BSL being adjudicated by the Financial Ombudsman Service (“FOS”) are expected to be transferred to the FSCS. We understand the FOS is in the process of writing to all affected clients and will need client consent for this transfer to occur.
Once the FSCS is in receipt of the files, it will contact affected claimants. If a claim is accepted, the FSCS will pay compensation and will take an assignment of the claimant’s rights against BSL and any third party. This will enable the FSCS to seek recoveries, including from BSL’s Professional Indemnity Insurer, and there is no need for clients to seek their own recovery against the Professional Indemnity Insurer. Any recovery of insurance proceeds is likely to be limited.
Individual Savings Account (“ISA”) notification
We set out below formal notification to ISA clients.
In accordance with the ISA Regulations SI 1998 (No.1870) (the “ISA Regulations”), we are obliged to notify you that BACSL has ceased to qualify as an ISA Manager effective from 1st March 2018.
Ordinarily, individual ISA account holders are required to transfer their account to another ISA manager within 30 days of this letter to preserve the ISA status of their assets. However, having regard to BACSL’s special administration, HMRC have agreed to relax such a deadline in order to preserve ISA status. You therefore do not need to take any action at this time.
As soon as any client money and client assets are ready to be returned to you, you should be able to validly transfer your ISAs to another account manager, but only after the joint administrators have quantified all of the assets held by BACSL, and the FCA have authorised the transfer of such assets. Further information will be provided shortly.
On commencement of the new tax year, 6 April 2018, you should be able to open and pay into a new ISA with a different ISA manager subject to your individual circumstances. However, please note nothing in this letter is intended to constitute UK tax or planning advice. It is recommended that you seek independent advice where required.
We will continue to keep clients informed on progress through the website and targeted communications.
Yours faithfully
For and on behalf of the Firms
Russell Downs
Joint Administrator and Joint Special Administrator
Acting as agent of the Firms and without personal liability
Russell Downs, Douglas Nigel Rackham, and Dan Yoram Schwarzmann have been appointed as joint administrators by the High Court to manage the affairs, business and property of Beaufort Securities Limited. Russell Downs, Douglas Nigel Rackham, and Dan Yoram Schwarzmann have also been appointed as joint special administrators by the High Court to manage the affairs, business and property of Beaufort Asset Clearing Services Limited.
The Administrators and Special Administrators act as agents of the companies, without personal liability. All are licensed in the United Kingdom to act as Insolvency Practitioners by the Institute of Chartered Accountants in England and Wales. The Administrators and Special Administrators are bound by the Insolvency Code of Ethics which can be found here.
The Administrators and Special Administrators are Data Controllers of personal data as defined by the Data Protection Act 1998. Personal data will be kept secure and processed only for matters relating to the appointment.
All is not well at Beaufort Securities. One of our members has asked that I run this Open Letter to Tanvier Malik. I’ve read it and strongly agree with the ‘Client A’, that it’ needs to be addressed as a matter of urgency! Mr Malik knows who ‘Client A’ is. I suggest you address the issues raised as a matter of urgency.
Open Letter to Tanvier Malik CEO Beaufort Securities CEO
Tanvier Malik. Questions that need to be answered!
Dear Tanvier
This letter is written to you in an open format given Beaufort Securities’ position at the heart of the Retail investment community in the UK. I believe the issues detailed here are of wider public, and in fact, regulatory interest. I also postulate that if a large retail client with extensive experience of the regulatory framework can be subjected to the quite incredible course of events which I have been with your firm in recent months then it is even more important that a light is cast upon your actions by the appropriate authorities in assessing if there are failings in your procedures.
There are numerous points that I believe need publicising and addressing as detailed below –
The first point relates to KYC (“Know Your Customer”) whereby prior to transacting business for a private customer (professional or retail) that a fact find and suitability assessment is made where a client is deemed “advisory” or “discretionary”. The basis of my account with your firm was “advisory” and I was what is called a “retail” designated client.
During the period I operated my account with your firm (2016/17) I was offered placing positions in a number of companies & on the strength of representations to me by your staff members I participated in a number of these. Important perceived regulatory failing (1) – at no point until early July 2017 had a “fact find” been carried out on me by Beaufort. Indeed, when this fact find was carried out over 12 months after my account had been opened it became apparent that it should have been done right at the inception of the account and that the “advice” given would have been different.
The FCA’s guidebook is specific in this regard re COB 5.2.3 – “When a firm provides limited advice on investments to a private customer, the firm should not treat any resulting transaction as an execution-only one.”
Further, COB 5.2.4 states – “Principle 9 (Customers: relationships of trust) requires a firm to take reasonable care to ensure the suitability of its advice and discretionary decisions. To comply with this, a firm should obtain sufficient information about its private customer to enable it to meet its responsibility to give suitable advice”
I wonder how many other clients have not had the KYC requirements applied to them and by extension are in investments that may not be suitable for them?
The second point relates to the FCA’s definition of “Best Execution” – the guidelines are extensive here and I will stop short of quoting the rule book at you but my own understanding having worked as a dealer and being a CF30 is that “timely” execution is a key component of this. Numerous transactions were executed way beyond the usual couple of minutes that one would expect. In one instance I believe approaching 30 mins. I make the point that at the time of instruction and final execution that there were no “fast markets” or other similar issues in play that could be used as an excuse for such a delay. In a few moments a price can move materially, let alone a near 30 mins timescale. In this regard I believe that timely execution was not applied to my account and I wonder how many other Beaufort account holders are suffering same and being potentially detrimented.
Thirdly, there is a very serious issue that goes to the heart of both best execution again and, also the legal concept of “willing buyer, willing seller”.
I attempted to carry out a simple “broker to broker cross”. In effect the buyer was looking to confirm the trade through their underlying broker with you and the bargain be agreed with one side then reporting the bargain to the exchange. The order was given on an execution only basis by me. I have fact checked this with numerous market counterparts and 2 regulatory specialists and there was nothing out of the ordinary with regards to this structure. Indeed, broker to broker crosses effected both at prices that relate to current market spreads and that are different to market spreads transact many, many times a day.
Your firm was insistent that this trade be actually put through a market maker and so it was no longer a standard broker to broker cross despite both my and the counterparts insistence and protestations that we did not want it going through the market. In effect, your firm and the market maker attempted to frustrate an open market, arms length bargain between 2 wiling parties and dictate a new price – one that would have cost me personally £50,000. In illustrating just how wrong Beaufort Securities were in this regard, when I finally transferred my account elsewhere (despite obstacles being continuously put in my way in trying to effect this move I also add), the transaction was concluded immediately at the agreed prices between myself and the counterpart. This issue forms the main body of my FCA submission as if your approach was correct then by extension hundreds of other trades carried out daily are remiss in regulation or, in the alternate, your firm was wrong in this approach and it needs to stop before other clients are potentially (or have been) financially detrimented.
To conclude, I have made my own direct representation to the relevant dept at the FCA re the primary points detailed here and I urge you now, as a fellow market participant, to take a root and branch approach to your current systems and controls structure and, perhaps more importantly, your corporate culture. There is a saying that “the tone of any organisation comes from the top” and I ask you to reflect upon that. The stress I have been subjected to in dealing with these issues with your company this last few weeks has been phenomenal and I would not like any other investor to have to endure what I have, hence my bringing this to a wider market attention.
Just when Nostra Terra share holders think that it can’t get any worse it does. Today I expose what must be one of the most disgraceful and deceitful episodes in the history of the Alternative Investment Market and the codes of practice that CEO’s should adhere to and what the AIM regulators are there to enforce.
It is quite frankly an absolute fucking disgrace. It ranks as yet another low point in the history of the Nostra Terra shorting CEO and bare-faced liar Matt Lofgran. I take no pleasure whatsoever in exposing these ‘practices’ and do so solely as a warning to all those currently holding or looking to buy stock in this POS. If you are a Nostra Terra Share holder then you need to contact the company and the Nomad and the AIM regulation team and seek answers.
Documentation forwarded to this site has now been proven to be genuine.
Secret Cash Payments.
The CEO of Nostra Terra Oil and gas has been making ‘Secret Cash Payments’ of possibly tens of thousands of pounds to a well known internet scumbag to attack his own share-holders who had formed a share-holder action group, and to ramp his company via social media. This is wholesale market abuse and the AIM regulator now needs to step in and clarify exactly what has gone on here. The scumbag in question is Matthew Benjamin Turney, aka Ben Turney.
Emails seen by this site provide compelling evidence that thousands of pounds maybe tens of thousands of pounds have been filtered out of Nostra Terra to Turney. Those emails are emails from Matt Lofgran condemned by his own words. Copy’s are below for all to read.
Lofgran was suckered into making those admissions via a fake Ben Turney email address. The emails were forwarded to me. It has taken a long time to prove their authenticity. Which is 100% now proven.
Drug Dealer Took Cash to Ramp & Attack NTOG Shareholders
Lofgran admits that he has told no one but may have told the nomad. That Nomad has since parted ways, as the time of the Faustian Pact’ was way back in 2015. Lofgran also goes on to state that there’s no paperwork on the secret payments to Turney. “I don’t think we even have a consultancy agreement in place” four minutes later he confesses “By the way, never told anyone any amount”.
Questions now need to be answered and answered openly. The inference from those admissions is that the Board of Directors have been kept in the dark regarding secret cash payments to a well known failed businessman, self styled Private Investigator and former legal highs (Illegal Now) drug dealer, a man who chuckles at selling poisonous chemicals to teenagers, chemicals deemed unfit for human consumption and now punishable by up to 10 years imprisonment. When was this pact entered into? How much has been paid? How was it paid? Did Lofgran pay it personally? Did Lofgran use share holder money? Are there any ‘other such ‘pacts’ with other people? Why was there no paperwork? Why was the BOD kept ignorant? Are payments still being made? These are but a small selection of valid questions that must be answered. Make no mistake these are breaches of FCA guidelines and regulations. Lofgran needs to answer!You can read them HERE
Turney has openly attacked the share holder action group on bulletin Boards, his twitter feed is a litany of NTOG ramptasic horse shite. Paid promotion on behalf of the company. He has consistently promoted NTOG yet he has failed to declare that he has been receiving thousands of pounds of cash from the company. That itself is an abuse. Let alone Lofgran’s corporate failure to adhere to FCA guidance/regulations. Has Turney used Teathers Financial as a conduit for these secret payments? Has the money gone into Teathers or has it gone into his pocket? Again there is a myriad of questions that Turney needs to answer.
Silence
Both individuals have been contacted by myself many times, both have remained ‘silent’ this is the silence of people with something to hide.
Part of those requests also asked about Mr Michael Whitlow, aka Doc Holiday, if he had any financial involvement with Nostra. Mr Whitlow is mentioned by Lofgran in the emails, however much I dislike Whitlow,I do not believe a word this man says, after having personally met him several weeks ago he assured me that he had received no money directly or indirectly from NTOG. Evidentially there is no concrete proof linking him to this ‘Devils Pact’. So Michael gets the benefit of the doubt until such time as there is or isn’t proof.
I also spoke to many sources one of which confirmed to me that they knew Turney was taking ‘backhanders’ or payments from Lofgran/Nostra.
If I was a Nostra shareholder I’d be demanding answers. This is an absolute scandal and it needs to be addressed immediately with a full explanation to the market, the Nomad, shareholders and the NTOG BOD.
Lofgran has to resign. Nothing else is acceptable. It’s over to the drug dealer and the shorting CEO for their response.
Viva
Daniel
Damning emails. Slam Dunk! Below!
@*****.***> wrote:
>
> Matt
>
> Have you discussed the consultancy agreement and the fees with anyone outside of the Company recently?
>
> I’ve received 3 emails. One’s fairly accurate. Doc and I are concerned.
>
> Ben
On Mon, May 8, 2017 at 7:11 AM, Matt Lofgran <[email protected]> wrote:
No.
I think the only ones I ever told were the Nomad. Not sure if I ever told the broker.
By the way, I don’t think we even have a consultancy agreement in place.
On Mon, May 8, 2017 at 7:15 AM, Matt Lofgran <[email protected]> wrote:
It would appear that the dirty tricks now being deployed by Nostra Terra Oil & Gas (LON: NTOG) to wriggle off the shorting hook has sucked in Tom Winnifrith. News has reached me that shareProphets has backed Matt Lofgran the embattled CEO, who has been caught with his ‘shorts’ down and as TW says if true has to RESIGN. Would this be the shareProphets that’s taken tens of thousands of pounds in ‘fees’ from the said company for presentations, donations? You take the Company shilling you sing the company tune.
Once again poor Tom has been spoon fed utter shite from Nostra and here’s why.
YA Global Master SPV, Ltd
NOSTRA TERRA OIL & GAS CO
GB00B067H256
0.00
2012-11-13
YA Global Master SPV, Ltd
NOSTRA TERRA OIL & GAS CO
GB00B067H256
1.09
2012-11-12
YA Global Master SPV, Ltd
NOSTRA TERRA OIL & GAS CO
GB00B067H256
0.88
2012-11-08
YA Global Master SPV, Ltd
NOSTRA TERRA OIL & GAS CO
GB00B067H256
0.77
2012-11-07
The above are HISTORICAL SHORT positions DISCLOSED on the FCA website as of today, yesterday and when they were declared in 2012. You’ll notice that each short position has increased. Those short positions were held at the same time as Yorkville/YA Global, one in the same company, held 150,000,000 million shares loaned to them by the Nostra CEO, Matthew Lofgran. Yorkville are notorious known Death Spiral shorters.
It’s quite simple to resolve. Nostra Terra should release an official RNS after contacting the FCA telling the FCA why those SHORT positions disclosed by the FCA are wrong, stating that at no time whatsoever did Yorkville/YA Global hold ANY short positions in their company. Then explain to the market and the FCA just what in God’s name the Yorkville/YA Global short positions DECLARED on the official FCA website are? They’ve been there for 3 years. Extremely difficult to find but there none the less. Are we to believe that Nostra never knew of their existence? Is it all a Bobby Ewing shower moment? Are we to believe that Lofgran loaned 150,000,000 million of his shares to known market shorters just because he liked them? Pray tell us Mr Winnifrith? Or is it a case of ‘Occam’s razor’ which is thus. The most logical and simplest explanation is the truth?
Or maybe a drunken official at the FCA or Yorkville after having a slice of Tom’s delicious pizza, lost the plot, not once or twice or three times but four times over a period of six days made fraudulent SHORT DISCLOSURES miss-leading the market in 2012…
It’s a shocking tale of undeclared, unsecured loans made by Dave Whitby from the coffers of the then CEB AIM listed company, which recently rebranded to Andalas Energy & Power (LON: ADL). Whitby, who is the CEO of Corsair Petroleum, a private Singaporean company, took control of CEB/ADL on June 5th 2015, on that day he also took control of £1,500,000 of placing cash raised at 0.4p. Within days he had secretly signed off $475,000 in undeclared related party payments in unsecured loans. If you think that is shocking, read on and discover who the unsecured loans went to.
I call upon AIM Regulation to immediately investigate Andalas Energy & Power PLC and it’s disgraceful CEO, the $600,000,000 fantasyman Dave Whitby for accounting FRAUDS he should be suspended forthwith! Their Nomad, Cantor Fitzgerald, Miss Sarah Wharry, (Worry) has been informed, as have the AIM Regulation Team and the FCA Market Abuse bods.
This is how it went.
On 10 June 2015 Whitby CEB/ADL issued Whitby/Corsair (Yes himself & his Corsair mates) with an unsecured loan of $250,000. The loan was to bear interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest was to be made by 10 June 2016.
On 15 July 2015 Whitby CEB/ADL issued to Whitby/Corsair another unsecured loan of $225,000. That loan also carried interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest was to be made by 15 July 2016.
Those payments are related party transactions and were never disclosed to shareholders or the market at the time they were made. Just how much of the $475,000 Whitby and Simon Gorringe, who is also on the board of Corsair and the gravy train at Andalas, have taken in payments from Whitby/Corsair is not known. However any payments made by Whitby/Corsair using Whitby CEB/ADL unsecured loan cash must be yet more related party transactions and subject to full RNS disclosure. Nothing, zippo…
The reason Whitby/CEB/ADL gave Whitby/Corsair unsecured loans is quite simple. Corsair haven’t got a pot to piss in and haven’t got any asset/s of value to secure the loans. It is inconceivable that any financial institution or business would advance approx. $500,000 in unsecured loans at 5%.
The questions are many and myriad but will have to wait until later down in this article because folks it gets even worse!
On the 19 August 2015. Whitby/CEB/ADL incorporated a subsidiary of Andalas Energy & Power, another Singaporean company called Corvette Energy (Singapore) PTE. LTD Company registration number 201532252D. Now you would think that an AIM listed company operating on the London Stock Exchange would have RNS’d such. But nay, there’s no mention of the new Whitby/CEB/ADL/Corvette subsidiary. The first inkling of Corvettes existence is six months later, buried in their half yearly report released on 26/01/2016.
Here’s the killer, we learn that Whitby CEB/ADL and Whitby Corsair have now novated and ‘extinguished’ the Whitby CEB/ADL unsecured loans of $500,000 & the 5% interest made to Whitby Corsair. “On 26 January 2016, Andalas, Corsair and Corvette entered into a novation agreement pursuant to which the Loans were extinguished and the benefit of the loaned moneys was transferred to Corvette with effect from 30 October 2015”. So now the unsecured, undeclared loans have come full circle back to Whitby CEB/ADL/Corvette. The burning question shareholders should be asking is this; How much was returned?
Remember, that according to the 2015 annual report the unsecured loans were made with these contractual conditions “The loans bear interest of 5% per annum payable on repayment of the loan/s. Full repayment of the principal amount/s plus accrued interest of 5% will be made by 10 June 2016 and 15 July 2016. There was no mention whatsoever of the unsecured loans being made for Indonesian Due Diligence. It is only when their repayment looms large is it sneaked out that ‘really guys this was for DD’. That throws up a multipule choice of unanswered questions. How were Whitby Corsair ever going to repay? Maybe they were planning to flood the market with the next tranches of ADL shares, all 93,750,000 going to Whitby Corsair that were to be awarded to them on the signing of an Indo’ deal? Did this plan fall apart during suspension? It’s 8 months after the unsecured loans were made that the repayment goalposts are moved. It is s fraud, compounded by lies!
Canada Dry! Charlatan Exposed!
We learn on the 26 January 2016 that they now were given so that Whitby/Corsair could progress Indonesian due diligence. What a crock of shit. Let’s be generous and say Maybe some of the cash was used but I seriously doubt that all of it was! Are we to believe that Whitby CEB/ADL will force their own ANDALAS subsidiary Corvette, to repay back $550,000 to themselves? When did it change? It’s a sleight of hand.No fooker is paying the cash back because the majority of it has been rinsed out by Whitby/Corsair! What is left is probably a small rump of cash that they once again haven’t RNS’d. These are ALL material transactions that have to all intents and purposes been sneaked out via the back door. They have been deliberately withheld. They are in effect ‘Back door Director loans’ that will never be repaid. Whitby should resign immediately.
The elephant in the room is this? Where has $550,000 dollars gone? Of course we’ll get the usual spin from Whitby, does anyone now really doubt that what myself and Tom Winnifrith, have wrote on this chump isn’t, in light of yesterdays absolute disastrous placing and this article today, bang on? Whitby is a corporate crook, raping his own shareholders to line the pockets of himself and his fellow Aussie crims.
I contacted Sarah Wharry the company nomad, from Cantor Fitzgerald, Sarah hasn’t responded to my questions. I wonder why? It has to be noted that Cantor were not the Nomad at the time of the undeclared, unsecured related party loans. That mantel fell to Sanlam Securities who, intriguingly, no longer provide Nomad services! I personally spoke to several big private holders of ADL stock who were again, unaware. I spoke to two CEO’s. One stated that he “would never put that to my board because it was wrong”. The other said in answer to my question, are these in your opinion related party transactions? Reply; “Absolutely – is a related party transaction and needs independent written advice and an RNS”. Both of these men are respected CEO’s.
I urge shareholders to contact the relevant authorities with the questions below. Make a formal complaint. A full investigation is warranted. Get the $550,000 dollars back. A full forensic account is needed here!
Questions for AIM Regulation, Cantor Fitzgerald and the FCA Market Abuse Team.
1/ Can you please explain why $475,000 in related party payments i.e Unsecured loans, made by the CEO Whitby CEB/ADL to CEO Whitby/Corsair were not disclosed to shareholders and the market at the time they were signed off? (There was never any RNS’s)
2/ Can you please investigate how much of the unsecured loans made by Whitby/CEB/ADL to Whitby/Corsair were paid in fees/expenses to Whitby/Gorringe by Whitby/Corsair?
3/ I understand that these unsecured loans have now, as of January 2016, been novated and moved into a hastily incorporated subsidiary of ADL. (Corvette) why wasn’t this disclosed?
4/ How much money was transferred by Whitby/Corsair to the Whitby ADL subsidiary Corvette?
5/ How much cash did Whitby/Corsair burn through before the residual amount of the unsecured loan was transferred back to the Andalas subsidiary Corvette?
6/ What has happened to these loans now, will they ever be paid back in full as per Whitby stated in the 2015 annual accounts?
7/ The Company has lied to shareholders and the market, isn’t this sanctionable?
8/ Why was there no RNS on the formation of the ADL subsidiary, Corvette? Surly this is an RNSable event?
9/ Why was there no RNS on the transfer of the loans back from Whitby/Corsair to the Whitby Andalas subsidiary, Corvette?
10/ Why wasn’t the novation and extinguishing of the loans plus interest, disclosed to the market and shareholders?
11/ How much of the unsecured loan cash went into the pockets of Whitby/Gorringe/Corsair?
12/ Why was no information ever given to the market that unsecured loans with 5% interest, were part of a due diligence effort?
And last but not least,
13/ Who signed these unsecured loans off and where was the oversight with the written legal advice as to their legality?
It is only in January 2016 some 8 months later, that we are told that; Andalas and Corsair agreed to structure the funding of the due diligence expenditures as loans (“Loans”) to Corsair” This just isn’t credible let alone believable.
It seems to me that this is, to all intents and purposes a fleecing of CEB/ADL cash by the executive and should be immediately investigated.
I put it to shareholders that these unsecured undeclared loans were in effect ‘back door director loans’ which have now been rinsed through two corporate entities coming back to ADL’s Corvette subsidiary minus a large amount of cash originally given to Whitby/Corsair by Whitby CEB/ADL.
Basically chaps where has all the money gone?
Viva
Dan
NB. This is what they said in their annual accounts: Published 21 July 2015;
On 5 June 2015 David Whitby was appointed as Managing Director and Chief Executive Officer of the Company. David Whitby is a beneficial owner of Corsair. Through his beneficial ownership of Corsair David Whitby owns 7,812,500 shares in the Company which were issued on 4 June 2015. On 10 June 2015 the Company entered into a loan agreement with Corsair to provide Corsair with an unsecured loan of USD 250,000. The loan bears interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest will be made by 10 June 2016.
On 11 June 2015 370,000,000 ordinary shares were issued for trading at a price of 0.4 pence per share, raising gross proceeds of GBP 1,500,000. Of these 50,000,000 were subscribed to by Northcote.
On 15 July 2015 the Company entered into a loan agreement with Corsair to provide Corsair with an unsecured loan of USD 225,000. The loan bears interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest will be made by 15 July 2016.
This is what they said in their 2016 half yearly report: Published 26 Jan 2016;
On 5 June 2015, Andalas and Corsair entered into an agreement (“Assignment”) pursuant to which Andalas agreed, amongst other things, to undertake and fund due diligence in respect of certain oil and gas concessions in Indonesia with a view to making an investment. Initially, for administrative convenience, Andalas and Corsair agreed to structure the funding of the due diligence expenditures as loans (“Loans”) to Corsair and, accordingly, advances pursuant to that arrangement were made on 8 May (US$25,000), 10 June (US$250,000) and 15 July 2015 (US$225,000). On 19 August 2015, Andalas incorporated a subsidiary, Corvette Energy (Singapore) Pte Ltd (“Corvette”). On 26 January 2016, Andalas, Corsair and Corvette entered into a novation agreement pursuant to which the Loans were extinguished and the benefit of the loaned moneys was transferred to Corvette with effect from 30 October 2015.
Corvette was incorporated on 19 August 2015. There was never any mention in the 2015 accounts of Corvette etc Or what these unsecured loans were made for?!?
Corvette only comes into the picture when the repayment of the loans with interest begins to loom large.
 It’s time to get the popcorn in. Tom Winnifrith’s ShareProphets are going for the ‘Zoetic jugular’. Claims of Corporate malfeasance are now doing the rounds at The FCA, City of London, as well as Stateside, The Food & Drug Administration who, make no mistake, are both investigating the ‘ShareProphets Zoetic Dossier‘, which I might add looks DAMNING….

 A quick check of Braileys’ twitter reveals he’s following and followed by virtually every known PUMP & DUMPER. In 1 tweet Brailey accuses Malcolm Graham Wood of being ‘Compromised’. Well how compromised are ShareProphets now?
 ‘other’ covert operations not only attacking companies as well as trolling (mostly) small time UK punters trying to make an honest gain?
 Viva!
 Well let me tell you. On the 21st April 2018 the day of the UK Investor Show, four of the above met in a public house (Mr Burton, Mr McKinley, Mr Whitlow & Mr Turney) where they agreed, among other things, to form a ‘mutual self-help society‘ i.e. they made a pact and conspired to ‘Promote’ each other’s tweets and blogs/articles/podcasts. Sources who witnessed it also tell me that they believed they could become a force greater than ShareProphets. The deluded ‘Wannabees‘ thought they were going to take over the world of micro-‘crap’ info……

 The history of Lofgran is one of total failure and scurrilous lies. There is no short squeeze here. No Market Maker desperate for stock to close a short. It is sheer fantasy to enable, nay manipulate, the SP upwards for the yet again Placing that is inevitable. The shorting Shyster has been running around the City gauging the appetite for a Placing. Hence the continual ramptastic horseshit of the Band of not so ‘Merry Men’.