google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: gas

  • #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    There’s a ‘hefty‘ lot of  Reabold Resources (LON: RBD) investors/traders out there, awaiting news on the company’s up-coming drills. Wick & Colter. If you don’t know what those drills are then I suggest you get researching because unlike certain other UK Onshore Oilers the RBD drills (Offshore UK) are the real deal. A ‘Roll of the dice’ with a decent chance of success (COS) on BOTH drills, particularly Colter. Which, once they actually get to rig ‘mobilisation stage’ will push this SP much higher. I personally hold some stock here, so am always on the hunt for information. The problem is the company are not releasing the news. Good or bad I publish what it is. You can moan all you want but it’s better to know what’s going on than not. It’s how you make money and it’s how not to lose money. It was pencilled in for a 12 noon release but I’ve been cashiered into 12:30pm ’cause one of the ‘twittermen‘ has to finish his go-karting with the family. What a nice guy I am….  🙂

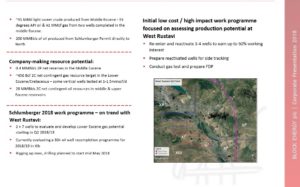
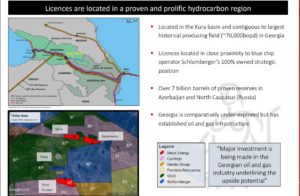
    Now it’s been a long time since I wrote on Reabold and new information has come my way via the BMD ‘sauces‘ pipeline. There’s a major whisper that this company are farming into a Georgian gas asset which is ‘controlled’ by, the soon to IPO, Block Energy. Fortunately I’ve managed to get my hand on not one, but three Block Energy prospectus’. The Georgian gas asset is flagged up as “Substantial potential from 608 Bcf 2C gross unrisked contingent gas resources at West Rustavi, analogous play being tested by Schlumberger in 2018 and 2019 on adjacent licence”

    This is more good news if it comes to pass, as it further flesh’s out RBD with another potential quality licence farm-in. A value driver.

    In the constant hunt for good returns, Reabold, sub 1p, could provide excellent returns. The SP could hit 2p/3p/4p/5p dependent on how successful they are. It will almost certainly break through 1p soon enough.


    Fully funded with a big following and an even bigger following waiting on the side-lines to jump in once the drills start to crystallise as a reality. The placing has been done so unless they’re running a ‘double bluff‘ holders should be able to sit tight and wait for the move upwards. Of course the placing flippers are still at work exiting, however most of them will now be out. Good place to start researching is HERE

    This is going over 1p soon enough. The only question is when? Not if! But as ever do your own research etc. Remember I hold stock as such I could be construed as a Rose Tinted Spectacle wearing leftie… 🙂


    Viva


    Dan


  • Ascent Resources. ‘Mother Hubbard’ There’s Fook All Left In The Cupboard..

    Ascent Resources. ‘Mother Hubbard’ There’s Fook All Left In The Cupboard..

    “Mother Hubbard there’s nothing in the cupboard” So goes the sad sorry tale of Ascent Resources (LON: AST). Today’s 7am RNS announced accounts for the year end December 31 2017. The problem was that the accounts were not released within the RNS and directed investors to their website which funnily enough never had the accounts on. READ ACCOUNTS HERE 

    Now call me a cynic! ‘You cynic Levi!’. But surely if an RNS states that the accounts are on the company website then that is where they should be. But no. Several calls to the AST Nomad, Aim reg team with a follow up email seems to have done the trick. Accounts in all their gory details now on the website 3+ hours late and no wonder why….

    I Want Your Cash! Again & Again ad infinitum to pay my fees for failure…

    The accounts lag behind real-time by some 5 months. It’s glaringly apparent that Ascent Resources are close to the bone and running on fumes. The cash burn is what’s important here. £1,032,000 in Directors/Employees remuneration, £1,966,000 loss for the year with a measly £699k left in cash as of 5 months ago which doesn’t reflect their £210,000 of liabilities 5 months ago.

    Serial Failure…. Gave himself massive pay rise.

    So let’s be generous ’cause I’m a real generous type… Directors/Employees Remuneration is running at circa £1,000,000 per year. Five+ months have since elapsed so circa £500,000 as per their D/E Remuneration cash burn has now been paid but’ lets only take off £400,000 from their cash position that leaves them £299,000. Hang on I here you AST trolls scream ‘we’ve got revenue now!!!’ ‘Ok’ say I, I’ll add that in… The Ascent gross margin was £411,000 that is to say the actual cash received and held by AST. So you have £411,000 per year but your running at a £2,000,000+ loss! Ergo there’s a £1,600,000 funding gap that has to be bridged to survive this year!!!

    Old Mother Hubbard LOL!!!!!

    Where is that money coming from because it’s not coming from the production is it? Production is declining because there isn’t the cash to spend on it. What an absolute fooking mess the corporate shysters carve ’em up Carver & Hutchinson have made. They’ve cleaned the company coffers out and annually trouser hundreds of thousands of pounds while awarding themselves huge pay increases for failure. You can be sure of one thing whatever happens to AST these corporate shysters will continue to bleed it dry until they are booted out of the company.

    Ascent Resources are running on fumes and regardless of what these two fookers are spinning to you, the mug punters, if they don’t raise cash and raise it quickly then they will be insolvent. Massive Discounted Placing on the way as sure as night follows day! And guess who will be getting the discounted stock? Come on down Mr Henderson and Mrs Darwin. with their bastard child Primary Bid in the bolloxs!!!


    Sell and run like hell….


    Viva


    Dan

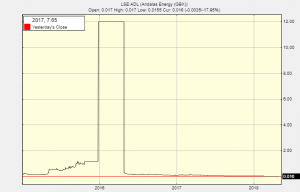
  • Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

    Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

    Today yet again we have ‘yet again’ another scandalous placing & acquisition RNS and a Board change RNS from the corporate crooks who run Andalas Energy & Power (LON: ADL). Make no mistake these fookers are running true to form. The RNS’s contain blatant lies. Which I will expose further down in this ‘Epistle to the Morons’.

    Mug Retail Punters woke up this morning to yet more horse-shit via the bush-tucker system. I say ‘Bush-Tucker‘ for good reason as my sources, who are 100%, have kept me informed on #ADL at every twist & turn. More of why I’m using an Aussie term further down in the blog…

    What is happening at Andalas Energy? Well I’ll expose it and expose it in full! Today’s Placing/Acquisition wasn’t news to me as I already knew months ago about the new asset and knew on Thursday/Friday that the joint cunts, Novum & Optiva were lining up a placing. Sadly I only had 2 sources. (The BMD rule on solid info is that I have to get at least 3 separate sources unconnected with each other before I run an article.)

    RNS LIES

    Investors who are currently holding ADL stock are in for a wipe-out via a massive share consolidation and another placing. Todays RNS’s contain blatant lies. Gorringe has stated; “Indonesia offers significant potential and we remain committed to our existing projects and strategy there”.  This is a blatant lie.

    As is this; “On behalf of the board, I would like to extend our thanks to David (Whitby) for his service to the Company, he brought passion for Indonesia to Andalas and we wish him well in his future endeavours.” 

    New Name. New Asset. New BOD. Consolidation & Wipe-Out. Rinse Repeat!

    David Whitby, outgoing Chairman, said “I am proud of what the team has achieved in Indonesia, whilst the Company has not done enough to show the market that the foundations built over the past few years will generate shareholder value, I am confident that I leave the Company full of opportunity. I wish the team and shareholders all the best as Andalas executes its new focused strategy, which has the potential to make 2018 a significant and exciting year for all involved.”

    For a company to opine such blatant shite in an RNS is testament to how detached from reality they have become from their share-holders. There is no shareholder out there who, hand on heart, would agree with the utter shite above! Whitby and Gorringe have decimated ADL and raped it since day one with a series of worthless paper deals. Not one therm of gas or drop of oil has been produced, yet tens of millions of pounds have been fleeced out of UK investors. They’re now being paid off to fuck off. For Whitby or indeed any of the sad sack of shit that run this company, to state such utter bolloxs gives away exactly how they see shareholders. Gullible fools bent over & willing to be repeatedly financially sodomised, with the help of the likes of BigGob, Bellcunti & the Gunslinger a.k.a Doc Holiday etc. You’ll all remember them with their incessant ‘Share of The Year’ shysterism…

    SHADOW DIRECTING

    Those who are basically shadow directing ADL have no intention whatsoever of progressing Indonesian assets because they know they’re paper assets and worthless. The plan which is being shadow directed by Paul Hayward (Block Energy) Novum brokers Colin Rowbury, James Sheehan & Optivas Christian Dennis, (you may recall some of those names as these were the people who installed the crooked Whitby crew (and kept it going) at the beginning of this long, sad, tortuous tale and what a tale it has turned into) is to reinvent ADL and slowly flip out the majority of the board quietly over a period of months, bring in new blood, while at the same time changing the company’s name, employing professional PR/IR and changing the emphasis/direction of the company. Hence the new asset…. It is a reinvention of the wheel, a passing on of the ‘cash cow’ that allows those at the pigs trough to keep feeding and filling their pockets.

    And pray tell just where in the name of God are ADL going to get their 14.75% share of an offshore drill in the North-Sea for the Licence P2112 ? The cost of which is up to circa £50,000,000 sterling…. It cannot be done unless they jettison the entire Board of ADL and run away from Indonesia and wipe out existing shareholders via a massive Consolidation and placing and that folks is exactly what those shadow directing this POS are about to do!

    As for the rest of  Licence P2112 who is going to come in? My sources are telling me that, that other super sodomiser of UK Retail Mug Punters, Solo Oil & Gas (LON: SOLO) are also in discussions with Eagle Gas LTD. And we all know who really has their fat sticky ‘didgeridoos’ in SOLO. Come on down the fat Aussie Liar and corporate conman His Excellency ‘LordLieAlot’ take a bow David Lenigas!


    Wipe-Out on the way ADL!


    Have a Good Day Cobbers!


    Viva!


    Dan

  • Saffron Energy/Coro Energy. It’s a Bit Convoluted. But it’s a ‘Goodun!’

    Saffron Energy/Coro Energy. It’s a Bit Convoluted. But it’s a ‘Goodun!’

    There’s never a dull moment on the London Alternative Investment Market (AIM) particularly when one is trying to work out whether we’re being sold a ’pup’. You’ve got to go through all the available documents line by line, then re-read each and every document line by line. As well as using all available sources to see what you can come up with, such as what the company are involved with below the radar and how this could affect value going forward. (More on this below)

    Such is the convoluted nature of the Saffron Energy Reverse Takeover. Black-tie events apart & the machinations of Po Valley assets in,  out, suspension, relist, suspension, relist, AGM dates constantly re-jigged etc. The information saturation on this one would take its toll on the patience of a saint.

    But now all finally seems to be coming to fruition. The well-known corporate bastard, (CB) James Parsons (JP) and his team of lessor corporate bastards are now ready to and no doubt raring to go. Being classed as a ’Corporate bastard’ may ‘sound’ (No pun intended) harsh. Far from it. Again, unless you’re steeped in corporate culture you’d not realise that this is a worthy accolade, of sorts….. A corporate bastard gets the job done for his/her shareholders and the benefit of the company. Warren buffet is a corporate bastard. The head of BP is a corporate bastard. They are bringers of value. They do what is necessary regardless of short term pain for long term gain. When choosing an investment or a short-term trade always bet on the CB. Proven management bring value. Proven shysters lose value.

    All too often we as investors/traders are sold down the river by corporate shyster lifestyle companies operating on the AIM, it’s littered with them, in fact it’s like a backed-up lavatory at a Japanese POW camp, literally over-flowing. I’ve watched and followed the bowel movements of these companies and have written and exposed many of the dirty tricks that they try to pass off as good business when it’s anything other than good. So, it makes a change when a real opportunity comes along. Such as Sound Energy that hit over £1 & the great Echo bonanza that rallied to over 25p in the first few months of development.
    At the moment we all await the Saffron AGM which is nothing but a rubber stamp of the proposed terms of the RTO. Trying to cut through the corporate speak and get to the nitty-gritty of what comes out of the other end has in my opinion not been very well communicated to share-holders and those looking to trade/invest post the AGM ratification of the RTO.

    So, I’ll break it down into common parlance. Layman’s terms. I’ll also give the readers of my most wonderful blog site the heads up on what is currently going on in Indonesia. Humpty Dumpty

    Pre-the AGM there’s 200,000,000 million Saffron shares in issue. Post AGM, on the 29th March 2018, there will be a new company formed: Coro Energy (LON: CORO) with team JP at the helm.

    Shares in issue will be 716,809,735. Warrants & Options outstanding will amount to 236,817,341. The warrants will have a strike price of 6.57p, the placing shares have been sold at 4.38p per share. There will be circa $15M in cash, virtually debt free with bread & butter production. The Company’s cornerstone investor, CIP, together with Continental Investment Partners S.A.,Metano Capital S.A. and Greenberry S.A, Marco Fumagalli and James Parsons have been classed as a ‘Concert Party’ they will hold, post AGM, 22.82%. Po Valley will, unless they’ve been selling pre AGM , hold 100,000,000 (13.95%). There will also be an open offer of 45,662,100 shares to existing shareholders. There will be a plethora of ‘Lock ins’ on stock held, most will stick to the lock in. But me being me I don’t set much store by them. One lot who will be slowly drip feeding into the rises will be Po Valley. Regardless of what they say….

    Following the AGM ratification, in aggregate, the Company will own 2P (proved and probable) gas reserves of 205.10 MMscm, 2C (contingent) gas resources of 660.20 MMscm, and 2C oil resources of  2.40 MMbbls. The best way to understand the structure of the newly formed entity is the pictograph (Right).

    The asset base post AGM will be cash generative which will increase as Coro invest and rework over existing and new fields in Italy.

    Now the main direction of Coro will begin to focus on South east Asia, Indonesia and Malaysia.

    I was down as a placee until the suspension and pulled out due to the ever-changing time line of readmission and terms. Now PVO are out, which is a much better value driver for Coro. Too many CEOs aren’t good for stability. Just as too many cooks spoil the broth, too many CEOs fuck the company up. Now they’re out. That’s good news all round.

    It’s known by ‘Yours Truly’ that Coro are in advanced negotiations with several Indonesian oil & gas companies and are in talks with the Indonesian state-owned oil company PERTAMINA.  One of their new directors, Ilham Habibi, (Son of a former President of Indonesia) has direct access to the top echelons of PERTAMINA. I know this because I met Mr Habibi in Indonesia last year. (I was on Sefton business) Several of the assets I toured were up for grabs including a 10 Million scuffs a day gas producer with half a TCF resource. And a 3,000 bopd asset owned by Fosters oil. So, you can take it as read that there’s going to be multi TCF Indonesian exploration/production assets brought into Coro some time in 2018.

    Any news on big exploration gas/oil licences or producing oil/gas assets will set the share-price on fire. It’s a no-brainer that the SP will rise. The question isn’t ‘if’ it’s when. Any thing under 5p is a steal. Any one selling now will rue the day…  I’ve set a target between 12p-15p over the next 12 months. And as ever will closely follow the news and the developing story. Investors should do likewise, keep researching them. It will pay off.

    I have to ‘fess up’ that I’ve been holding/buying shares in Saffron for quite some time!   🙂

    Get ready for ‘Go’ on Coro!

    Viva!

    Dan
  • Reabold Resources. Placing Ahoy!

    Reabold Resources. Placing Ahoy!

    It’s not looking good for holders of Reabold Resources (LON: RBD). News has reached ‘Yours Truly’ from strong City sources of an orchestrated ramp & dump, pre an imminent Placing. Of course they’ll now deny it and maybe they’ll put it back a week or so. But placing they are…..

    Yes folks there’s a placing on the way for a minimum of £2,000,000+. In fact they need £4,000,000 just to stand still. (Explained Below). I’ve been watching the order book price action over the last fortnight which tipped me the wink that some thing was afoot. On research now undertaken, sources and I mean multiple City of London sources have confirmed that there’s a placing on the way! Which is why some of the ‘choice’ P&Ders are quietly off-loading their positions in-order to reload up in the placing. And make no mistake a placing IS coming! If you don’t believe me then ask the one man band bullshitter Adam ‘Dubious‘ of Jub Crapital the sacked broker of ‘Lord’ @ChrisOil or the House Broker ‘Turner you over Holy Pope’. As a matter of fact ask each one of them to sign a legal binder that RBD aren’t placing. You’ll get the usual ‘corporate waffle’. That’s because they’re selling! Why? Because they’re organising the placing!

    Now that’s not to say that Reabold don’t have potential, I tipped them on J&H and if you’d have listened to me then you’d have made good money. They have a decent story but that story is deliberately being used to sucker in the gullible to keep the share-price up so that they can get away another placing. Well that’s just not ‘cricket’ in my book….

    The last half-yearly report stated RBD had cash in hand of £353,000. The new team of Stephen Williams and Sachin Oza raised a further £5,720,000 in 2 placings ( £3.96M & £1.76M ) which fleshed the company coffers out with circa £6M in cash. In November 2017 £1.5M of that cash was quickly gobbled up via a 35% stake in the private Oil company Corallion. Following on from that in December 2017  a further £1.5M was gobbled up in an ASX listed company called Danube Petroleum to buy a stake of the Parta Gas project. It’s the worst kept secret on the London Alternative Investment Market (AIM) that they’re also looking to bring in another asset, which if they run true to form, will cost £1M+  if we consider the same level of investment in this new asset at say £1.5m that leaves cash at hand of £1.5M. Now don’t forget that the Colter drill is being touted for April 2018. The rig for that will wipe out the cash. Indeed the deposit will do that in itself. Placing.

    KILLER THAT NAILS IT!

    The killer fact that nails the placing is thus: Corallion are currently in the City of Mammon trying to raise between £3.5M-£6M to fund drilling of their UK license P1918 which includes the “Colter” asset. If Reabold don’t want their 35% stake heavily diluted then they will have to come up with at least £1.6M-£2.1M in cash to keep their 35% stake of Corallion and the assets. This would then leave Reabold with a negative balance of -£590,000!

    PLACING

    Answer. A Casino! Where the House (Corporates) tell lots of lies…

    Common sense dictates that to keep the lights on with say £1m cash at hand Reabold will need to raise at least £1.6M that’s before any cash calls from Corallion or Danube for project development and cash calls will come. Placing. To keep the company progressing its investment opportunities the company must raise £4m! Which is why they’re secretly trying to keep the SP up. Expect lots of ramptasic horse shit with denials from paid promoters. Then a placing.

    Shares are trading circa 0.65p which gives a market cap’ of just over £10m.  Cash raised will have to be at a discount which is par for the course on the AIM Casino. That means a potential whopping 20%-40% discount to current levels.

    Sell & buy back in the Placing. Because that’s what the P&Ders are sneakily doing!


    Viva!


    Daniel

  • AN(g)US Energy. It Goes From Bad To Worse…. Another #Placing On The Way…..

    AN(g)US Energy. It Goes From Bad To Worse…. Another #Placing On The Way…..

    The Angus Energy (LON: ANGS)  ‘Jackanory’ just keeps going from bad to worse. Todays ‘epistle’ from the ‘Kimmeridge Crackpots’ sees ANGS throw their hat into the Balcombe license. Balcombe was first drilled and abandoned by ConocoPhillips in 1986 it was then left to rot until the fracking outfit Cuadrilla drilled an appraisal well then a side track in 2013. Both wells were again abandoned after the ‘appraisal’ appraised them as worthless. That’s because no oil flowed from any of the zones drilled and obviously the ‘fracking case’ couldn’t be made at the time because of the political fallout.

    So what better for the Board of Angus to take 25% off Cuadrilla/Lucas Bolney Ltd and start up a rinse repeat operation screaming kimmeridge…. Great business…….

    Abandoned by 2 other oil companys…

    Lets spend over £4,000,000 that we don’t have and take 25% of an abandoned well! We’ll not put in the details of the well and the side track being abandoned, instead we’ll talk about kimmeridge. Even though we’ve got absolutely no production whatsoever from the kimmeridge clay either at Lidsey or Brockham. Apart from the facts that we have cash-burning capex at Lidsey and Brockham as well as hefty drilling cash commitments of £800,000+ at Holmwood1, not to mention the ongoing PLC costs of an AIM listed company….

    Sounds like the ‘Jackanory’ has failed to realise several salient points. The first being that most now know that the constant allusions to kimmeridge ‘Billions I tell ya Billions of Barrels of Oil’ are about as truthful as that well-known corporate bullshitter (Lord Liealot), David Lenigas not selling his UKOG/ANGS shares into the orchestrated Pump & Dump. The others being that common-sense dictates that ConocoPhillips and Cuadrilla deemed Balcombe to be a failure, which is why both companies abandoned it and Cuadrilla/’Baloney’ has farmed out 25% to ANGS.

    But hey let’s be rather generous, ’cause I’m a generous chap, and say that Balcombe actually flows oil. Well then you can expect that it will be a bread and butter piss poor producer on-trend with that other world-changing über ramped global changing ANGS asset, Lidsey. Scores on the production doors 40bopd that’s 20bopd net to Angus. Lidsey is uneconomic. And production at Lidsey is falling….

    I’d say that cash at Angus is like the great kimmeridge and Lidsey/Brockham fairytale OIL JACKANORY, rather thin on the ground and stretched to breaking point.

    There’s a huge financial gap that needs to be plugged to keep the ‘Show’ on the road. £5,000,000 placing looks likely to me. And for those ‘Howler Monkeys’ who are screaming NEX Bonds…. Please don’t make me laugh. You’ll note that the Company have not updated on the NEX Bonds since 29th September 2017. That’s because the NEX Bonds are dead in the water, them being tied to production and a declining 20bopd doesn’t get you much in the way of cash on the Bond….

    The share-price is headed down and could hit 3p. That’s about what they can expect to get on the next placing and make no mistake there’s another huge discounted placing coming.


    Viva!


    Dan

  • ECO (Atlantic) Oil & Gas. Major Multi Billion Barrel Mega Play Coming On Radar!

    ECO (Atlantic) Oil & Gas. Major Multi Billion Barrel Mega Play Coming On Radar!

    Target £1. Major O&G Companies are falling over themselves to get a slice of the pie….

    There’s a super O&G opportunity that has so far gone way under the radar in the Retail Investor/Trading world. And I myself must say that I, like you, failed to spot it until I took a call from one of my trusted sources who pointed me in its direction.

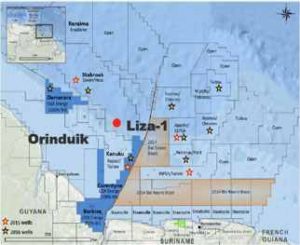
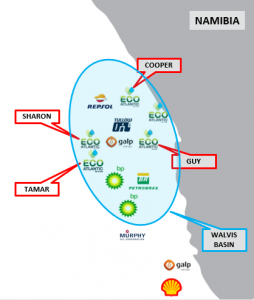
    Eco (Atlantic) Oil & Gas (LON: ECO) are a tiny oil minnow who came to market in February last year. They are an oil and gas exploration company operating out of  Guyana and Namibia, Eco Guyana holds a 15%-40% working interest with a possible farm in of Total (dependent on option for 25%) alongside Tullow Oil’s 60%, in the 1,800 km2 Orinduik Block in the shallow water of the prospective Suriname Guyana basin. The Orinduik Block is adjacent and updip to the deep-water Liza Field, which has recently came in with a mammoth oil discovery by ExxonMobil and Hess, estimated to contain as much as 2.5 billion barrels of oil equivalent, making it one of a handful of multi billion-barrel discoveries of the last few years. Exxon have made 6 major oil discoveries so far in this basin. Read Here. What’s important here is that some of these major discoveries are within circa 3 miles from the ECO acreage which is why they have Major O&G Companies farming into their licences. Majors are falling over themselves to partner up.

    In Namibia it’s the same story with their Cooper Block. Major O&G Companies are now partnered up. The Cooper Block has an 882 Million Barrels (BOE) of Oil (Gross Prospective – Best) resources ‘ticket’. ECO holds interests in four offshore petroleum licences with over 2.3 billion barrels of prospective P50 resources in the Wallis and Lüderitz Basins.  These four licences, Cooper, Guy, Sharon and Tamar are being developed alongside Major O&G Companies. That point is very significant. Majors do not ‘Partner up,’ unless they believe there’s a good Chance Of Success (COS), with small oil minnows. (Which is why no fooker will ever touch UKOG).

    The only thing lacking with ECO is their Investor Relations strategy. It is woeful. If they can get their message out then the SP should move upwards. Another pointer here is that Keith Hill has gone on the Board of ECO. Hill is the CEO of Africa Oil who now hold circa 20% of ECO. Should any of these plays come in then the SP of ECO would be in £s rather than pence. I’d expect to see this SP begin to rise throughout 2018 as the story gains traction in the market, a £1 target pre drills is easily achievable bearing in mind that Majors have become involved which basically means that there’s no problems regarding the technical ability to progress each licence to its logical conclusion: The drill bit.

    Well worth a punt and a hold. As ever get researching and do your DD! This Company could turn out to be one of the best oil stories of 2018. It has mega multi-bag potential. As well as operating in proven oil Basins with multi billion barrel transformational oil assets. As it comes onto the Retail radar expect an SP heading towards £1. Do not under-estimate the significance of the involvement of Major Oil Companies such as Tullow, Africa Oil, Total etc.


    Viva!


    Dan


  • Nostra Terra Fantasy RNS RAMP! 100 YEARS TO GET OUT THE ‘POSSIBLE’ OIL! PRE-PLACING RAMP! SHOCKER

    Nostra Terra Fantasy RNS RAMP! 100 YEARS TO GET OUT THE ‘POSSIBLE’ OIL! PRE-PLACING RAMP! SHOCKER

    Here we go yet again Nostra Terra Oil & Gas (LON: NTOG) CEO the lying deceiving scumbag Matt Lofgran, the man who shorts his own company and pays a self-confessed drug dealer to write his RNS’s has released another ‘corker’ today!  The druggie boy is now and has been ramping to fook on twitter and his no google ranking ‘valuethemarkets’ website, bought from that other ‘credible market coNmentator Mikey the strangler, shouting from the rooftops what is quite frankly wholesale lies and fraud to pump up NTOG pre placing.

    Apparently there’s been an increase in the oil reserves at one of his Stripper Well assets. Pine Mills. You’ll recall what stripper wells are? Wells at the end of their economic life.

    The scam being perpetrated here has been going on for so long it’s now an open, running, pus filled sore on the AIM market.

    Future potential upside in the Woodbine-Wagoner;
    The Tom Pepper of Tom Peppers is that there’s  “1.39 million barrels gross recoverable “Possible” reserves, “Internal assessment” based on an existing independent study” At 3.5 barrels of oil a day because that’s what is being produced per stripper well at Pine Mills, it would take 100yrs to extract the fantasy figures ‘Heralded ‘ today. It’s a big fat pre-placing whopper!!

    I draw your attention to the three words. One is ‘possible’ the other two are ‘Internal Assessment’  The translation is thus ‘possible’ because we can’t say definitely because we have no data whatsoever to prove it. ‘Internal Assessment’ This is what WE are saying IN-ORDER TO RAMP THE SP. Wholesale bullshit.

    Of course what they’re not saying is that there’s no cash and the company is in debt to their own Directors who now basically have to fund the business because no sensible investor would touch it with a bargepole. The only people in this travesty of a ‘Tale Tale’ are the Pump & Dumpers, who basically dictate the SP etc.

    Now we can all see the P&D going on here. For instance the 53% Permian play $40,000 field ‘Twin Well’ drill. Being spun as a major oil find. This is a ‘Stripper Well’ that will produce circa 35bopd at best!!! 53% of that is about 18 barrels of oil. Of course the delay in the official numbers is caused because yet again this is a stripper well and needs critical care to get it producing.

    When the ‘scores on the doors ‘ are released there’s going to be an almighty crash back to reality here.


    You have all been warned….


    Viva


    Daniel

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights