google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: gas

  • (BNS) Brokerman News Service Zenith Energy & the ECHO connection…

    (BNS) Brokerman News Service Zenith Energy & the ECHO connection…

    Operations at Zenith Energy (LON: ZEN) are finally beginning to bear fruit. Todays RNS on their well M-195 workover is very good news for the Company and its share-holders, you can read that RNS by clicking HERE.

    However it’s not todays good news that I’m writing on it’s the rumour/s that Zenith Energy are in detailed discussions with Echo Energy ((LON: ECHO). Now I don’t know what the discussions specifically involve but using my powers of northern common-sense, rather like Sherlock Holmes, it’s elementary my Dear Watson… Zenith must be after the Echo East Ghazalat 25% concession. We know that it’s up for sale, we know that it’s currently producing circa 100 barrels of oil per day and we also know that it’s in legal dispute. And we also know there’s other production opportunities on assets in that portfolio.

    There’s no chance of the current holders of the concession ever sorting out the problem which they created. But there is a good chance that if Andrea Cattaneo, ZEN CEO, gets the asset he’ll be seen as a ‘clean pair of hands’ and will be able to quickly remedy the dispute with the new top Chinese official now parachuted into Egypt to sort out the dispute. Cattaneo is a smart cookie and well known as a man who can negotiate. Just look how he’s ended up in Azerbaijan with a field now on it’s way to producing 1,000 barrels of oil per day…

    Now here’s me thinking out of the box. What could possibly be the deal? Well I’d expect that cash and ZEN shares or some form of future cash payback once the dispute and production is sorted out and back on track. Revenues currently owed to whoever gets the asset amount to circa $1.3M, sadly this is offset by the Chinese operator claiming production expense of circa $2M, but this like all bits of the dispute, can be and will be negotiated down by the right ‘clean pair of hands’. Now here’s a thing if ZEN offer ECHO shares in the deal then obviously Echo Energy would become a Major Share-holder in Zenith. There’s one thing I do know and that is that Echo would rather take ‘/cash/paper/promissory note’ in a genuine producing oil company than a Toxic POS like Nostra Terra Oil & Gas. Now if Echo were a major share-holder in Zenith what would they do with the stock? Could they then go on to buy them out or stick a Director on the board or maybe just quietly sell, who knows but it’s an interesting discussion I’ll be having with many a source this week. I’ll be in London Wednesday.


    Viva!

    Daniel

  • Echo Energy, Shell & other bits of the jig-saw!

    Echo Energy, Shell & other bits of the jig-saw!


    A lot of whispers and rumours currently doing the rounds in the city of Mammon (London) regarding Echo Energy (LON: ECHO). There’s no need to go through the history here as those reading this already, or should, know it, other than to say that as of now Echo are the hottest stock on the London Alternative Investment Market (AIM). This was confirmed to me over several days last week and this week as I conducted a whirlwind blitz of all contacts/sources specifically targeting Echo.

    The company have refused or prevaricated on my attempts to speak with them. No worries there. These guys do what they do and I do what I do. And that is to get the information good or bad. I tell it as it is. On this one it is yet more good news on the way.

    Echo have had a team/s in South America and are set to announce up to three (3) multi Trillion Cubic Feet (TCF) deals.  Bolivia, Argentina, Brazil and Chile are the most likely countries. Talks have been held with various ministries in those countries. These deals will be announced over the coming days/weeks but not months. The deals are all but done. Once the first asset is announced then there should be a steady stream of news.

    I have heard a few rumblings that Andes Energia (LON: AEN) may be in some way involved, however I cannot firm that up so tread carefully. What I do know is that Malcy Graham Wood, who knows and blogs on AEN, has been recruited as an advisor and may even have helped with introductions to various plays. So if I was you I’d harass him for his views. The pie eater won’t talk or correspond with me as I have yet to catch up with him for a tete-a-tete.

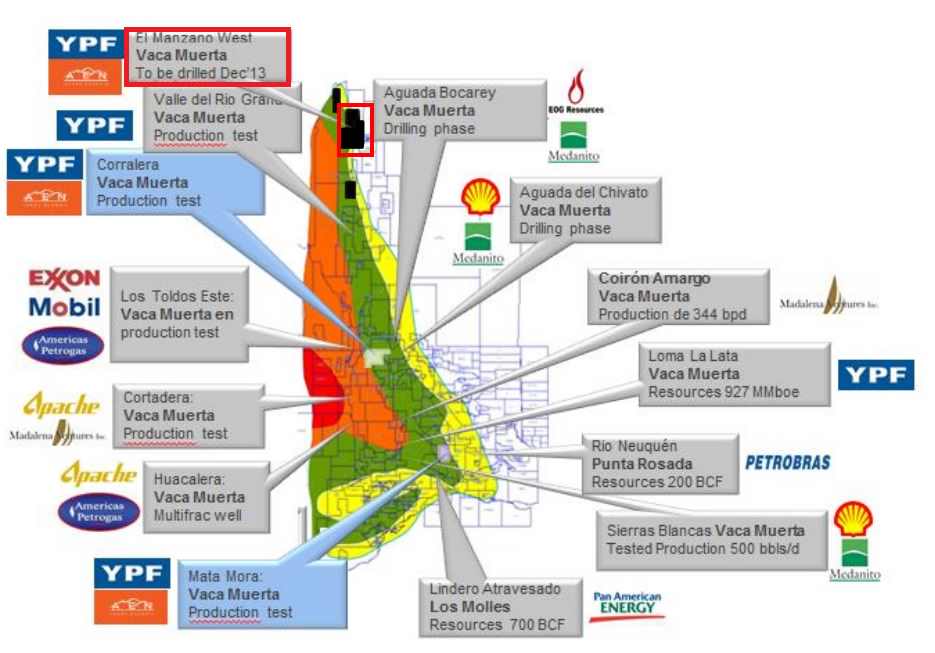
    Some of the targeted assets are sat right bang on top of a well known prolific gas/hydrocarbon bearing formation known as the Vaca Muerta. All the big major global oil players are involved and targeting South America. Now here’s an interesting tid bit of rumour. In Bolivia it is known by this blog that meetings have taken place with Shell or people who work for Shell, such as the Vice President and Country Chair at Shell, come on down Mr Orlando Vaca…. Not many people know that but they do now. He’s on LinkedIn check him out! Precisely what the tie-up or discussions were focused on isn’t known as it is being very tightly held. But one can infer that it’s either about data/people/asset/s or some form of assistance from Shell either directly or in-directly.

    It’s all to play for here, still very early days and a long way to go. I personally ignore the intra-day trading and the usual guff being spouted by those who failed to get in or spot the opportunity. i.e. those who are not making money and seeking to extort payments for their investor shows.

    Remember there is risk, just as there is risk crossing the road. However the key here is to track the Institutions who’ve backed the team with circa £35,000,000. Ride their coat-tails. That is the pointer here. But of course you can sell or buy at any time. The choice is yours.


    Viva!

    Dan

  • International Financial Blogger of the Year, Says “Sirius Petroleum is about Funding!”.

    International Financial Blogger of the Year, Says “Sirius Petroleum is about Funding!”.

    Is it getting ‘serious’ at Sirius Petroleum (LON: AIM) ? I’ve been looking into Sirius for the last four weeks as a close confidant of mine suggested I take a look. When I asked why I was told that there’s a potential farm in on the cards, any funding of the OLM drill offshore Nigeria, which is I believe an appraisal well, that means the oil/gas is already there, could send the sp on a charge. Now my source pointed Sirius out for their own ulterior motives, they hold significant lumps and have tried to bring pressure to bear on the Company to reveal who the potential farm-in partners are. Nothing from the Company who believe that any leak could jeopardise talks. Many hands make light work. What Sirius should do is this: If they are indeed close to a deal re’ farm in then they should announce it asap. If they’re not then they should also announce it asap. Prevarication either way makes for speculation. Hence why I’m being used to try to force the pace. There’s no flies on BMD. I know exactly what sources are up to here. They want an announcement either way! Whisper is it may come in 4-8 weeks.

    I also know that there’s a lot of clever PI’s in this one and sentiment is building as the news on funding seems to be going well. Of course some of this has already been trumpeted out months ago on the super information highway (Internet), which does lend credence to what sources are saying. But it doesn’t definitively prove it up. But make no mistake Sirius Petroleum are in talks with potential farm-in partners.

    A brief rundown on the company reveals some interesting facts. I’ve gone all out on this one, as I see it this matches the criteria I use for trading/investing. If you want to know what that is then watch this and join this

    Sirius are a company that are in a quandary. They have potential oil/gas in shallow waters but do not have the funds to drill. They are close to a good revenue stream. The fact that they’re partnered with well known leading oil field services providers such as Schlumberger does take away some of the risk. But make no mistake there are risks here. The main one I see isn’t finding the oil it’s a sneaky placing should the SP charge up to 3p.  So be warned there is risk. As with all oil/gas minnows the board will raise cash if they can. As far as ‘Bobo’ their CEO is concerned, he’d be failing in his duty if he failed to raise cash when their SP was 3p etc. Never trust a broker or a CEO they’ll pick you clean and come back for your dry bones to make soup! That’s not to say that the management are shite. Far from it, Sirius have performed very well for their share-holders and Mr Bobo must be given credit. He’s also very well connected in Nigeria and probably the best person to bring Sirius’s assets to full producing potential.

    When you have International oil service providers offering turn-key services, equipment and personnel, then the risk becomes less as they see it as a ‘low-risk development project’.

    The Competent Person’s Report (CPR) on the Ororo Field, by Rockflow Resources, gave a Mid Case Net Present Value (NPV10) of the asset of circa $50M, based on a $50 per barrel flat oil price for the life of the field. This would give peak oil production of 6,000 stb/d and peak gas production at 25 MMScfd, which equates to combined peak production at 10,310 barrels of oil equivalent per day (boepd).  That is a pointer that Sirius have a real asset and not a clutch of piss poor dried up stripper wells. The Ororo field is real.  It’s in a world class oil bearing region. The field lies in shallow waters offshore Ondo State in water depths ranging between 23ft and 27 ft and it is adjacent to Mina, West Isan, Ewan, Eko and Parabe fields – all of which are operated by Chevron. Ororo is located in a world class petroleum system.

    As I understand it all of the backhand, oops sorry it’s Nigeria, backend costs will come back to Sirius should the field reach production. The netback to them is about $25 per barrel plus the backend costs. Then they revert to a 40% share of the production. There’s probably millions of barrels of oil and mucho gas. But it’s all down to funding. That in a nutshell is Sirius. I’d urge anyone interested to read their CPR. Try to get a feel for the Company/assets and remember fundamentals here aren’t great. Funding is the key. 

    Turning to Sources and Info’

    My sources are telling me that Sirius could be in negotiation’s with 5/6 potential funding partners. One of them is rumoured to be a UK Major Oil/Gas producer and a footsie one hundred company. The theory is that they believe that there’s potentially significantly more oil/gas in the Ororo field. This makes sense only if and it is an ‘if’ the whispers are true. It’s rumoured that funding partners may think that there’s a potential 20,000 barrels of oil or equivalent, potential per day in Ororo on full field development. Now again be aware that some times sources try to talk the talk. But again My sources are good. That doesn’t mean to say that there is 20,000 boepd in Ororo only that potential partners may think this. Proof is in the drilling etc. Now if you take a position before researching them then remember there’s risk here. However I don’t believe; I know they are 100% in partner discussions. Nothing is certain other than death and Manchester City winning the 2017/18 premier league…

    Get researching them and good luck.

    Viva

    Daniel

    NB. I really am milking the ADVFN International finance blogger of the year award….. If ya got it flaunt it…. 🙂
  • Nostra Terra Oil & Gas ClusterFook of epic proportions. SELL! SELL! & SELL!

    Can it get any worse at the POS that is Nostra Terra Oil & Gas (LON: NTOG)? The answer to that question always seems to be ‘Yes’. The Company are consistent in one respect. That is failure. Nostra are a serial failure run by an Ex estate agent from the USA. Who doesn’t have the Deal Flow, expertise or the common sense to run a small oil company. He’s totally out of his depth. Come on down the shorting CEO Matt Lofgran. Not only has Lofgran lied regarding stock ‘loaned to YA Global (the well known shorting crew) he has consistently with-held market sensitive information most notably on their 25% in the nightmare that is East Ghazalat in Egypt. Readers of Guerilla Investing will be all too aware of the disaster that has unfolded.

    Sources indicated to this website a travesty of gargantuan proportions…. Production has now more than halved, not so much as a peep out of Lofgran regarding the steep decline in oil. No revenue has been received, ever! Pump jacks have failed on some of the wells, again not so much as a peep, cash calls from North, the Chinese operator, have gone unpaid by Nostra Terra, an Oil field service Company (Lufkin) was owed close to $1,000,000 in January 2016 and had refused to supply any additional equipment. The JV  has basically accused the Chinese operator of Fraud. They’ve also accused them of technically poor work!

    Currently Nostra Terra are in full default for a sum that is way in excess of monies owed to them. Nostra refuse to recognise the default. It’s a case of the tail trying to wag the dog. You do not go in guns blazing dictating to a National Chinese Oil Company demanding that they justify their track record, employees, costs and expenses while at the same time telling them that their technical ability is ‘shit‘. It is a clusterfuck of epic proportions and it will only end in tears for any one daft enough to keep holding this stock. Of course you could wait for the collection of stripper wells that is Pine Mills, to come good. Yet another batch of sucked dry piss poor assets used to flesh out and divert attention from this shitty aim disaster! Or you could wait for the next Placing, The recent one had to go cap in hand to pump & dumpers who paid 2p per share. Of course these are now ALL underwater! lol! Karma…..  If I was them I’d cut my losses and get the fook out…..

    North has now questioned the legality of the consortium. A notice of default was served on them by their Chinese Operator on 17th January 2016. Nostra hadn’t paid a single bean since November 2015. That position has not changed. The Nostra Terra JV owes millions of dollars in unpaid cash calls to North! North are deliberately allowing East Ghazalat to run down because the JV is not paying its share of the costs. Adding insult to injury Nostra and their JV partners have tried to replace North as the operator!!! You can’t treat a National Chinese Oil Company like this!

    In January 2016 the General Manager of PetroSafwa clearly stated the asset was loss making unless the price of oil was $70 per barrel or higher!!! PetroSafwa are the joint venture operating company!!!

    Of course all of this has been deliberately keep from Nostra share-holders. It’s a bomb shell Lofgran has hidden from the market! Nostra Terra are out of control and in the grip of Pump & Dumpers….

    With the re-launch of Independent Resources as Echo Energy (Echo Energy (LON: ECHO) there was a chance that this major disaster could have been resolved. Echo have bigger and better things to progress with their time and have washed their hands of the whole Egyptian Nightmare. It’s known that they are actively in negotiation’s to off load East Ghazalat asap!

    It will take a new JV partner whose not tainted with the NTOG association to sort this out. There’s no chance, after close on 18 months, that Lofgran, whose responsible for the failure can do it. He should resign immediately.


    Viva

    Dan


  • Saffron Energy. There’s more to come… Gas that is!

    Saffron Energy. There’s more to come… Gas that is!

    Today Saffron Energy (LON: SRON) finally announced what was already basically known by those who follow and read www.guerillainvesting.co.uk  That is that Bezzecca gas production has now come on stream at 30,000-40,000 scm per day. This when added to 10,000scm currently being produced from their Silaro field gives them production of 40,000-50,000 scm per day. Financially this is over three hundred thousand euros per month. Circa £250,000 per month times this by twelve and we get £3,000,000 per annum in revenue. That is a phenomenal success story in the world of micro-cap oil and gas.

    SHAREPRICE

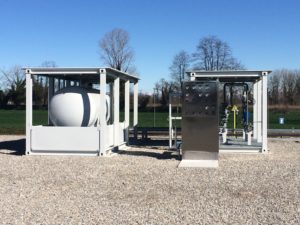
    Shiny ‘Mac Shine’. Brand new kit now producing…

    The SP has spluttered on very good news! When in actual fact it should be heading towards 10/11p etc. One of the quirks of the AIM is that impending good news is usually forward sold into by the brokers and the ‘canny’ high net worth’s. You can see it in the late trades that were being announced over the last two weeks. Profit taking. Every one is entitled to take it. So when you’re looking at Saffron or any other Company remember think ahead and don’t be discouraged by a rise that spluttered on good news. There’s always a reason for it. Normal service will be resumed once the SP settles down.

    WHISPERS

    Sources here are indicating that gas production from Bezzecca could easily surpass 50,000 scm per day as the Company work out their best flow rates over the coming weeks. Again any increase in production will significantly add to their revenue. These are a bargain at todays SP. I did hear that their CEO (Masterman) was in the UK and will be having a tete a tete with investors this week. A question I would ask if I was their would be this; “Bearing in mind what was being discussed on the recent site visit, will the 100,000scm per day be reached this year?”

    Great little producer this. Could be 12p-15p by the end of this year….

     Viva!

    Dan

  • Saffron Energy RNS Imminent! Gas flowing! Confirmed!

    Saffron Energy RNS Imminent! Gas flowing! Confirmed!

    It’s great news reaching the ‘International Finance Blogger of the Year’ (I only put that title in to annoy certain people 🙂 ). When you have a ‘Big Stick’ it’s nice to beat a few people with it lol!!!

    Hopefully those at Saffron will be forced to release an RNS today on the back of this small Blog.

    The Gas Meter Dials are Whizzing around at Bezzecca !

    Gas is flowing at Bezzecca. Reports of a minimum 30,000 scm per day that equates to about 200 barrels of oil or equivalent. This is now in the public domain so the Company should release an RNS immediately!

    Great news for the Company and a testament to a genuine small oiler that within a few months of their Initial Public Offering (IPO) have now brought in a major revenue stream. This is a super achievement. Think of ALL the companies in this sector that have for years upon years promised so much yet delivered absolutely nothing other than fleece retail investors and they’re still at it today!  The road to AIM is littered with broken promises and broken companies. Saffron Energy have taken 2 months to do what most of the piss poor lifestyle comps’ still haven’t done in 4,5,6 years!

    Well done to all at Saffron. It’s a refreshing change to be congratulating a company rather than castigating it!


    Viva

     Dan

  • Zenith Energy Set to announce 250%-500% increase on 1st workover!

    Zenith Energy Set to announce 250%-500% increase on 1st workover!

    Share-holders in Zenith Energy (LON: ZEN) are on tenterhooks awaiting the news from the companies first well work over in Azerbaijan.  Oil is flowing from well M-195 directly feeding into storage tanks. That means that the workover is complete, more importantly successful. I’d now expect that this Blog will force an RNS this week.

    The whisper here is that production has increased from well M-195 by a stonking 250%-500% the number is significant because if you forward think it by X 20 you can extrapolate a ‘potential’ in excess of 1200 bopd by March 2017. Actual cash revenue would increase many fold. Production from the first well should come in between 40-60 bopd. We know they are currently working on more wells so I’d expect news to keep dropping of mainly successful re-completions/workovers.

    Now remember there’s a lot of behind the scenes activity going on here that the Company are not reporting, such as further asset producing targets. I can exclusively reveal that Cattaneo (CEO) is known to be in negotiation’s to bring in more cash producing assets from Italy, Egypt, Azerbaijan and Asia. The key here is to either trade on the rises or hold as they incrementally increase revenue/production.

    There’s also the Gunsynd (LON: GUN) Lenigas threat of a corporate action to Takeover and oust the present management. The Board here have acted very quickly to see off these corporate hyenas. However I am still not convinced that they’ve gone far enough. The fat Aussie will not give up easily. Fat man is eyeing their increasing cash revenue and would love to get his fingers on the bank accounts. That would be disastrous for share-holders as it is Cattaneo who is the main-stay of all the deals negotiated in Azerbaijan/Italy. Lenigas would be out of his depth and doesn’t have the skill-set to progress in Azerbaijan.

    Target 15p short term. Longer term say next 10-11 months, 20p-25p. Of course I may be wrong, what do I know……,

    Expect an RNS this week.

    International Financial Blogger of the Year  🙂


    Daniel Levi


  • Nostra Terra Oil & Gas Egyptian Cover Up! Omnishambles!

    Nostra Terra Oil & Gas Egyptian Cover Up! Omnishambles!

    Once again I write on the utter omnishambles that is Nostra Terra Oil & Gas (LON: NTOG). I urge every one involved to contact The FCA, AIM Regulation & their Nomad to demand clarification on what is wholesale market abuse.

    Image result for mummified
    Nostra Board Meeting Egyptian Style!

    As part of my attempts to bring some skin into Sefton Resources I moved within hours of the Independent Resources announcement last week. My interest was  regarding asset/s that may or may not come on to the market for sale. I discovered, after speaking to the operator/s and various interested parties that production has basically HALVED at East Ghazalat. That production decline has been going on for months. Not so much as a peep from Lofgran or their Board. Nostra have deliberately withheld market sensitive information on a steeply declining production rate in Egypt. It is a ‘Cover Up’ of material facts that should have been reported to the market and shareholders.

    This explains the Company’s change of tact in ‘Canning’ reporting production figures to the market.  I also learned that the company maybe close to a default on the assets in Egypt which are the subject of an on-going legal dispute, a clusterfook of epic proportions.

    The failed placing, which was exposed in the public interest by myself, has now lead to a change of Broker. Come on down Smaller Company Capital Limited. A tiny bucket shop broker with nine clients. Wonders never cease, the broker of a well known Pump & Dumper who has a history of twitter trolling and barefaced lies. And it just so happens, coincidently… One of the ramptastic morons who regularly talk utter shite about Nostra! And yet again the same man is in regular contact with Matt on twitter, via email, podcast and telephone. What a ‘Coincidence’!!!

    Remember the rule of thumb. Change of Broker always comes because they’ve exhausted retail appetite from the previous Broker. Expect a placing here.


    Viva!


    Dan

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights