google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Investment

  • ADVFN SHAREHOLDER ACTION GROUP?

    ADVFN SHAREHOLDER ACTION GROUP?

    The ‘Natives’ (Shareholders) of the much maligned ADVFN are getting restless. So restless that they reached out to me last Friday 22/11/2024. That approach resulted in several Telegram group chat’s and a video meeting.
    The Tele’ group has over 40 members/shareholders who stated that they’re in contact with other small time holders and have got hold of damning information of malfeasance within ADVFN. Which I took with a pinch of salt.

    One groups ‘damning information’ usually ends up being no more than wishful thinking, as in this case claimed exorbitant Director expenses. That’s not going to fly. It was a very interesting weekend, quite funny in many ways not least that they asked me to help, formalise and draft a Requisition, ‘You know the ropes Dan on how to get the job done’. Even offered a ‘fee’ and a position within the company ‘Head of RestructurIng’ LOL!

    Their lead man/woman, whose identity and holding I have confirmed via the actual ShareHolder Register they provided, (No mean feat in itself to get hold of) came across as a decent individual. I did give them one tip. Don’t organise on ADVFN chat BBs and for fucks sake never name your source on the ‘inside’. Loose lips sink ships. Fortunately that dies with me. Lesson learnt.

    Today’s 5% drop in the SP will no doubt add fuel and more members to the Action Groups cause. But is that ’cause’ a lost cause?
    I can vouch that the Group certainly has enough stock to call a Requisition, but that’s far short of ADVFNS’ Executive, family & no doubt ‘friends’ holdings of at least 30%, so it’s an upward struggle, but there are, this is key, other ‘Malcontents’ and just over 28% of stock ‘not in public hands’. So theoretically there’s 6o% ish of votes out there. That would need a huge concerted push of a ‘clandestine nature’ to reach out and pitch your ‘Antidote’ to the current ‘Malaise’ engulfing the company and it’s share price. They certainly have the stomach for it. However traipsing round the City of London, and beyond, pressing the flesh campaigning for votes is time consuming.
    I’ll be meeting them in person next week in the City of Mammon…


    Stay tuned…

    Viva

    Daniel

    x

  • ADVFN: Takeover Inevitable?

    ADVFN: Takeover Inevitable?

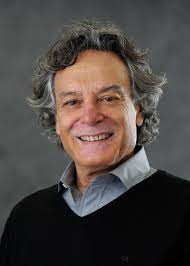
    In the wake of the ‘rumoured’, Israeli group front man, Ex ADVFN Director, Yair Taumans notification (TR1) that  doubled the holding to 18.31%.

    Can the present Board of ADVFN: (LON AFN) keep control of the company?

    That’s the question doing the rounds in the City of London as you read this. 

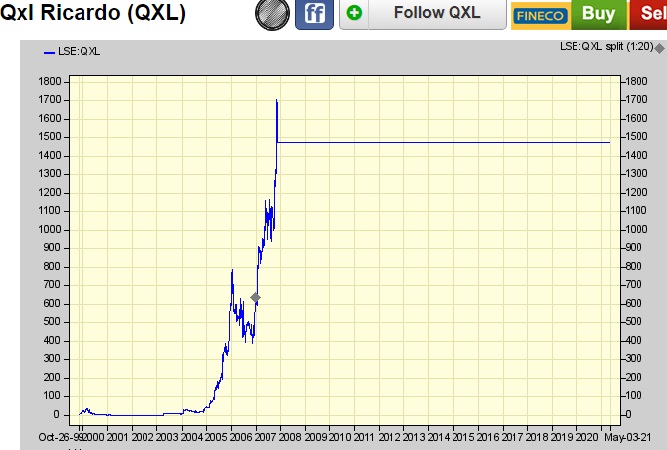
    Looking at the QXL history and the ‘contentious’ 2015 attempt at wrestling control of ADVFN, it’s almost certain, there will be further increases in holdings from both combatants in the fight for what the takeover group probably see as a potential lucrative cash cow that’s under-performed. After taking control of QXL , the sp was sub 1p eventually rising to a staggering £17, before the company was bought out for close to £1B, at £14+, in 2007. I’m sure the Board of ADVFN are aware of exactly who’s involved, what they hold, both declared/undeclared and who is supporting them. These are mega wealthy people and know the market inside out; Yair Tauman, is a highly respected, Professor of Economics at State University of New York, Stony Brook and the Director of the Stony Brook Centre for Game Theory.

    The conundrum is, will those currently trying to ‘kick in the front door’ cease and desist and knock on the front door? If so how will the present Board react? Rumours current are that there’s a shadowy concert party pulling the strings, through nominee accounts from as far away as USA, Israel, Cyprus, Switzerland and the Bahamas to name but 5 of the many locations I’m hearing.

    Those running the Company are duty bound, if approached via a ‘polite knock’ on the front door, to enter into negotiations. ‘Thems’ are the rules corporate and regulatory. If you’re approached then you have a duty as well as a responsibility to sit down and listen to the proposal. It’s as simple as that. Hammer out a deal. In the real world of business everyone is up for a deal. ADVFN and the Professor are no different.

    Prof’ Yair Tauman

    As it stands, I can’t see these people making the same mistakes as 2015. Both parties are corporate, business, savvy, both know that the other will not blink in a hostile takeover situation. But is that really in the best interests of shareholders?

    ADVFN could probably muster 25% to 30% of existing holders to keep control. But that would not be enough. If a requisition drops, which is by it’s very nature ‘Hostile’ then their only way of defeating the Israelis is via ‘legalese‘. As I read it, the interested party can call up or will soon be in a position to call up, over 40% of the votes…

    So, the value drivers at the moment are increased holdings TR1s from the Tauman group, as well as Director buys and option, warrant exercises by the incumbent’s. That should or could catapult the SP to between £1/£2. Of course if an RNS drops announcing ADVFN are in official takeover talks or a Requisition is RNS’d and these two are highly likely given the history. Hindsight, with a look at the meteoric QXL rise, then £4+ isn’t out of the question from a current share price of 63p. If I was either of the combatants I’d reach out officially and get in too talks. That’s the key here to it all.

    Make no mistake there’s a corporate battle being played out behind the scenes for control and the share price will rollercoaster higher.

    As always take care. Greed is the enemy.


    Viva

    Dan


  • Online Blockchain. Here’s what’s going on & why they’re deliberately ‘Damping Down’ on news-flow…

    Online Blockchain. Here’s what’s going on & why they’re deliberately ‘Damping Down’ on news-flow…

    Let’s try to decipher exactly what’s going on at Online Blockchain Plc (LON: OBC) and quantify what the company do and where their headed as opposed to the screamers & howler monkeys committing hari-kari on £14k worth of trades that at one point had the SP down 20%. It’s abundantly clear that those trading the stock do not understand Cryptocurrency, let alone Blockchain or the liquidity position of a company with circa 8 million shares in issue, 4/5 million of which are tightly held. As for the Market Makers who’re short of stock, I’ll deal with that further down the piece.

    If you don’t understand Blockchain/Cryptocurrencies then this stock is not for you. Get out now and trade/invest in the space that you understand, such as the resources or bio/pharms etc You wont make any money trading in a sector or a bubble that you are not ‘savvy’ with, regardless of how ‘cute’ you think you are. Sell up & move on. Now some people did that in the dot.com era and we all know what happened to those who sold such ‘God Awful’ companies like Facebook, twitter, Yahoo, Microsoft, Napster, MySpace, Amazon, Google etc. These companies were ALL laughed, scoffed and ridiculed on a daily basis in the heady days of the dot.com era. That isn’t to say that OBC are going to be Microsoft. I simply state by implication that the above listed companies swallowed up and bought out hundreds of smaller dot.com companies on their journey, one that made them the super global behemoths that most of them now are. Fortunes were made, and lost, by lessor companies and those that invested in them. Read Here

    OBC yesterday announced the roll out of a new coin ‘Brazio‘. Now granted the RNS’s from the company have been thin on the ground and granted again, rather bland. In fact one could say that the company are deliberately ‘dumbing down’ their news flow. Now there are reasons for that which I’ll address. It was made very clear to those who went to the Pizza Crypto event that they would not announce negotiations and would only announce ‘Done Deals’. The company have been in talks with the Gibraltar Stock Exchange (GSX) and a third-party on a potential deal with a Global fashion house (Vivian Westwood). Those negotiations were not RNS’d, if they had been then the SP would have went through the roof. Equally because both sets of talks have now (Stalled) failed to materialise there doesn’t have to be an RNS. That is the ‘rationale’ of the OBC board on their deal-flow. (If you’re looking for pump & dump horse shit of the #Liargas kind then you wont find it here). 

    Currently OBC have a myriad of revenue generating streams. The Mining Operation generates between $150-$250 per day. The return on investment (ROI) will take circa 10 months. (Far better than a small oil & gas ROI and much quicker). That operation is currently being expanded. I know this because I’ve seen the delivery of further crypto-mining equipment. Now lets hazard an estimate that it’ll take 2/3 months to install the new equipment because crypto mining brings with it challenges. Apart from the security aspect, there’s the space, ventilation to cool the machines, and the noise. All these operational challenges have to be over-come. As some-one eloquently put it on twitter “It’s like pushing string up a hill”. So in 3 months OBC could be generating in excess of $500 per day. Then there’s their Crypto-currencies each coin generates a plethora of small revenue streams from the various transactions. The bigger the hash-rate the bigger the uptake the more transactions. OBC do not have two crypto-currencies they have four. Two have not been RNS’d. The market cap’ of Plus1 has gone from zero, to at its height $2m/3m. It’s now circa $1m. (Bitcoin didn’t hit $15,000 in a day, a week or even a year. It took time) If all four currencies total $10m, $4m or $50m in market cap then that generates revenues. Business rule 101. Create revenue streams to flesh out your company. The secrecy and fear surrounding listed Blockchain companies, especially one that’s run by people who’ve excellent working relationships with the London Stock Exchange, is the single biggest anchor on this share-price. Fear of pissing off the exchange is holding the SP down.

    The company is actively in talks with a myriad of partners on potential deals. There’s a whisper that they are developing an exchange in either Brazil or Argentina. I hear that there’s new Application/s being tested, one is rumoured to have generated $1500 per day. What it is we don’t know. There will be no RNS’s unless there’s a signed dealIt is the first major deal that they announce we await. If you want pump & dump then leave the building. An update on their revenue generating streams would be more than welcome. Will we get it? Faith can’t move mountains. But faith in the integrity of a company can move share-prices. Remember it’s a Blockchain roller-coaster. If you’re trading, it’s where you get on and off that counts.

    Likewise Market Makers (MMs) who’re short of the stock and deliberately mark the price down to sucker in the gullible. 11% down on a 3k share offload! To beat an MM you hold your stock because of thus: Online are fully cashed up, debt-free and hold a huge slug of ADVFN shares and are revenue generating with a potential company making deal. More importantly they’re a genuine company run by genuine business entrepreneurs. It’s already hit £1.85p and it will ‘hit’ again and indeed surpass. Time is the key. If you can’t understand the sector then move on.

    The Blockchain sector is cut-throat, commercial confidentiality to protect your developments/talks is paramount. Like it or not it’s their strategy.


    Viva!


    Dan


  • #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    There’s a ‘hefty‘ lot of  Reabold Resources (LON: RBD) investors/traders out there, awaiting news on the company’s up-coming drills. Wick & Colter. If you don’t know what those drills are then I suggest you get researching because unlike certain other UK Onshore Oilers the RBD drills (Offshore UK) are the real deal. A ‘Roll of the dice’ with a decent chance of success (COS) on BOTH drills, particularly Colter. Which, once they actually get to rig ‘mobilisation stage’ will push this SP much higher. I personally hold some stock here, so am always on the hunt for information. The problem is the company are not releasing the news. Good or bad I publish what it is. You can moan all you want but it’s better to know what’s going on than not. It’s how you make money and it’s how not to lose money. It was pencilled in for a 12 noon release but I’ve been cashiered into 12:30pm ’cause one of the ‘twittermen‘ has to finish his go-karting with the family. What a nice guy I am….  🙂

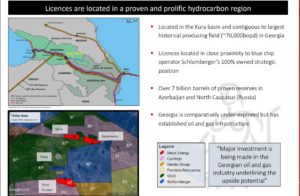
    Now it’s been a long time since I wrote on Reabold and new information has come my way via the BMD ‘sauces‘ pipeline. There’s a major whisper that this company are farming into a Georgian gas asset which is ‘controlled’ by, the soon to IPO, Block Energy. Fortunately I’ve managed to get my hand on not one, but three Block Energy prospectus’. The Georgian gas asset is flagged up as “Substantial potential from 608 Bcf 2C gross unrisked contingent gas resources at West Rustavi, analogous play being tested by Schlumberger in 2018 and 2019 on adjacent licence”

    This is more good news if it comes to pass, as it further flesh’s out RBD with another potential quality licence farm-in. A value driver.

    In the constant hunt for good returns, Reabold, sub 1p, could provide excellent returns. The SP could hit 2p/3p/4p/5p dependent on how successful they are. It will almost certainly break through 1p soon enough.


    Fully funded with a big following and an even bigger following waiting on the side-lines to jump in once the drills start to crystallise as a reality. The placing has been done so unless they’re running a ‘double bluff‘ holders should be able to sit tight and wait for the move upwards. Of course the placing flippers are still at work exiting, however most of them will now be out. Good place to start researching is HERE

    This is going over 1p soon enough. The only question is when? Not if! But as ever do your own research etc. Remember I hold stock as such I could be construed as a Rose Tinted Spectacle wearing leftie… 🙂


    Viva


    Dan


  • Anglo African Oil & Gas  Watchlist/Research!

    Anglo African Oil & Gas Watchlist/Research!


    HomeApologies to all this one should have gone out on Jekyll & Hyde pre-IPO.  Unfortunately the ‘Securitate’ deemed it too sensitive and conflicted. Hence why it’s now going out on Guerilla Investing. Some minor changes post IPO… You can join the UK’S Premier Tip Sheet Jekyll & Hyde by CLICKING HERE

    Get Anglo African Oil & Gas (LON: AAOG) on your watch lists and research it! START HERE. They came to market yesterday. What I like about this one is that the placing ended up hugely over-subscribed.  It’s always a good sign. They have great potential  going forward very quickly to increase production in 2017. The management are a decent lot and have been working for two years on their IPO. The Directors intend to distribute free cash to shareholders through regular dividends, once production reaches a sustained level of 1,000 bopd and provided that oil prices are not less than USD 30/barrel. Now that’s some thing no other AIM oiler will do. It’s a good pointer. Also some of their close neighbours such as ENI have production of circa  5000 barrels’ a day from basically the same geology/horizon as Anglo plan to drill.

    Anglo currently produce 38 bopd but it is in their potential to increase this to circa 750-5,000 bopd that could push their SP much higher. Now if they get anywhere near this figure then the SP will correspondingly move upwards. Everything is now in place. Assets, infrastructure, funding and more importantly sentiment. Which is very strong. The only drawback when I first penned this piece was their website which looked like it’s came out of Noah’s Ark. Thankfully the powers that be responded to this concern and updated it to a nice healthy one. In line with the rude health that AAOG are now in.

    The assets are located in the Republic of Congo (RoC). Development of the near offshore Tilapia field could significantly increase production in the near term to circa 250/750bopd. “The company also aims to conduct exploration and appraisal of proven deeper reservoir targets to raise production to in excess of 5,000bbl/d in the medium term. The acquisition of Petro Kouilou would result in AAOG gaining extensive onshore surface infrastructure comprising: 5,000bbl storage tank, separator, in-field pipelines and other associated facilities. These facilities would cost US$15-20m if they were constructed today. Consequently, the company will not need to spend any other capex than that associated with the proposed work programme. The new wells can simply be connected and new production can brought onstream almost immediately.  Low-cost workover programme. AAOG intends to workover two wells on Tilapia field at a cost of US$300,000 which would increase production from 38bbl/d to 250bbl/d. On the assumption of a successful IPO this work would be conducted during 2017.”

    So the drivers of the share-price are many and varied. There’s existing production, increasing production, multi million-barrel potential from existing production and multi million-barrel exploration potential. The IPO price was 20p. If you can get in as close to this as possible then hold for news on increasing production/exploration. How high could it go? On any where near 5,000bopd it will rocket. On a bread and butter 250-750 bopd it should get to 50/60p. 25p-40p should be your near term target. Remember profit is the game. It doesn’t matter if you make £100s or £1,000s derisk as you go. Good solid little oiler that could/should be financially self -sustaining by the end of 2017. By that time the bopd will be many multiplies of where it is today.


    Viva!


    loginDan


  • Independent Resources = Sound II “Team Parsons” Effectively Takes Control. BUY!!!!

    Independent Resources = Sound II “Team Parsons” Effectively Takes Control. BUY!!!!

    SOUNDRarely does such an early stage opportunity come along in the markets for retail investors. Todays RNS from Independent Resources (LON: IRG) could quite possibly be one of the best investment/trading opportunities for the last 5 years. This has taken the markets by total surprise although I did know of ‘something’ but couldn’t quite nail it down. Believe me I tried every trick in the book, and every trick not in the book to get the name of this company for my followers/readers. The secrecy surrounding this has been a phenomenal success akin to the success of the people now coming on to the Board of Independent Resources

    Make no mistake this is now not Independent Resources. This is Sound Mark II. And we all know the Sound Energy story. James Parsons the goldenboy of AIM has transformed Sound, with a £600,000,000 valuation, with more to come… He now comes into a micro-cap distressed IRG with a market cap’ of £1.500,000. The value alone of Parsons and his team of proven management should be worth at least £10,000,000 on the MC of IRG.

    Just where this share-price is going to end up over the next 2-3 years is anybody’s guess, let alone the coming days and weeks. But one thing is certain. It is going into the stratosphere! If they can replicate 10% of the Sound Energy success story that’s a £60,000,000 MC valuation. The mind truly boggles at the potential here…. Do not wait for the Open Offer. The chances are most will not get in.. Get in now!

    Just what has brought this event to the market? Well here’s a wild guess. Imagine the frustration of running a USD1 billion company (fully diluted) with lots of cash and strong paper… originating dozens of world class but initially small scale assets/deals and not being able to pick them up as they aren’t Mediterranean and aren’t large enough for the company and won’t fit a future purchaser / liquidity event. To put that into layman’s terms. The Sound team are awash with top class assets but have no where to put them because they don’t fit into Sound Energy’s business plan, area of operations and scale of size.

    The JP Effect…

    Cue Sound Mark II – an early stage vehicle with the same culture, top team and ethics.  Assets are I am sure ready to back in. I know Sound very well and I can guarantee that assets are already lined up and ready to be backed into Independent Resources. If they weren’t then this deal would never have been signed. Those assets will not be piss poor stripper wells!!  They will be top class and in typical JP style, before the launch, he offers private investors the opportunity to join in on ‘ground floor terms’ – to participate in the journey.

    Get in on the JP magic again. This is the best opportunity I’ve come across in the last five years. It’s going to be emotional, a roller-coaster of events, trials and tribulations. A re-run of Sound Energy. Only this time we ALL know where this could go. It’s going to rocket. Placings or open offers will be massively over-subscribed. Every Sound Energy shareholder will pile in, Retail will pile in, Brokers will pile, Institutions will pile in even the Pump & Dumpers will try to get in on the journey… Buy! Buy! Buy! Hold for 12 months then reassess. As sure as night follows day every man jack and his/her dog will jump all over this in the coming months. 2p-3p target. But in all likelihood much, mucho, more… Three years down the line this could be many multiples of 2p/3p a share. We simply do not know how high this is going…. But UP it will go…..

    I’m in!


    Viva!

    loginDaniel


    N.B (Not that it’s anyone’s business) Daniel Levi declares a financial interest here.   🙂


  • Master Investor Show 2015. Free Tickets! Use code BMD2015


    jimpicAs you all know Sefton Resources Inc. (LON: SER) are presenting at the Master Investor Saturday April 25 2015.  I look forward to being there in person. To push the case of what I believe are compelling reasons why you should research Sefton Resources. Soon to be renamed. More of which at the Master Investor show.

    So with out further adieu. Let’s get down to business. We’ve managed to twist the arm of one of the most influential investing gurus in world finance. Jim Mellon. Or as I like to sycophantically call him ‘Mr Mellon’ One has to give respect to a Sefton share-holder. Especially Jim who has helped UK Share-holders no end.   We’ve got free tickets for the show and there’s a discount code. BMD2015  Use the code. CLICK HERE to get your free tickets. Repeat FREE TICKETS

    Click Here to chat for free!
    Master Investor 2015. FREE TICKETS!

    It’s set to be a fantastic show with big names headlining. Jim Mellon, Nigel Farage, Evil Knievil, Zak Mir (Cat), James Ferguson, Merryn Somerset Webb. There are two British hero’s and I mean real hero’s attending. Sir Steve Redgrave and a man who epitomises suffering and courage in the same breath Mr Simon Weston OBE. Brings tears to my eyes just thinking about this chap.

    There’s approx. 100 or so Companies attending and presenting. CEOs and Directors will be in abundance and unable to dodge your questions. Get down there and have a super day.  Who knows I may even buy you all a coffee.


    Viva

    Dan

  • GKP/STERLING.Investment white paper from The Economist.

    Provincial control of Iraq as of January 2007 ...
    Iraqi areas under control 2007

    Contact us | Login
    Home :: White paper
    Iraq Through Investors’ Eyes: Perspectives on risks and rewards
    Against a backdrop of difficult political and economic transitions, Iraq is once again opening its doors to foreign business. Decades of war, sanctions and hardship have left the country with a devastated infrastructure, and the government is looking to foreign investment and expertise in its bid to rebuild and expand.

    One legacy of the long years of Iraq’s isolation is that information, beyond news journalism, is sparse. Companies wishing to consider investment in Iraq often do not have sufficient information required to make informed decisions. This white paper goes some way towards filling that gap by highlighting the current experiences, hopes and concerns that companies have regarding the business environment in Iraq. It is based on a programme of desk research, a survey of 367 senior executives, and 13 in-depth interviews with business executives, diplomats and investment experts. This research focuses on companies’ perception of doing business in Iraq, and includes the views of companies currently operating in the country, those that plan to invest and those not considering entry into the Iraqi market.

    The main findings of the research are highlighted below.

    • Investor opinion about Iraq is divided…: Although 49% of respondents judge tha“the ongoing violence means doing business in Iraq will remain too risky for some time”, one-third see Iraq as “a country with significant opportunities for those who are willing to accept risks in the short term” and 28% as “a fledgling democracy with a long-term political and economic future.”
    • …but improving: Just over half – 51% – said their perceptions of Iraq as a place to do business had improved in the past two years, compared with 12% who said it had got worse.
    • Construction is seen as the most promising sector after oil and gas: 46% of investors see construction and real estate as the country’s single most promising non-hydrocarbons sector, followed by chemicals (25%). Consumer goods tie with healthcare and pharmaceuticals for third place (both 22%), followed by agriculture and agribusiness (20%).
    • The largely untapped consumer market is seen as a significant attraction. Unsurprisingly, the most attractive aspect of Iraq, as perceived by these executives, is the country’s oil and gas resources, which are cited by 58% as one of the top three attractions (17% cite other natural resources such as phosphates). However, Iraq’s untapped consumer market is almost as big a draw, selected by 49% of those surveyed, with the chance of achieving first-mover advantage being the third most popular choice.
    • Violence, corruption and poor infrastructure are the main business risks: The top three risks are violence, (69%), corruption (45%) and shortages of infrastructure (38%). The next three are credit risk, bureaucracy, and a lack of contract protection.
    • Investors on the ground expect security to improve: Almost 70% of existing investors expect the security situation to improve over the next two years, while only 5% think it will get worse. However, 61% of those not currently considering investment expect the situation to stay the same or get worse.

    The research also yielded advice for businesses looking to enter the Iraqi market. Please click here for the full report, including survey findings, economic forecast and advice for investors.

    Interesting read.

    Daniel

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights