google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: James Parsons

  • Richard Jennings: “The Yorkshire Terminator” Tom Winnifrith Scrooge……

    Richard Jennings: “The Yorkshire Terminator” Tom Winnifrith Scrooge……

    Read this to the end there’s a real twist….

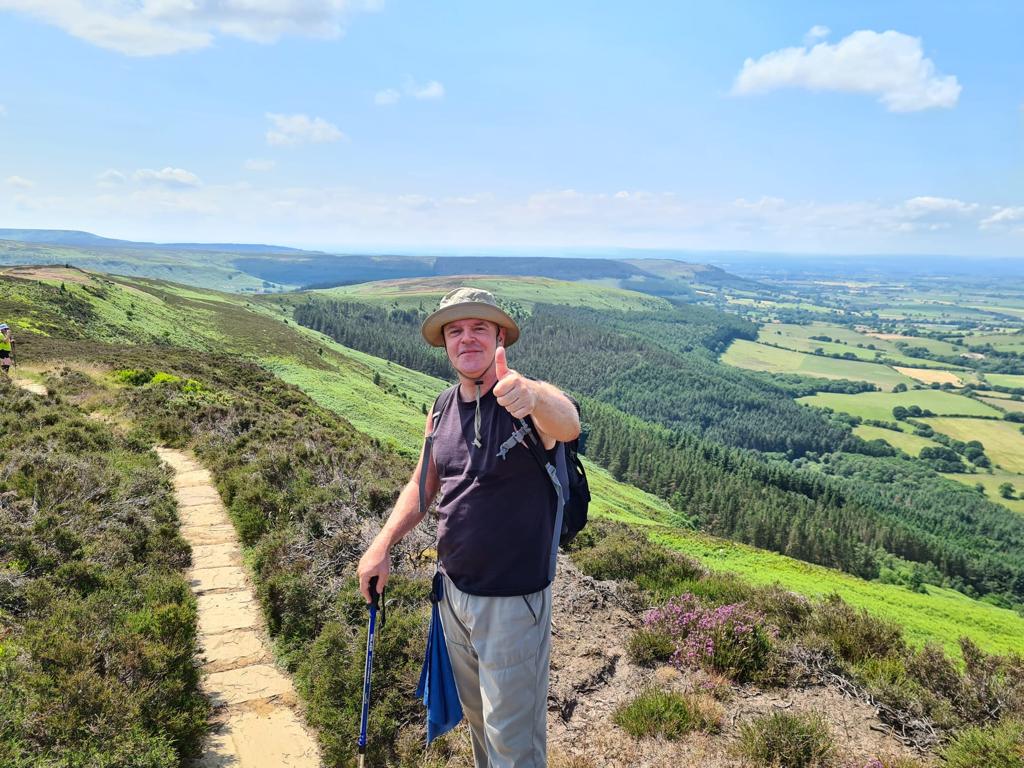
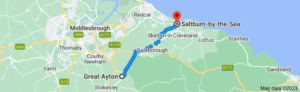
    Somehow I managed to get talked into doing the Great Ayton to Saltburn by the Sea leg of the 175K Cleveland Way hike in aid of The Yorkshire Cat Rescue Charity. I was up at 5am and drove the 116 miles to meet up with the newly named: Yorkshire Terminator aka Richard Jennings of Align Research. What a hilarious day I had on Saturday.


    Click Pic 2 Donate

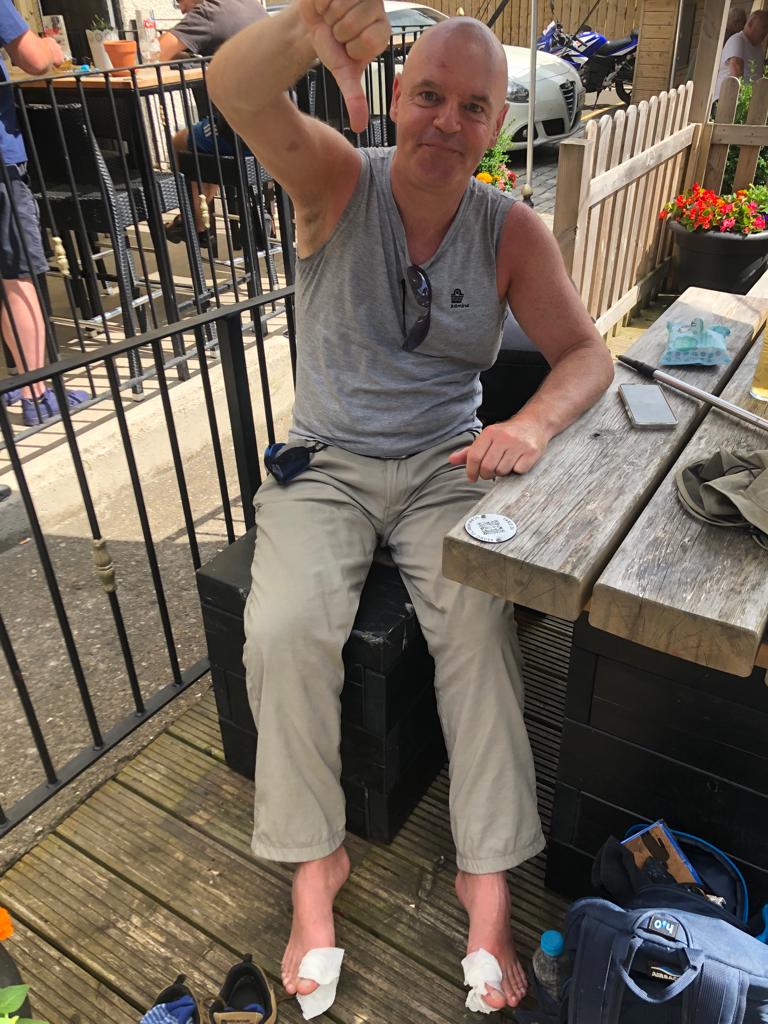
    After 5 miles I managed to talk him down off the tops and we headed downwards to The Fox Inn, located in Guisborough. Patrons of the The Fox then had to eat their meals while Mr Jennings sat there in the posh beer garden with both bloodied feet in a wash bowl full of cider vinegar, provided by a relative of mine who (actually lives close by) came to the rescue. I imagine it’s now gone down in ‘Folklore’. We cleaned them up and true to form the Terminator swigged a beer and insisted on carrying on. Complete insanity

    I’ve known RJ for a very long time. Had my own battles with him over companies but he’s always kept the door open to me. He’s one of the good guys. The tough, aggressive exterior is his protection against the lying scheming world that he navigates, but really underneath he’s a pussycat with a heart as big as a lion. He’ll be fuming reading this!!! My texts will go off the radar!

    Most traders and investors don’t know just how much Richard Jennings has done and continues to do, behind the scenes away from the City of London. He’s personally helped and funded a myriad of causes including life saving operations from South Africa to Lithuania/Albania/Greece. It’s a secret life that’s never been told….. Building and funding housing and water projects, volunteering his time, as well as charity fundraisers for his beloved ‘Cats of Greece’.

    Richard Jennings

    How he dragged himself over the Cleveland Way in agony and I mean in AGONY! Day upon day with 4 day old supperatting blisters, oozing blood, gunk, and toes swollen, was reminiscent of the Terminator. He refused to give in. Wouldn’t stop. Kept looking back and there he was dragging, himself towards me. Talk about Yorkshire Grit! LOL!!! If you ever met him I guarantee you’d not stop laughing and would walk away feeling a bit guilty. You wouldn’t have to buy the beer either….

    There are some mean corporate bastards out there. It’s amusing to see them squirm when approached for a donation. However there’s a few that have donated. What that proves is that they’re still in-touch with the real world and real people such as you and me. But most wouldn’t give you the steam from their piss. 

    Well done to Richard Jennings and a big thank you for inviting me to hike with you. It was a pleasure and I will definitely take him up on his invitation to put in 10 days work at the Greek Cat Sanctuary he tirelessly keeps a float.

    As a gesture and it’s only a ‘Protest Gesture’ donate £1 (I actually mean one pound) And here’s why. It’s £1 more than Tom Winnifrith…… The mean old bastard….

  • Balochistan The Last Great Onshore Oil, Gas & Mineral Resource Play On The Planet…. Coro Energy *BUY*

    Balochistan The Last Great Onshore Oil, Gas & Mineral Resource Play On The Planet…. Coro Energy *BUY*

    I guarantee 99% of UK O&G traders/investors have never heard of Balochistan. Indeed having just read some of the BB loons I’m changing that to 100%. That is about to change. Balochistāns’ capital is Quetta it is by land mass the largest province situated and the westernmost province of Pakistan, bordered by Iran to the west, Afghanistan on the northwest, Khyber Pakhtunkhwa and the Punjab provinces northeast and east, by Sindh province on the southeast and by the Arabian Sea on the south.

    It’s the last great onshore oil, gas and mineral resource play left on the planet. That is a fact. The province POTENTIALLY contains huge Oil, Gas and Mineral Resources. Estimates vary from 6 billion barrels of oil to 75 billion with gas in the hundreds of TCF. It’s the main reason why the Chinese have spent $40 billion constructing the Chinese Pakistan Economic Corridor known as the CPEC, as well as financing and building the port of Gwadar taking a 99 year lease to operate it. Think about that…….. Or better still google the ever shifting sands of Geo Political Alliances currently slugging it out on the world stage, seeking control of the earths resources. Make no mistake Balochistan is now coming into play and that play is huge. 

    Now lets get down to the UK Privateer Coro Energy pantomime: “O yes they are. O no they’re not in negotiations”,  currently doing the rounds on the BBs, Twitter, and Financial Forums. Are we to believe anonymous posters or do we believe sourced articles circulating in Pakistan/Balochistan as well as UK’s Upstream Online?

    Occam’s Razor: If it walks like a duck, quacks like a duck, looks like a duck, it’s a duck. There is no doubt that Coro Energy are in negotiations re O&G licences in Balochistan. At what point those negotiations are at isn’t known. What is known is that Coro must have physically been in Balochistan/Pakistan and held high level ministerial meetings as well as meetings with virtually all the main Pakistani O&G companies, if it hadn’t have happened it wouldn’t be reported in over 10 different Pakistan Newspapers/Journals… Just because it’s written in Urdu doesn’t make it any less valid. It’s happening.

    The article in Upstream writes that Coro are seeking Joint Ventures one of them is purported to be a 100Million barrel of oil with 850Bcf of gas ‘stranded asset’. If that is even half correct the financial implications of such a tie up would catapult the Coro SP into multiples of multiples. We’re talking literally billions of dollars in production. The kicker is, subject to Due Diligence, a stranded asset has already been discovered. There’s no uncertainty: the hydrocarbons have already been found

    I’m thinking out loud here. Going back to the GKP days. Gulf Keystone managed to manoeuvre themselves into Iraq/Kurdistan a region beset by a full scale ‘Shock and Awe’ USA lead war. One of the main movers in GKP was Ewen Ainsworth. We all know the story and the meteoric rise in the SP of GKP. Ainsworth is a board member at Coro Energy. Balochistan doesn’t have the instability of  full scale war, what it does have is internal disputes between State and Federal governments on the share of Mineral, Oil & Gas resources, with a very low level local insurgency that’s on its last legs. With the appointment of a new Balochistan Chief Minister who has made it clear that it’s time to develop the provinces mineral/hydrocarbon wealth, Ainsworth is probably worth his weight in gold. 

    There’s literally 1,000s of oil seeps all over the Baluchistan region. So much so the locals often come across them. This video is well worth a watch.

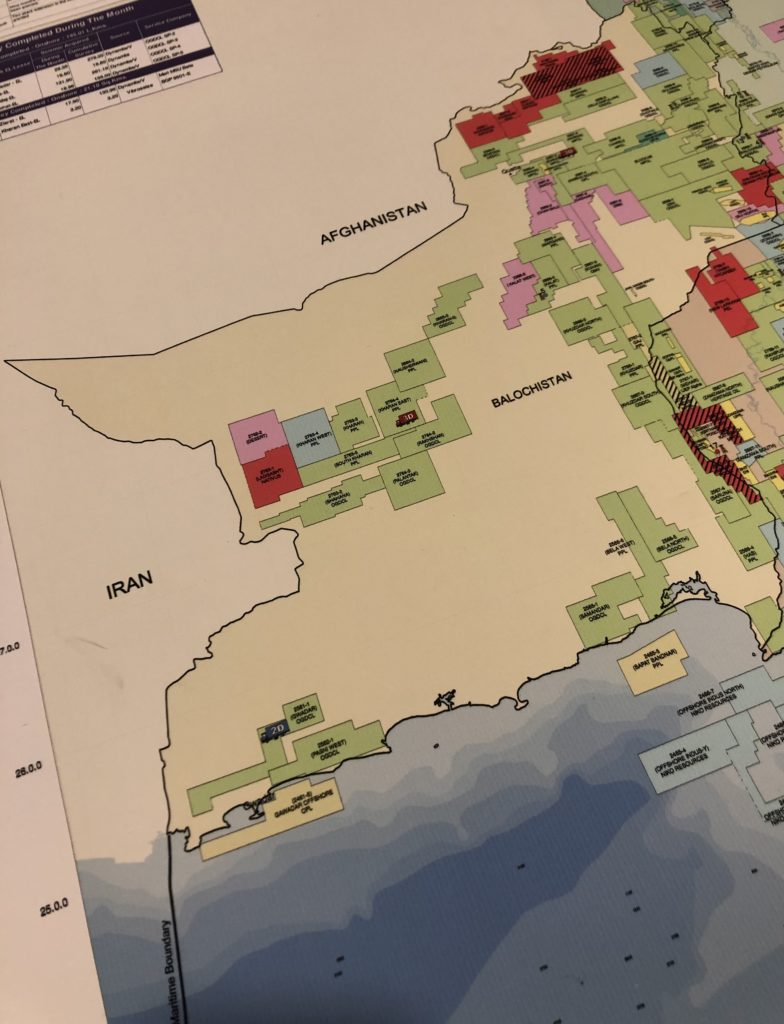
    Baluchistan Licence Blocks
    Current Balochistan Licences

    There’s nothing on the AIM, and hasn’t been for several years, that has caught investors imagination, mainly bread and butter plays. Balochistan is totally different it is huge. Whatever the true state of play of these negotiations is, any deal or JV signed has the potential to be earth shattering especially if the oil is already there…

    The driving force behind Coro is James Parsons and it is JP who has travelled, literally 100s of 1,000s of miles every year seeking deals trying to bring value back for share-holders. To go where no one else or any company would go is impressive. It takes guts. No CEO should get an easy ride but to search the globe year after year all the while being hounded by disgruntled BB howler monkies can’t be pleasant. The tenacity of JP should be applauded. This, if it comes to pass, is a company maker.

    Coro may be on the verge of entering the last great Onshore Oil, Gas & Mineral Resource play on the planet. 10% 25% 30% of any deal OR JV, if struck, would be transformational. To put it into context 1TCF of gas is 166Million BOE. At a $76 a barrel that’s over $10 Billion dollars gross. 25% of that is what? The market cap of Coro is circa $8M.

    This SP could motor upwards over the next few months especially if there’s a JV with a stranded asset. Currently trading at a third of a British penny. Short term 3p, 5p 10p isn’t out of the question. If there’s a deal on a multi billion dollar stranded oil/gas discovery we could see 50p on production. Remember GKP? Of course I’m now a shareholder.

    Any thing under a penny is an absolute steal!!!


    Viva

    Dan

  • The ‘Bushmills Vampire’ is Dead! Ascent Resources Post Corona. Buy!

    The ‘Bushmills Vampire’ is Dead! Ascent Resources Post Corona. Buy!

    It’s with a certain amount of ‘I Told You So’ that I pen this epistle….


    There’ll be no wailing and gnashing of the teeth from Ascent Resources (LON: AST) shareholders at the demise of the God awful ‘Bushmills vampire’, Colin Hutchinson, finally receiving his much deserved metaphorical stake through the heart. I just hope that the ‘Slayers’ (new team) double checked the stake had gone right through when they sprinkled holy water over the corpse. Always best to be certain when it comes to Vampire killing…. Gleaned from watching the Netflix series, Van Helsing 

    So what next for the Slayers, Ewen Ainsworth, James Parsons and Leonardo Salvadori? Well with the cancellation of Riverforts $421,943 note into a two-year zero-coupon bullet payment loan, convertible at 7.5p per share when ASTs share price exceeds 10p per share for more than 5 days, which represents a potential 100% increase from last weeks placing price of 5p now makes AST a fairly comfortable trade/investment, you can buy at 4.p ish. However, that’s not why I bought in.

    As most of you know, who follow my site and twitter, I’ve been a fierce critic of Ascent Resources. I know this company inside out and everything that’s happened to AST I’ve correctly predicted. Clive ‘carve ’em up’ Carver with his crusty sidekick, hapless Colin Hutchinson, destroyed the company. They had no regard whatsoever for their own genuine shareholders. It was never about getting the Slovenian gas asset into full production. Ascent became a ‘confetti machine’ for the likes of Darwin, Henderson Global et al.

    The new team who came in last week are some of the corporates I was talking to on behalf of the defunct shareholder action group, set up 18 months ago. Suffice it to say that the market and value of the company has somewhat changed for the worse. Shareholders gave up. And who can blame them? But hope has now been revived

    🧛‍♂️Bushmills vampire🧛‍♂️

    Ascent are basically debt free, ‘Bushmills vampire’ free, generating limited cash from their gas production in Slovenia (which is at the moment mired in a legal controversy the ‘Vampires’, not only created, but failed to address) and now have a team that can sort the mess out. Make no mistake the ‘Slayers’ have already started the process of righting the AST ship. The word is that a delegation is heading to Slovenia pronto! Expect news on this shortly.

    News has also reached ‘Yours Truly’ that the new team, pre taking control of the Company, have been in talks with several production/exploration cash strapped oilers, one being Humber Oil & Gas. You may know Humber as a partner in one of the biggest onshore O&G discovery’s in the UK: West Newton and have a stake in the soon to produce Wressle discovery. You may not know that they’re desperate for cash having paid all their West Newton drill costs. All their assets are up for sale. Including West Newton. Enter one Jon Fitzpatrick, (X Macquarie Capital) the negotiator rumoured to be working on behalf of the Lang family. At what stage any of these talks are isn’t known. But talks, there are. Now remember it’s your money not mine. That means investors/traders can buy, sell, hold, derisk or ignore at their own discretion.

    If the new team had taken over 18 months ago the SP would probably have made it back to 2/3p. Fast forward today post the consolidation and placing, we have an SP of 4p ish with a resetting of the ‘stock clock’ to 46,196,484 shares in issue. The market cap’ is sub £1.8M. Once the corona virus ‘deflating’ effect passes & the spooked herd stop burning the house down, we’ll see an inflation, subject to sorting out Slovenia & depending on what comes into Ascent, 10p/15p, maybe more, looks achievable……

    Now don’t let me have to write another ‘I told You So Epistle’ when it reaches 10p!

    Viva


    Dan

  • NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    Commenting on stocks and shares can at times feel like a character from a Hans Christian Andersen tale, one in particular, “The Emperor’s New Clothes” springs to mind every time I read or see the utter shite constantly pumped on social media by various shysters on both sides of the fence, corporate and retail.

    It doesn’t take a genius to see the metaphors from fairy tales played out on City of London listed companies by traders and corporates alike who rely on ‘greed’ to blind ‘common sense’. The target being lumpen-proletariat small time mug-investors or as I call them ‘the meat in the liquidity sandwich’. The goal is to push the ‘tall tale’ using various ‘ruses/ploys’; such as ‘behind the scenes briefings’ to certain well known P&D merchants who take a position as well as small fees with ‘warrant packages’ then go out heralding the news of riches beyond your wildest dreams….

    Which brings me on nicely to Nu-Oil & Gas (AIM: NUOG) the current nudge, nudge, wink, wink is in full flow not least on the BBs and twitter sphere. NUOG are a shell they have absolutely no value whatsoever other than there listing value. The old Board of Directors are being paid out, then kicked out, with a new team set to come in post GM ratification. The ‘new deal’ is deliberately structured in such a way that a select group of Novum placees (no more than 4/5 individual connected investors) are taking 1,000,000,000 shares of stock at a 50% discount to today’s SP, while a newly formed corporate entity holds £2,500,000 of loan notes (again at a 50% discount) to flip out as and when you ‘the meat in the liquidity sandwich’ are buttered up into believing in ‘Fairy Tales’. Mugs buying in at 0.075p are paying a 50% premium to that placing and loan note package. £3,000,000 will be flipped out into the orchestrated rise. A rise that will be predicated on a ‘hope value’.

    If by now you haven’t worked out the implications then let me spell it out. You’re starting a race with a handicap. You can never beat the corporate flippers because they have a 50% head start with access to the news flow. If today you were 20% down on your stake bought at 0.075p they would still be 30% up. It’s a race you can never win.

    ‘Weaver’ Fumagalli?

    The company holding the £2,500,000 loan notes are C4 Energy Ltd. That paper company is the brain child of one Marco Fumagalli (Continental Investment Partners, Sound Energy, Coro, Echo) and Mr James Parsons (JP) (Sound Energy, Echo energy and Coro). Both are connected at the hip as is Mr Andy Dennan proposed director NUOG, (current CFO & Director CORO, Sound Energy Holdings Italy Ltd, Alpha Growth Plc, Baron Lux LLP). I know them all, have met them, broke bread with them and talked all things O&G with them. They’re decent people in their own way. But as corporates go I wouldn’t trust them with a ‘birds nest’. They are ‘corporate bastards’. NU-OIL, at this stage of its evolution, isn’t about finding oil or gas in Cuba, Mexico or some far field of a foreign land that’s forever England, it’s about corporates playing the system using a tried and tested method to make money regardless of finding oil or not. 

    …..  ‘Weaver’ JP? …..

    All of the above have made substantial sums of varying degrees, of a reputed £200,000,000 million generated from the Sound, Echo and CORO ventures. The largest slice of the pie going to the moneyman who finances the companies: Fumagali/Continental and their various offshore exotic mechanisms.


    The ownership of C4 Energy wasn’t disclosed in the RNS of 2nd October 2019. That omission was deliberate. It was a calculated ploy to set the NUOG shareprice to spike in an attempt to replicate the fantastic gains of the early days of Echo Energy. Pump and Dumpers were briefed to scream it from the rafters. It ultimately failed. 

    Sadly all three companies Sound, Echo and Coro ‘ultimately’ bombed. Now that isn’t a critique of any wrong doing. Far from it. In the real world the best any investor can ask for is a company does what it says on the tin: i.e. They get their licence, and drill it. All 3 companies have done exactly what they said they would do. They have ran and continue to run within the rules and regulations. On the whole their biggest failure has been geological and it’s geology that determines financial success or failure for shareholders. However it’s not the geology that determines success or failure for corporates it’s selling heavily discounted stock into ascending share prices.

    The whispered Cuban licences for NUOG are a fantasy. One only needs to do what Liargas did with his ‘Fairy Tale’ and speak to the British Ambassador to Cuba who explained that O&G exploration in Cuba was 15-20 years away due to the Geo-political situation vis-a-vis the USA. Exit stage left Liargas from Cuban oil into cannabis.

    Based upon historical performance of those now taking control of NUOG if it runs true to form then it’s nothing more than a corporate carve-up pre change of control…….

    So, the questions are many. Too many for this blog. But questions will be put to those running the show and answers sought next week. Such as: Since when did an Oil & Gas CEO (JP) decide that issuing vulture finance packages and organising a select placing at ‘mates rates’ to mates, become more productive than finding oil and gas?

    Viva


    Dan


    N.B:  Kejserens nye klæder) is a short tale written by Danish author Hans Christian Andersen, about two weavers who promise an emperor a new suit of clothes that they say is invisible to those who are unfit for their positions, stupid, or incompetent – while in reality, they make no clothes at all, making everyone believe the clothes are invisible to them. When the emperor parades before his subjects in his new “clothes”, no one dares to say that they do not see any suit of clothes on him for fear that they will be seen as stupid. Finally a child cries out, “But he isn’t wearing anything at all!” The tale has been translated into over 100 languages.

  • Coro Energy: The Shambles Part 2. Placing Update!

    Coro Energy: The Shambles Part 2. Placing Update!

    Shambles Placing

    One of my favourite sayings that I often use when it comes to the fakirs and shysters that operate on both sides of the corporate fence, is “Oh what a wicked web we weave when we practice to deceive”,. The tricks and manoeuvres never cease to supply me with a barrel of laughs. CEO’s, Directors buying a pittance of stock, clarion calls, emails and text messages to the gullible, Chief Operating Officers rocking up on cowboy podcasts to deny funding, twitter DM groups infiltrated by the company PR to monitor how the deceits are being swallowed. Mass tweets of the‘veritable’ paid pumpsters such as Total Market Shite (TMS). It really is testament to the power of honesty that one man exposing the shambles of companies can have such an effect.

    I’m reminded of that well known line in the exorcist: “The Power Of Christ Compels You” Ergo, The Power Of Dan Compels You…. AIM companies just need to be honest. It’s as simple as that. Honesty is the best policy. You duck, dive and deceive then you pay the ultimate price. Loss of your share-holder base. Such is the ‘Jackanory‘ on Coro.

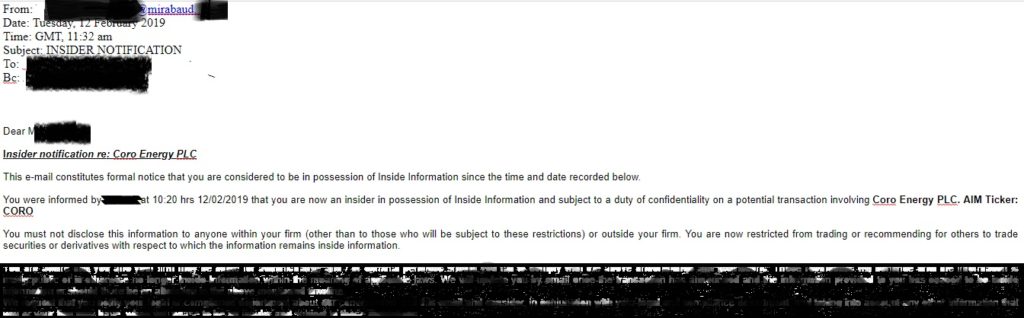
    Yesterday those that had been made inside on the Coro Energy (LON: CORO) placing were ‘cleansed’ Mirabaud, Company and Nomad emails went out ‘en masse’ and the CEO bought a handful of confetti which means that Coro have, after being exposed on here, done an Angus Energy (LON: ANGS), delayed and walked back their placing and we all know what happened there, which will happen here. Coro will try to puff up their SP then when the coast is clear they’ll drop their Placing. It’s a ticking placing bomb on the heads of those daft enough to suck up the guff. Hence why the 5 day ‘silence of the gullible’ was broken by a plethora of corporate denials, but you can, like Angus, only delay the inevitable for so long. The cash position is woeful. Their balance sheet reveals the two ‘fundamental’ truths. The shine of my good com padre, James Parsons has some what dulled and £14M has all but gone…….

    Which leads me on to another snippet of news. Just why have Coro paid circa £18,000 (Flights, Hotels, Wine & Grub not included) to attend a ‘one to one’ direct corporate investor funding shindig in Hong Kong?

    1/ Because Coro have got lots of cash?

    2/ Because Coro have spunked away £14M?

    It’s a bit like speed dating but in this case it’s speed ‘debting’. As for the Euro Bonds for Gas, any one with half a brain knows that Lombard ‘odious’ and Rob Giles are vulture financiers. This is death spiral funding. Euro Bonds for gas? Would that be laughing gas? As sure as night follows day, however much they ‘delay’ theirs a placing coming.

    It’s a Shambles. Like venereal disease, take precautions. Protection helps.

    Viva!

    Dan

  • Coro Energy £10M-£20M Placing! It’s A Shambles!

    Coro Energy £10M-£20M Placing! It’s A Shambles!

    Yesterday I had to rush to the City of Mammon on ‘confidential business’. But as ever ‘yours truly’ doesn’t miss an opportunity to get the latest juicy news, views, rumours and whispers. Which brings me on nicely to the utter clusterfook that has become Coro Energy (LON: CORO).

    Every one who invested (Myself Included) has been spun more ‘tales’ than  there are rats in the sewers of Whitechapel. I like the Board, particularly James Parsons (JP), who is one of the good guys. So I take no pleasure in tearing into & ripping the company, but some one has to stand up and read the riot act here to the Management! The whole sad, sorry adventure of Coro Energy has been structured around and loaded in favour of corporates making the money via dodgy finance packages that puts them in the driving seat, when it comes to trading out their discounted stock and warrants! It’s a fooking disgrace and James Parsons needs to step up to the plate and sort the whole, sad, sorry miss-adventure out! Corporate Gang-Banging!

    Their Indonesian strategy is woeful. Their RNS of Monday was another self inflicted injury. They totally miss-read the impact of their ‘Euro Bonds’ for Indonesian gas RNS. That’s been their form since day one of the takeover of Saffron Energy and the metamorphosis into Coro Energy. Whether it be executive management swanning around at expensive ‘black tie‘ events (with fireworks) where the previous CEO was prancing around in an evening gown, while all were ‘quaffing & scoffing’ (at the expense of the lowly Private Investor) slapping each others backs after being flown in for the ‘jolly’ on business class flights to be warmly ensconced into five star hotels, as Mike Masterman off-loaded shares on the ‘QT’, it’s been one long car crash.

    It’s apparent that the management are about as far away from their lowly PI investor base as a street busker is from a spot at the London Palladium entertaining Royalty. If what I’m hearing from yesterday proves to be correct then Mondays RNS, which was an absolute fooking shocker, a smoke & mirrors Death Spiral financing package dressed up as Euro Bonds’, funded by well known value destroyers Lombard ‘Odious’, then there’s a major kick in the balls to go with the Monday kick in the teeth RNS.

    The cash position of Coro is dire. One only has to look at their fundamentals to see that from a healthy €14M Euros as of June 2018 the cash has all but gone. $12M in cash and shares ($8M CASH) spunked on the Bula PSC, $2.95M CASH on Duyung PSC, $2.8M on General & Administration for 6 months up to June 2018 and those figures do not include current liabilities and 7 months of further cash burn, which is at least $2M and that’s being very generous on my part! The head count here is manifestly gross. The balance sheet is a travesty which is why suspicion is heightened when their Broker runs a presentation. When a companies broker organises a presentation it’s for one reason and one reason only. Placing. When a company rocks up to a VOX market shindig that too is an indication of a capital raise. It’s called a ‘roadshow’. and when two London sources tell me theirs speculation of a huge raise then you can bet your last dollar that there’s some thing going on. Glossy presentation brochures aside….

    The current whispers on Coro do not bode well for those daft enough to be listening to the horse-shite ‘screamed’ online and on financial Bulletin Boards (BBs), which have been infiltrated by paid rampers and one or two brokers who as I type are rumoured to be lining up one hell of a MASSIVE dilutionary placing! Yes sources indicate that Coro Energy are testing the ‘appetite‘ to get a huge placing away.  £10m-£20M. 

    It’s a shambles! Private Investors are being played for fools….

    Viva!

    Dan


  • Saffron Energy/Coro Energy. It’s a Bit Convoluted. But it’s a ‘Goodun!’

    Saffron Energy/Coro Energy. It’s a Bit Convoluted. But it’s a ‘Goodun!’

    There’s never a dull moment on the London Alternative Investment Market (AIM) particularly when one is trying to work out whether we’re being sold a ’pup’. You’ve got to go through all the available documents line by line, then re-read each and every document line by line. As well as using all available sources to see what you can come up with, such as what the company are involved with below the radar and how this could affect value going forward. (More on this below)

    Such is the convoluted nature of the Saffron Energy Reverse Takeover. Black-tie events apart & the machinations of Po Valley assets in,  out, suspension, relist, suspension, relist, AGM dates constantly re-jigged etc. The information saturation on this one would take its toll on the patience of a saint.

    But now all finally seems to be coming to fruition. The well-known corporate bastard, (CB) James Parsons (JP) and his team of lessor corporate bastards are now ready to and no doubt raring to go. Being classed as a ’Corporate bastard’ may ‘sound’ (No pun intended) harsh. Far from it. Again, unless you’re steeped in corporate culture you’d not realise that this is a worthy accolade, of sorts….. A corporate bastard gets the job done for his/her shareholders and the benefit of the company. Warren buffet is a corporate bastard. The head of BP is a corporate bastard. They are bringers of value. They do what is necessary regardless of short term pain for long term gain. When choosing an investment or a short-term trade always bet on the CB. Proven management bring value. Proven shysters lose value.

    All too often we as investors/traders are sold down the river by corporate shyster lifestyle companies operating on the AIM, it’s littered with them, in fact it’s like a backed-up lavatory at a Japanese POW camp, literally over-flowing. I’ve watched and followed the bowel movements of these companies and have written and exposed many of the dirty tricks that they try to pass off as good business when it’s anything other than good. So, it makes a change when a real opportunity comes along. Such as Sound Energy that hit over £1 & the great Echo bonanza that rallied to over 25p in the first few months of development.
    At the moment we all await the Saffron AGM which is nothing but a rubber stamp of the proposed terms of the RTO. Trying to cut through the corporate speak and get to the nitty-gritty of what comes out of the other end has in my opinion not been very well communicated to share-holders and those looking to trade/invest post the AGM ratification of the RTO.

    So, I’ll break it down into common parlance. Layman’s terms. I’ll also give the readers of my most wonderful blog site the heads up on what is currently going on in Indonesia. Humpty Dumpty

    Pre-the AGM there’s 200,000,000 million Saffron shares in issue. Post AGM, on the 29th March 2018, there will be a new company formed: Coro Energy (LON: CORO) with team JP at the helm.

    Shares in issue will be 716,809,735. Warrants & Options outstanding will amount to 236,817,341. The warrants will have a strike price of 6.57p, the placing shares have been sold at 4.38p per share. There will be circa $15M in cash, virtually debt free with bread & butter production. The Company’s cornerstone investor, CIP, together with Continental Investment Partners S.A.,Metano Capital S.A. and Greenberry S.A, Marco Fumagalli and James Parsons have been classed as a ‘Concert Party’ they will hold, post AGM, 22.82%. Po Valley will, unless they’ve been selling pre AGM , hold 100,000,000 (13.95%). There will also be an open offer of 45,662,100 shares to existing shareholders. There will be a plethora of ‘Lock ins’ on stock held, most will stick to the lock in. But me being me I don’t set much store by them. One lot who will be slowly drip feeding into the rises will be Po Valley. Regardless of what they say….

    Following the AGM ratification, in aggregate, the Company will own 2P (proved and probable) gas reserves of 205.10 MMscm, 2C (contingent) gas resources of 660.20 MMscm, and 2C oil resources of  2.40 MMbbls. The best way to understand the structure of the newly formed entity is the pictograph (Right).

    The asset base post AGM will be cash generative which will increase as Coro invest and rework over existing and new fields in Italy.

    Now the main direction of Coro will begin to focus on South east Asia, Indonesia and Malaysia.

    I was down as a placee until the suspension and pulled out due to the ever-changing time line of readmission and terms. Now PVO are out, which is a much better value driver for Coro. Too many CEOs aren’t good for stability. Just as too many cooks spoil the broth, too many CEOs fuck the company up. Now they’re out. That’s good news all round.

    It’s known by ‘Yours Truly’ that Coro are in advanced negotiations with several Indonesian oil & gas companies and are in talks with the Indonesian state-owned oil company PERTAMINA.  One of their new directors, Ilham Habibi, (Son of a former President of Indonesia) has direct access to the top echelons of PERTAMINA. I know this because I met Mr Habibi in Indonesia last year. (I was on Sefton business) Several of the assets I toured were up for grabs including a 10 Million scuffs a day gas producer with half a TCF resource. And a 3,000 bopd asset owned by Fosters oil. So, you can take it as read that there’s going to be multi TCF Indonesian exploration/production assets brought into Coro some time in 2018.

    Any news on big exploration gas/oil licences or producing oil/gas assets will set the share-price on fire. It’s a no-brainer that the SP will rise. The question isn’t ‘if’ it’s when. Any thing under 5p is a steal. Any one selling now will rue the day…  I’ve set a target between 12p-15p over the next 12 months. And as ever will closely follow the news and the developing story. Investors should do likewise, keep researching them. It will pay off.

    I have to ‘fess up’ that I’ve been holding/buying shares in Saffron for quite some time!   🙂

    Get ready for ‘Go’ on Coro!
    Viva!

    Dan
  • Breaking News Echo Energy Placing £15-£20 Million?

    Breaking News Echo Energy Placing £15-£20 Million?

    It’s all gone quiet on one of the hottest oil and gas plays out there.  Currently Echo Energy (AIM: ECHO) are suspended pending a big South American transaction that constitutes a reverse takeover under Rule 14 of the AIM Rules for Companies.

    Now there’s a lot of rumours flying ’round out there about just what’s going on. I can exclusively reveal that sources are intimating to me, from many different quarters, that there may be  a big ‘numbers’ CPR on the way. And I mean big……. The company ‘maybe’ raising cash, the whispers, although not confirmed, are a £15-£20 million pound book-build (Placing) underway.  Indications of a placing are many not least they’re on a ‘Roadshow’ touting their wares around the City. Another sign that something ‘financial’ is a foot… Is that a good thing? Well at this stage only time will tell.

    However as a share holder I’ll tell you this: I am concerned that this book-build may involve Vulture Financiers, come on down Primary Bid, you’ll all remember them as the hat changing Darwin Strategic, Henderson, Lombard, all one in the same. I’ve emailed Darwin head honcho Anand, sadly Anand has failed to reply. Silence of the guilty. Their possible slice of the placing pie, £4/£5 million of discounted shares will hit the market from day one. Not good news for LTHs. Darwin have fooked over many a company over long periods of time, Ascent Resources (AIM: AST) being the latest example. Once these blood-suckers get their teeth into a company, good or bad, then it’s a racing certainty that problems develop. Strong management is needed. The next thing we know Clive Carve ’em up Carver will be on the Board! That will be the Death Knell and time for me to depart, rather smart.

    As a shareholder, whispers that a whole host of bucket shop shysters may have been given a slice of the discounted placing pie, too many to name individually, don’t concern me too much, even though one of the bucket shops is ‘rumoured’ to be under investigation by The FCA. The whisper is that the Placing is at a 15%-20% discount. That means that there will be an overhang when ECHO return. I am hoping that the more ‘sticky’ Continental Investment Partners are involved… That would be a good thing.

    Of course company’s need cash to progress, that’s a self-evident truth for a new company. Particularly one with a superb management team like Echo. However, when companies turn to Vulture Financiers the next thing we know they’re on all the pump and dump forums, such as LSE, Podcasts & Vox Markets, whose share-holder base has two well-known Darwin Strategic traders. Once you run with the P&Ders you lose credibility with LTH’s.

    I’d also urge investors to listen to the ‘right’ people such as Malcy Graham Wood, Probably one of the best oil & gas analysts out there. I did say to Mr J Parsons quite some time ago that it would be a good move to stick Malcy on the Board…. Rumour is that some of these assets may have been introduced by him. This guy knows his stuff. Although I don’t  ‘Have it’ with Malcy, he is respected by me as a professional. Knows his O&G. I believe there’s a presentation this very evening. Anyone there should ‘grill’ the lot of them.

    Aligning your interests with share holders is the key to success. That’s a fact. AIM is littered with companies who only use retail investors as the financial meat in their sandwich. Just what has made them turn to the Vultures isn’t known. It could just be a quick financial fix trying to get Echo back out of suspension, asap. If it’s that then say so. Of course they’ll come out and explain. If it’s a one-off, then fine, but if a pattern starts to develop then  problems of the ‘Ascent’ kind will rear their head. That’s a fact! So let’s hope the management take it on ‘board‘ their Board!

    Echo has strong support from LTH’s and good, honest, genuine retail punters. They have a huge following and everyone, including the Board, wants it to hit £1. Knowing those in control, I believe that this is quite possible, any success with the drill bit will rocket their SP. There are a few quality O&G plays on the London AIM . Echo are one of a handful of companies with proven value driven corporates. Let’s keep it like that. Stay away from the darkside…. Otherwise Danksy is Offski.

    Now I know that this company actually listens to its share holders. As evidenced by their communications and the fact they quickly ditched their previous Broker who was selling while telling people to buy. That’s a good sign… So if you’re reading this, a solution to the Primary Bid/Darwin problem is thus: Whatever slice of the pie these fookers take lock them in for 6-12 months.

    Hey but who am I?

    I tell it as it is. Good or bad. Which is why you’re reading this!


    Viva!


    Daniel


google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights