I’m not as prolific blogging these days, lot of reasons, (been traveling mucho these days) but mainly age, and experience has taught me that the market, from top to bottom, is about as twisted as a helter skelter. Most CEOs, Directors, Market Makers, Brokers, PR outfits, Big hitter traders, run a double game, concealing their agenda. Mammon reigns supreme in the City of London. Arrogance, greed, bare faced lying, fraud, corruption the list goes on. There are some good people amongst the above but they are the exception to the rule. By far the most honest are the small time investors who are just trying to make a few quid….
Most don’t know that I’m currently back and forth to Asia ‘chasing the rainbow’ (on the corporate side.) But that’s another story for another time that will eventually be told….. I digress. Any way onwards and upwards.
It’s not every day that a genuine tiddler in the mining sector pops up that’s actually worth a punt. Most are shite, lifestyle companies run for the benefit of their BOD. One only has to look at the utter disasters that are Redrock, Sunrise and, the God awful Kavango Resources, to name but three. There are literally dozens upon dozens of these corporate shysters ‘mining’ the City of London and gullible UK investors/traders.
It’s all about research and if you do what I do and actually take a deep dive into them you wouldn’t now be sitting on a loss on the 3 bags of shite listed above. My advice to anyone daft enough to have been suckered into these life style companies and any others, is to exit immediately and take a look at
This kind of ‘tie in and buy in’ is worth many multiples of their current SP. 0.80p. The Aterian board are still fresh, clean and uncorrupted. I now a story about the ATN Chairman Charles Bray, of course I can never discuss it, but it’s that tidbit of information, that points to Bray being one of the good guys. Plus he’s got skin in the game. A lot of skin, just under 10%……
The Market Cap’ is buttons. At the current SP it’s a no brainer. I can’t lose. It’s got to be a multiple rise on news. It couldn’t and wouldn’t stay static. Common sense dictates that there’d be a buying frenzy… Surely the Company should now, at the very least, either confirm or deny that negotiations are in play? In-order to get that confirmation I’ve deliberately named 3 of the Majors.
So there you have it. Take a punt or don’t. You now know as much as me!
It’s looking decidedly grimmer and grimmer as each week passes on ‘Uber dog & ‘Uber’ ramped Chesterfield Resources (LON: CHF) This outfit are without doubt the biggest crock of shit currently on the small cap mining resources sector. They’re a mining copper play with bits of paper laying claim to ‘Copper Riches’ beyond your wildest dreams, in Cyprus.
Having spoken to ‘The Secret Nomad’ on all things standard listed and gone through every RNS and company presentation/s I can now tell you exactly what’s in store for any mug punter who falls for the ‘Greeks Bearing Gifts’ spiel currently being vomited out by this POS and their paid promoters.
Chesterfield listed on the 29th August 2017 raising £1.3M at 5p. Two months later the company was suspended, apparently a reverse takeover, so with a new prospectus they announced on 28th June 2018 that they’d raised £2M at 7.5p and had also issued 6,666,667 shares (£500K) of stock to HKP Exploration Ltd to take them over for the rights to 7 permits. HK Exploration paid nominal sums for the permits which were now incorporated into the new improved POS Chesterfield.
In September 2018 they released their Interim Results up to 30th June 2018. Where the cash balance was circa £900K. Now here’s the conundrum. On 28th June they confirmed the relisting and £2M raise. Their Interim’s are up to 30th June 2018 yet CHF state they have £900K. Have CHF ‘Jazz-funked’ away £1.1M in the space of 2 days of being relisted? If so then Whilst in suspension CHF must have been bust. The licences were paid for in shares. What was the £1.1M spent on, in two days, other than debts? It gets worse. If the above is correct then £2.4M in total has been spent over 10 months from listing to re-listing. Which leaves CHF £900K as of June end 2018, 8 months ago. The Company needs to clarify their cash position pronto!
If the £1.1M of the £2M has gone then they were burning cash at circa £240K per month up to June 30th 2018. How much cash has CHF got left? Well, on the cash burn up to June 2018 they again would be? Bust.
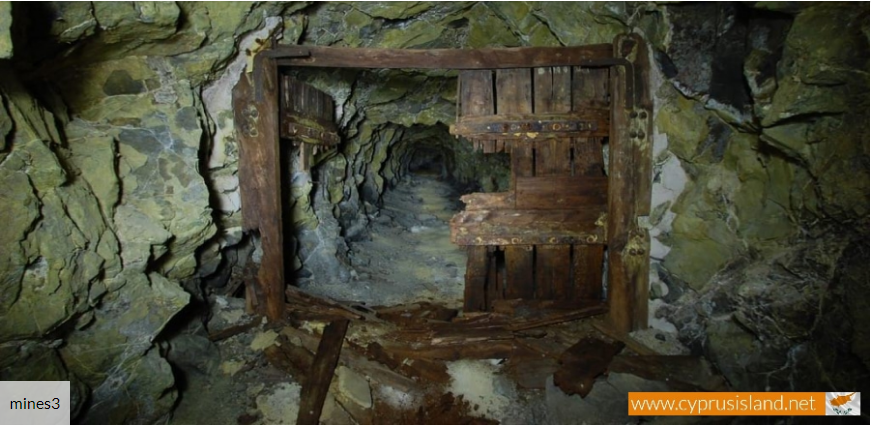
Invest your money here! One of hundreds of abandoned mines on Cyprus…
But let’s be generous because I’m a good guy. Lets say they decreased their cash-burn by 66% for the 8 months up to today. That means the Company have circa £100K in cash. And believe me ‘Uncle Dan’ is being extremely generous in cutting their cash-burn down by 66% per month. CHF are running on vapours. Mining, by it’s very nature, is hugely expensive. It’s hundreds of millions of pounds of capital expenditure (Capex) before a mine can be opened.
But here’s the ‘wibble in the wobble’. Being a standard listed company they can only issue 20% of their shares in actual issue in any one 12 month period, unless of course they come up with another ‘Acquisition’ and suspend and re-admit yet again….. If they go for a placing, 20% of shares are circa 12M shares. At 2p that’s one months cash-burn. At 3p that’s 6 weeks cash-burn. Or on the “generous good guy” figures of £100K per month 10 weeks or 15 weeks. Of course they’ll have to wait about 90 days before they issue.. There’s a very real possibility that CHF may well have to submit another prospectus and suspend. As Yoda would put it, ‘Vapours, almost certainly running them on’.
Cyprus was famous in antiquity for its copper resources. In fact the very word copper is derived from the Greek name for the island, Kupros. Cypriots first worked copper in the fourth millennium B.C., making tools from copper, which at that time could still be found on the surface. The discovery of rich copper-bearing ores on the north slope of the Troodos Mountains led to the mining of Cyprus’ mineral resources in the Bronze Age at sites such as Ambelikou-Aletri.
Toxic Abandoned Mine Cyprus. 1 of 100s…
Of course today after 3,000 years of mining one may want to ask exactly what’s left? Other than a few small time privateers, since 1970 the Cypriot mining industry has been in recession. Copper produced used to come from low grade dumps. That’s to say; processing of waste material from previous mining operations such as the Skouriotissa mine owned by Hellenic Copper Mines Ltd. Who’re a small scale producing copper mining company on Cyprus. In fact, Hellenic Copper Mines Ltd. are the one and only mining company on the island of Cyprus. Why is that? Answer. Because they have all the mining waste from their previous operations. In other words there’s fook all left. The only copper being produced in Cyprus comes from waste. Slag heaps. If you’d like to buy a permit and try your hand at finding the mother-lode of copper, gold or any other metal on Cyprus the cost is circa £8K per permit.
If you believe that defunct mines that cost a minimum of $200M dollops to clean up and get into production is good business then you need to send me all your money because I’m opening a gold mine at the back of a pawn shop in Didsbury….
Now we’ve all heard of that pithy saying “Beware of Greeks bearing gifts”. So here are the facts
Most mines on either side of the ‘Green Line’ (Google it) are of special scientific interest to the worlds archaeologists. That’s the Cypriot, copper industry in its entirety. There are 100’s of toxic abandoned mines. A full producing mine costs hundreds of millions of dollars to get into production. This lot have zippo cash and are about as far away from producing copper as I am from receiving a Royal Pardon and an invitation to become a ‘Lord’ of the realm. It’s a fantasy ‘Paper Mine’. Nothing more nothing less. Of course the ‘howler monkies’ will scream and scream and scream some more as reality bites.
I’ve seen it before. It’s an old worn ‘recipe’. Pick an area that’s had a history, get some spurious exploratory permits, throw in a few RNS’s, add a dash of diamond drill sampling, over-promote, give a few quid with an expenses paid jaunt to a couple of P&Ders, a pinch of ‘Total Market Shite‘, light the blue touch paper, sit back and laugh as you Mine the City of London via Mug punters.
Having spoken to ‘sources’ on what’s likely to be going on within this POS, I can only say commiserations if you’ve been suckered in by the blatant P&Ding that’s got you to this point in your trading/investing methodology where you greedily suck up more shite than a portaloo, suction cleaning vacuum.
This so called mining copper riches story is very similar to another one. In fact you could say it’s right out of the mining play-book for ‘Suckers‘. For those of us who recall the ‘Greek Tragedy’ that was Emed Mining. I’ll tell you this. It didn’t end well… Emed Mining were, (note the word “Were) a copper mining riches beyond your wildest dreams with licences in? Yes you’ve guessed it, £8 grand a ‘pop’ permit, Cyprus…
It’s Suspension, Placing or Both. Shell value 0.60p
Time I updated on Blockchains UK contender for “Hair puller out of the Year”. I went to the Pizza Blockchain shindig on Wednesday, just gone. Those that attended now know much more than those that didn’t on why On-Line Blockchain (LON: OBC) do not update on what they are working on & why it’s practically impossible to get hints or tidbits of news out of those running the company.
This is not an oil & gas play or a resource play. #OBC is a Tech’ Blockchain play as such it’s a roller-coaster. It isn’t subject to the vagaries and whims of P&Ders and day traders who currently run true to form and are howling and screaming utter bolloxs. It’s where you get on and where you get off that counts Not what you shriek into the barren wastes of London South East or social media. Bitcoin goes down, then oil & gas traders sell. That’s why O&G traders should not get involved until they ‘Gem up’ on the Blockchain space. Bitcoin isn’t Blockchain just as every single crypto coin isn’t Blockchain. Cryptos are run on a Blockchain. If you don’t know the difference then you need to get up to speed.
As it stands OBC started at 13p, it’s had many spikes in SP, at one point hitting £1.86p. It currently sits at 63p no doubt whatsoever that those spikes in SP will continually repeat as the company progress their business, and progress it they are. And no doubt the Howler Monkeys will continue to scream. The problem we have is that the Board are NOT your usual shyster lifestylers who update on the licking of an envelope or the tieing of a shoelace. The Board are very chummy with the top echelons of The FCA & the Aim Team. ADVFN compliance regularly liaise with both regulators.
This is what we know about #OBC and the people who run the Company. They’re fully cashed up, no debt, proven management in their space. They don’t leak info. They, through 20 years of business at ADVFN, (the worlds biggest financial portal) work with over 70 exchanges/platforms. That fact in itself tells us that it is nailed on that they’re talking to exchanges/platforms on Blockchain developments for exchange platforms. We know that they’ve had or are still having discussions with the Gibraltar stock exchange and we suspect plenty of others. I confirmed a recent meeting OBC had at the Reform Club (London) with the head of the GSX via a simple ‘phone call which ‘blagged’ this information from the Reform club reception. Easy when you know how.
Those at the presentation know that there will only be news on signed off deals. No news on discussions. If there’s any signed deal with any exchange then the OBC SP will go ‘stratospheric’. We know they’ve recently started a UK company called Awesome Animation (Company number 11166820). We know the Plus1coin hash rate has over the last 10 days risen to an all time high. We know that Plus1coin has been rolled out in the USA on InvestorsHub and we know that there will be other coins rolled out. We know that they’ve been developing Plus1coin as a validation token and we know that other media organisations are being-approached re’ the Plus1 validation token. We also know that they’ve opened an office some-where in London. The address of which is a highly guarded secret. It’s a secret for security reasons. Those that understand the Blockchain space will need no education as to why. It’s where their test mining and Blockchain applications operation are being developed. We know that William Louden is a big hitter and his appointment to the board isn’t ‘eye candy’. Louden is an internet genius. OBC will probably hit £2,£3,£5 or even £10 some where along the line. If you don’t think it will then sell up and move on or trade on. The choice is yours. Screaming blue murder isn’t going to force an RNS with the likes of Clem Chambers, Mike Hodges, Bill Louden and OBC. If you can’t take the pressure because you can’t work it out. Then move out! Simple. In this company we have genuine businessmen running it for the benefit of their shareholders and the company. It’s a rollercoaster. Get used to it!
Bearing in mind all we know or suspect, it doesn’t take a ‘genius’ to see that when or if news drops then it’s going to be good news. We can predict RNS’s such as their interim’s, accounts etc. With a degree of certainty. But we can only guesstimate when RNS’s on MOU’s, JVs Coins, Mining or Blockchain applications are rolled out. In real business, as opposed to the bullshit of the world of the P&Ders and Day traders, business deals constantly change during negotiations, ergo expected news time lines change.
You have to be in it to win it. If you don’t understand how real business works then sell up and move on. Leave Blockchain to those who know the space and are prepared to take the risk/reward involved.
When news comes it will be ‘real news’ as opposed to the bullshit that pervades the O&G/Mining space. And yes I’ve made good money in #OBC and yes I will continue to make more ‘Good money’. Research is key.
There’s a lot of rumours currently flying around on news from On-Line Blockchain PLC. Now here’s the thing we all know that there’s news long overdue on many fronts, but this week could be the start of news-flow. Now I’ll tell you why I believe that news is about to start to drop.
I’ve been asked if I’d like to attend a free Blockchain and pizza get together with the Great Clem Chambers. My sources and my gut feeling tell me that the start up of the pipeline of news from OBC is very close. Of course I will be attending the get together and urge others to do the same.
Keep your eyes on them any news will be good news. And good news always pushes their SP much higher. Dependent on what that news is, (which we just don’t know) but we do know that it will be very good whatever it is.
Remember they’ve been quietly working away below the radar while at the same time their Plus1Coin has risen in value by over 1,000%. We also know/suspect that they’re working on a Mining Operation, as well as developing Blockchain applications.
Investors & Traders in Blockchain are all sat awaiting news on On-Line Blockchain PLC (LON: OBC). The only genuine London listed blockchain play with proven management who not only have integrity but also have a hell of a lot of ‘Skin in the game’.
I first broke the news when the shares were trading for 13p…. OBC has hit close to £2 and currently rests at 95p. The recent cash & grab £1M placing certainly took away the momentum. Although that was the first placing for over 15 years.
It’s been a rollercoaster thus far as we pull our hair out (those that have hair) trying to fathom the Chambers/Hodges strategy. News has been thin on the ground. There’s a reason for that. Blockchain is a game changer and the ‘No Coiners’, such as the Banks and financial institutions are terrified of all things blockchain. You wont find the OBC guys ramping to fook or promoting to death, specifically because the Nomad and the London Stock Exchange are watching them like a hawk and this isn’t the way CEO’s with business acumen and integrity ‘Do Business’. Only shyster CEO’s operate on twitter/social media to massively over-promote suckering in the gullible pre there begging bowl twice/thrice yearly placings.
OBC are quietly going about their business and it is this I now turn too. News and whispers a plenty. OBC have been talking to the Gibraltar Stock Exchange (GSX) this has been confirmed to me by my sources. OBC ‘maybe’ meeting them again over the next month or so via a meeting in Gibraltar where Chambers is pencilled in to be one of the main speaker at a Gib’ blockchain conference in Q1, at what stage these talks are isn’t known. Indeed they could be dead or they could be very alive. Remember ADVFN deal with over 40 exchanges, so it’s pretty nailed on that some of these are being targeted. As well as gaming exchanges.
Big news on the way re’ OBC and a big international name/company coming in. Whispers have reached ‘Yours Truly’ that there’s a big name and I mean Big Name in discussions with OBC and their Nomad who would obviously be going through the usual AIM due diligence procedures on the name/Company. I emailed their Nomad, Roland Cornish regarding this and received no reply.. But it is 100% that news is on the way. Now from what I can glean an individual who has connections to Bill Gates. I shit you not! Was in the ADVFN office two weeks ago. Make of that what you want. I’ve also heard that ClemC was in the Facebook offices having a meeting. Whether this was ADVFN or OBC business isn’t known. But whatever it was for remember there’s a crossover.
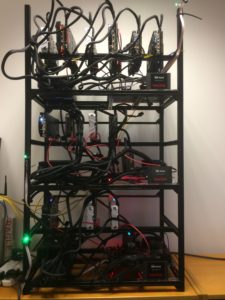
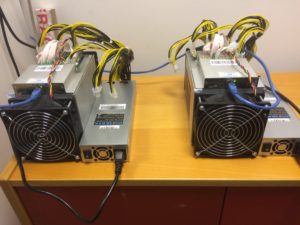
These are about $20K in value. Can mine $600 per day….
Generate circa £150-£250 per day.
The roll-out of Plus1Coin in the UK, which has risen in value by 1,000%, could be rolled out in the USA. That’s good news for those who have some of the coins and good news for those who are mining the Plus1Coin. Which brings me on nicely to crypto mining.
I was in the advfn office and noticed that there’s an awful lot of mining rigs of various descriptions, set up. (See Pics). So being the cheeky fooker I am I sneakily took a few pics! Which will no doubt get me barred from ADVFN…. I suspect that these rigs are a joint testing exercise between both companies. The large rigs use about £20 of electricity and generates £150-£250 per day in crypto cash. Not bad. I surmise that these mining rigs could be the precursor to OBC/ADVFN setting up an industrial scale mining operation over the coming months. 50 of these rigs would generate plenty of cash, do the maths…. I’d expect news on this pretty soon…..
There’s a lot going on behind the scenes and below the radar at On-Line Blockchain. Target £5 is easily achievable once the news starts to roll out. And make no mistake. Big news is on the way it’s a question of time. 3 months, 6 months 12 months etc. We just have to force out the RNS’s!
Once again I’m laughing into my porridge this morning. It really does take the biscuit when ‘comrade’ Tom Winnifrith comes out with such utter shite on the complete and total failure that is Red Rock Resources (LON: RRR). You can read the twisting & turning by clicking HERE But it is good to see that Tom’s ‘lieabetes’ oops sorry diabetes is now under control and he’s back running to form. People often ask me why I deal with TW. The answer to that is this; Winnifrith, regardless of what you think of him and my thoughts on him are widely known, can when he occasionally purges the spite and poison that runs through his diabetic veins, write excellent articles when he so chooses. Sadly he suffers from subjective, selective, memory recall which all too often surfaces. He who pays the piper plays the tune. Come on down Lenigas, Lofgran, Bell and many, many more.
RRR L Fraud = LifeStyle Company
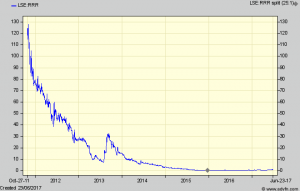
So when is a Death Spiral Finance agreement not a Death Spiral Tom? Apparently it’s when your bestest buddy whose been paying you tens of thousands of pounds over many years to promote his POS companys signs up for one. Red Rock have a Death Spiral finance with YA Global, commonly known as Yorkville. The euphemisms are aplenty in the shareProphets article, Alternative financing, Smart deal, This is not a death spiral, Cash to cash loan etc. etc. etc. Let’s forget the 15yrs of total failure and the misery that share-holders have endured since day one of the reign of Andrew Bell, known by investors and the City as #CalamityBell, the raising of many tens of millions of pounds, the flip flopping of the ‘story’ and the cold hard fact that this mining company has never opened a mine in 15 years! It is a lifestyle company to put it mildly.
CalamityBell Challenged to Debate!
Andrew Bell is a corporate crook if he wishes to challenge my statement then he is invited to do so through the Royal Courts of Justice, if he wants to debate with me face to face his disgraceful 15yr non-performance on TipTv or The FinancialFox then I will oblige.
Bell will use and say any and anything to negate the TOTAL, SHOCKING, DISGRACEFUL performance of Red Rock Resources. Even blaming President Obama… Ffs is it me or does anyone out there actually believe the utter cock that Bellend tweets and ramps? One only has to go back to their Initial Public Offering (IPO) to see just how many times the ‘Jackanory’ has changed here! Each and every ‘Jackanory’ used to ramp the fook out of the RRR share-price, each and every time placings aplenty and massive dilution and ultimately a resetting of the stock clock via CONsolidations. Oh and lets not forget the corporate largesse, just how much cash, stock and options has ‘Bellend’ had out of this company since day one? I seem to recall he awarded himself ‘performance’ options. Just quite what performance they relate to is a mystery…. Bit like the Bermuda Triangle. He’s made millions upon millions. Share-holders have been wiped out more times than I’ve had hot dinners. If RRR was a race-horse it would have been shot years ago to save on vet fees.
So for Winnifrith to be banging the drum that a Company that’s just taken on a $4,400,000 debt with a 13% coupon that is secured against the company assets, its shares and finances from known Vulture Financiers isn’t a Death Spiral shows the sheer bloody hypocrisy and the subjective paid for thinking that clouds the flawed genius that can be TW. There is one ‘constant’ when it comes to CalamityBell; Placings. Bell will run to form very soon and PLACE yet again, Rinse, Repeat. Ask yourselves this; What would a genuine Independent Financial Advisor (IFA) advise? Therein lies the truth…. Sell up and get the fook out.
FinnAust Mining (LON: FAM) is a dual AIM and Frankfurt Stock Exchange listed resources exploration company which currently has a number of prospective licences in Greenland, Austria and Finland. The company came to the London market in December 2013 following the £7.7 million reverse takeover of Centurion Resources. This brought with it a major shareholder in the form of ASX-listed nickel producer Western Areas, who we will discuss in more detail later, and which put up £1.8 million into the £3.4 million IPO placing at a price of 5p per share.
Having an initial focus on a range of early stage copper assets, shares in FinnAust fell steadily over the two years following its IPO as a result of a 35% fall in the price of the metal. However, a move into titanium in December 2015, driven by new Managing Director Rod McIllree, caught the market’s attention and breathed a new lease of life into the shares, which are amongst the best performing on the whole of AIM in the year to date.
FinnAust’s current assets are as follows:
Finland – owns 100% of a portfolio of copper, zinc and nickel projects; the Hammaslahti CopperGold-Zinc Project, the Outokumpu Copper Project and the Kelkka Nickel Project. In January this year additional licences were granted over the project areas, increasing the land area by c.50%. While these are not the current area of focus FinnAust still sees value in the assets.
Austria – an 80% interest in the previously producing Mitterberg Copper Project in Salzburg. This is largely a legacy asset from the reverse takeover of Centurion Resources and FinnAust is currently looking at realising its value.
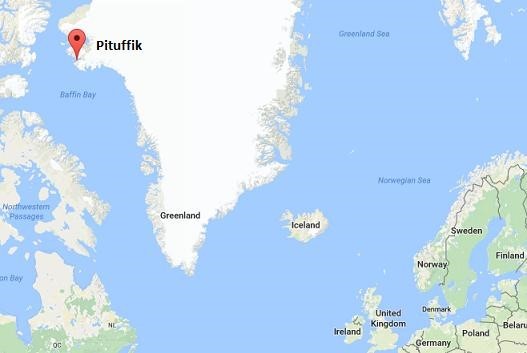
Greenland – the current focus of the company’s activities is the Pituffik Titanium Project in Greenland. FinnAust has an interest in the asset via its 60.37% stake in Bluejay Mining Limited, the 100% owner of the project, which was acquired in March this year.
The Greenland assets were added to in September this year when FinnAust agreed to acquire 100% of Avannaa Exploration from Capricorn Oil, a subsidiary of Cairn Energy, for £500,000 in new FinnAust shares. The two most noteworthy projects are the Disko-Nuussuaq nickel-copper-platinum project and the Kangerluarsuk SedEx lead-zinc-silver project. Located in the south-west of the country the assets had over $50 million spent on them prior to being bought by Cairn and are believed to have high-tonnage and high-grade base metal potential. The deal is conditional upon approval from the Greenland government and expected to be completed within the next few weeks.
Pituffik
Touted as a potentially world class asset, the Pituffik Titanium Project is located on the Steensby
Land peninsular in the north-west of Greenland, 83km south of the regional settlement Qaanaaq (pop. 656) and part of the Thule black sand province. Here, the coastline contains areas of high concentrations of the mineral ilmenite (the most commercially important source of titanium), on active and uplifted beach zones, which are the focus of Bluejay Mining. Bluejay holds exploration licences over 150km² of onshore ground and shallow marine environments at the project.
The acquisition price (for 60.37% of Bluejay remember) was a maximum of £905,607, paid for via the issue of 164,655,885 new shares in FinnAust at a price of 0.55p per share. Of these, 40,755,885 shares are deferred (see more below) and there is a four year option to acquire the remaining 39.63% stake (another point discussed in more detail later). The Bluejay vendors include, interestingly, FinnAust’s Managing Director Rod McIllree and Non-Executive Greg Kuenzel (of Noricum Gold fame). Along with the acquisition, a placing of 10 million new shares at a price of 2p each raised just £200,000 with major shareholder Western Areas putting in half of this.
As you can infer from the picture below, Pituffik is not somewhere you would want to go for your summer holidays, being located in the Arctic Circle and experiencing harsh climatic conditions. Despite the cold, Greenland has actually been warming up, with climatic changes causing its ice sheet to retreat and exposing new areas for minerals exploration and exploitation.
While originally being discovered in 1915 Pituffik remains an early stage exploration asset.
It caught FinnAust’s attention due to having high grade material and exploitation potential. Historic fieldwork by Bluejay, the Geological Survey of Greenland & Denmark and others has highlighted the presence of a very large and, according to the company, “unusually pure” titanium deposit at Pituffik. Active beaches in the region have demonstrated grades of up to 68% ilmenite, averaging between 38-40%, with the more expansive uplifted beaches averaging around 17%. Upon acquisition FinnAust’s CEO McIIlree gushed that Pituffik has the potential to “become one of the highest grade in situ deposit of ilmenite anywhere in the world.”
Key Areas.
There are two key areas which have been identified for further work at the project, Moriusaq and Interlak, located along an 80km coastline in environments including raised beaches, active beaches and drowned (underwater) beaches. Moriusaq is the most advanced area and has returned the highest ilmenite grades to date,with grades in some areas estimated to be in excess of 85% ilmenite. Interlak offers the largest volume of heavy mineral sands, with grade upside potential, with grades in some areas estimated to be in excess of 70% ilmenite. The plan is to advance Moriusaq first given that its marine environment could provide an opportunity to employ dredging (a simple and low cost method) to exploit the sands.
Latest developments
Following the initial agreement to buy the stake in Bluejay in December 2015 FinnAust quickly got its plans together for developing the asset, with the strategy being to capitalise on Pituffik’s near term production potential. In February, results from a bathymetry (underwater) and seismic profiling survey completed in 2015, along with a sea floor sampling programme, suggested that the shallow marine environment hosts very large volumes of potentially high grade titanium, with the results multiplying the amount of known titanium mineralisation significantly.
Subsequently, various technical consultants were hired in order to complete fieldwork over the course of 2016, including an initial resource calculation for the Moriusaq target and surrounds. With the nights (and days) getting colder, the work programme was finished in September, with more than 500 drill holes having been completed along with trenching and sampling across the project area. Results confirmed that the two target areas will remain the key focus. An Environmental Impact Assessment has been completed and a Social Impact Assessment is underway.
FinnAust is now in a position where it expects to publish a JORC compliant resource by the end of 2016, ahead of commencing an initial 30,000 tonne proof-of-concept bulk sampling programme in 2017, followed by the application for an exploitation licence in Q1 2017.
So far so good but valuation is materially out of kilter with the progression stage
To give FinnAust management credit the company has, over the past ten months or so, provided a text book example of how to promote s story, and they have done so with a relatively limited freefloat. A plethora of technically worded RNS’s with copious amounts of “pleasing” and “exciteds” peppered throughout these releases in relation to the Pituffik asset has pushed the stock price up nearly 15 fold since the beginning of the year. The shares have risen from 0.55p just prior to the Bluejay acquisition announcement to the current 7.5p, making FinnAust one of the best performing shares on the whole of the London markets in the year to date.
All well and good but we have a number of issues and questions.
Difficulties mining in Greenland
As a jurisdiction, Greenland has its attractions and is regularly ranked as one of the most attractive places for mining investment by various industry surveys, accepted. The government is becoming ever more mining friendly as it looks to take advantage of the island’s rich resources and, in contrast to the locations of many AIM listed junior miners, the country is politically stable. As mentioned above, climate change is causing ice sheets to retreat, creating the opportunity to study new potential resources.
But there are many challenges related to operating a mine in Greenland, mainly due to the harsh climatic conditions and remote location.
At Pituffik itself the average daily temperature in July barely reaches 8°C, with the winter months typically seeing temperatures of around -20°C. This creates a situation where certain activities can only be carried out at certain times of the year and makes for a more expensive operating environment. With pack ice forming in the early autumn the window for making shipments from Pituffik could be as low as five months.
Infrastructure in the country as a whole is limited, with there being no major road networks and most domestic transportation being conducted by air – Pituffik is located c.30km from the international airport and deep-water port of Thule Air Base which is operated by the US Air Force to the south-east and Qaanaaq domestic airport to the north.
Issue over deferred consideration and options shares
As part of the Bluejay Mining acquisition it was agreed that 40,755,885 deferred shares be paid to the vendors upon the grant of a mineral exploration permit over the offshore Pituffik project area. This was subsequently granted in July this year and satisfied one of two terms for the issuance of the deferred shares.
However, the second term requires that the issuance does not trigger a mandatory offer for the company by the Bluejay vendors under Rule 9 of the Takeover Code – ie. if their stake goes over 30% they will have to bid for the whole company. This situation would have occurred had the shares been issued given the Bluejay vendors’ current holding in FinnAust, so the company is waiting until any Rule 9 obligation ceases to exist before the deferred shares are issued. This can only come if the vendors sell some of their holding or, in the more likely case, their combined stake is diluted by further share issues.
There is also a four year option to acquire the remaining 39.63% of Bluejay for £594,393, to be satisfied by the issue of 108,071,388 new FinnAust shares to the Bluejay vendors. Again the situation is similar here in that the option will not be exercised if it were to trigger a mandatory offer or would trigger a reverse takeover under AIM rules. We note the RNS of 4th October in which Rod McIllree makes the statement “The Company now intends to review the mechanics of moving to 100% ownership of BlueJAy Mining Ltd (and hence Pituffik)…” and believe that this will be the “tell” that in fact unseats the stock price. The easiest avenue is simply to place the stake due to Blue Jay with a third party. As we point out below however, with a market cap approaching £50m without a JORC estimate at this point and no clear path to infrastructure build out, our bear case hinges almost entirely on this point – that is we doubt that a third party will pay anywhere near the current market cap in cold hard cash (the acid test for the industry’s perception of true value) for Blue Jay’s shares that are due from Finnaust and would thus absolve the takeover trigger. Of course they could apply for a “whitewash” if no third party steps up but all this does (assuming it was granted) is push out the date required for a liquidity event for the stockholders whilst not addressing the continuing cash needs of the company.
As we illustrate below in addressing our valuation concerns we suspect that any deal to place FAM shares for Blue Jay (if this route is taken) will be at a material discount to the current stock price if done in cash and still so if part of a strategic investor swap (which is what Western Areas is of course supposed to be…).
Director backgrounds
We note that certain Finniest directors have, shall we say “interesting” histories. Rod McIllree was the founder of ASX listed uranium explorer Greenland Minerals and Energy and its Managing Director up until August 2014. Australian newspaper The Sydney Morning Herald reported on several issues with the company including questions over its ownership structure (see here http://www.smh.com.au/business/unravelling–the–greenland–minerals–web–20091008–gp0w.html) and the rapid dilution of shareholders via the issuance and exercise of options. In addition, it would appear that McIllree and fellow director Simon Cato sold stock into the market immediately after exercising options – see here http://www.smh.com.au/business/a–cold–front–for–greenland
“In mid-April (2011) those two (Cato and McIllree), and Why brow, each received 4.4 million newly vested options. Earlier this month (May 2011), Cato and McIllree both announced that they had exercised some of their options, 1.55 million and 250,000 respectively, but their filings suggested that they must have sold them immediately because their total shareholdings remained unchanged.”
The share price performance of Greenland Minerals has been “erratic” to be polite– see chart below. But What Greenland Minerals has in common with FAM is that there was a concerted news blitz that increased the stock price materially before the company was laid low in large part due to the debt that was taken on. The problem with a heavily promoted bull story is that at some point the major stakeholders have to get out and if there is not a liquidity event to provide this gravity always kicks in.
We also point out that Greg Kuenzel, Non-Exec at Finniest, has a history of value destruction at AIM listed Noricum Gold where he is Managing Director. Since the company listed in December 2010 the shares have fallen from the IPO price of 4p to the current 0.12p after failing to prove a JORC resource at various projects.
We also add that we have posed a number of questions to Rod McIllree in relation to these points to which he has deigned to reply.
A mine of information from the 2016 results
While there was nothing really new in the company’s 2016 results regarding progress on the ground the P&L and balance sheet provided a wealth of information. It was revealed that cash as at 30th June stood at just £425,046, although this figure was boosted post period end by a £500,000 (preexpenses) placing. With monthly administrative costs being c.£52,500, and assuming placing fees of c.£25,000 we estimate that the current cash balance amounts to around £0.75 million. With this amounting to just over 1 year’s worth of admin costs there is clearly a placing ahead, we suspect in the first half of next year at the latest.
Non-participation of major shareholder in last 2 placings
Back to the placings… Finnaust has raised a total of £1.5 million since announcing the Bluejay acquisition – £1 million on 4th March at 2p per share and £0.5 million on 13th July at 5p per share. Our question is why has Western Areas, trumpeted as a cornerstone investor, not taken part in these placings? And why did it only put £100,000 into the original acquisition placing? WhileTakeover Code rules prevent Western Areas as a major shareholder (37.14%) from increasing its interest, we believe it could have at least maintained its holding noting that the Bluejay acquisition document states:
Following completion of the Placing and the Bluejay Acquisition, neither Western Areas nor the Bluejay Vendors will be able to increase their interests in the voting rights of the Company through or between a Rule 9 threshold without Panel consent.
Valuation
The main question here boils down to the valuation.
At the current share price of 7.5p the markets are valuing FinnAust equity at a shade over £37m million. But if we calculate the valuation using the fully diluted number of shares in issue (see table below) then we arrive at a figure of £49.6 million
Current shares in issue
494,400,804
Options & warrants
19,309,366
Bluejay deferred consideration
40,755,885
Bluejay option
108,071,388
TOTAL
662,537,443
While we do not deny that FinnAust’s assets have potential we firmly believe that a figure of approx £50 million is simply far too high given the company’s current stage of development.
Even a research note written by the company’s own broker, Optiva Securities, back in February admitted that valuing the company was “challenging” largely given the early stage nature of the operations. We quote:
“Given the early stage of the Pituffik project, limited exploration data and the fact that the deposit does not yet support a JORC-compliant mineral resource estimate, it is challenging to estimate a value for the project in its current stage, in our view.”
Here’s why we think the valuation is overheated.
Pituffik remains a very early stage asset. As yet there is no JORC resource, an exploitation licence to apply for, social impact assessment to complete, inevitable future placings to complete for working capital and the all important project financing to be raised.
Minimal asset backing on the balance sheet. Net assets amounted to £12.48 million as at 30th June, with most of these being in the form of £12.63 million worth of intangibles. These include £1.9 million attributed to the Pituffik licence. These values would have been hard tested by the auditors and is the first “tell” that the market cap is out of sync with the current stage of resource progression. Remember this value includes ALL the company’s assets too not just Pituffik.
Stripping out the book value of the non-Pituffik assets as at 30th June 2016 (£10.7 million) from the current valuation reveals that the market is effectively valuing Pituffik, an asset that was valued by the Bluejay vendors themselves at just £1.5 million only 10 months ago, at approx £40 million (on a fully diluted basis). We question whether the work done since acquisition has justified this 26-fold increase in value.
One valuation benchmark we can use is a November 2015 technical report compiled by consultants SRK which determined a valuation range of $0.6 million to $24 million for Pituffik based on a variety of variables. While the report excludes the offshore dredging element of the project we note that even the highest valuation of $24 million represents a value of just £18.4 million – less than half the fully diluted current market price.
Another valuation benchmark comes from the recently announced £215 million acquisition of mineral sands producer Sierra Rutile by Iluka Resources. The deal was completed on a historic enterprise value/EBITDA multiple of 16.2 times. Assuming a build out cost to FinnAust of say c.$20 million (£15.4 million) gives an enterprise value for the company of approx £65 million. Applying the Sierra Rutile exit multiple thus means that FinnAust needs to be making annual EBITDA of c.£4 million to justify anywhere near the current valuation.
We believe Finnaust has been a text book example in how to release news to the market in relation to a potentially positive mining opportunity whilst simultaneously keeping the free float tight. A classic squeeze if you wish.
But, once sell orders start coming through, which we suspect they may do as private investors look to take profits or, more likely, any strategic investor puts a very different valuation on the company’s assets given their current stage, the tumble downward could be rapid. While the deal in Greenland with Capricorn/Cairn is not yet complete when it is, we suspect there will be another £500,000 worth of shares in the market looking to be sold – we doubt Cairn will be looking to hold on to the stock given they wanted to be out of the assets at such a low price and they are after all much more financially resourced than FAM to develop them if they so wished.
The fact is that, while many have made large paper profits on FinnAust, liquidity remains low and a value event is needed for those gains to be realised. If the company itself needs an exit, if it is overvalued the industry simply will not pay up.
It’ a sorry tale I tell this afternoon on Sula Iron & Gold (LON: SULA). Sula are a serial failure who over the many years have never attained anything of true value for their share-holders, other than continual dilution and placing after placing. In fact they are little better than a Lifestyle company. I have more gold on my little finger than this lot have ever produced.
Investors need to be aware of exactly how the Board operate and how they continually raise cash and dilute to keep the lights on. Take for instance the recent placing on 10th March 2016. Billed as an existing Institutional/Cornerstone Investor taking yet more stock. We are told in that RNS that the ‘Institution’ also took part in the fundraising in October 2015. How much of the 166,666,664 shares issued in that placing wasn’t disclosed nor indeed was their name. Take a bow Jub Capital. Who in the March 2016 placing took 118,750,000 new ordinary shares at a price of 0.16p per Subscription Share. In addition to 65,312,500 ‘warrants’ were also granted at a price of 0.16p per share. Now fast forward to 24th February 2016 placing. A placing of 181,250,000 new ordinary shares of 0.1p each in the Company at a price of 0.16p per Placing Share. In addition to the Placing Shares, 90,625,000 warrants were also granted to placees at 0.16p per share. How much stock Jub took in the 24th February 2016 placing again isn’t disclosed nor again are they named. What we do know is that they took part.
‘Socialite’ Adam. Institutional Trader NOT Investor
The majority of that stock taken in the above three placing’s has been quietly drip fed into the market and unsuspecting retail investors. And will continue to be sold down. I spoke to the head honcho, ‘Dashing’ Adam Dziubinski, this morning. He confirmed that his company/clients now hold approx.’ 80 million shares. Which begs the question; Just how many shares have they sold into the market? They took part in at least two/three placing’s and have been and continue to quietly off-load Sula shares. You maybe wondering with such a large chunk of Sula why no notifiable RNS has ever been issued. I’ll tell you. The ‘Institutional/Cornerstone Investor’ purchases the stock and splits it into batches under notifiable thresholds for themselves and their ‘Clients’. All quite legal, but extremely disingenuous. This allows them to sell without having to notify via RNS.
Jub Capital are NOT a cornerstone Investor they are trading the stock at each and every opportunity, to make their margins. That isn’t investing it is trading/flipping, below the radar and should be disclosed at the time of their purchases. i.e. they have bought them to trade NOT invest! The playing field needs to be levelled. It is Institutional trading NOT investing and should be declared as such.
In the space of approx. seven months the Sula CEO Nick Warrell has raised ‘in discounted placing’s’ £1,500,000 and if my sources are correct they will place yet again in the not so distant future, probably after the City boyos have sold out their ‘Institutional/Cornerstone holdings’! That placing will again be ‘discounted’. If their share-price stays were it currently rests the placing price will be circa 0.10p.
 Aterian are fast tracking and advancing their portfolio of African-focused critical and strategic metal assets, in the Republic of Rwanda. So much so that sources indicate that there’s a gargantuan global player in discussions with them looking to partner and, or, buy in to the tune of £10M-£20M into their Rwanda plays. At what stage these discussions are at has been ‘researched’ by ‘yours truly’… So much so that I’ve taken a small punt. News could drop at any time. If and it is an ‘if’, as nothing is certain, that news drops then the SP of Aterian will go ballistic. What is known by this site is that the potential partner could be one of several. It’s known that Majors such as BHP, Rio Tinto, Glencore are entering Rwanda. News of any one of these three big hitters will send the Aterian SP through the proverbial roof. Rwanda is one of the worlds largest producers of Tantalum, Tungsten and Tin. The upside is huge with per tonnage prices in the 100s and 10s of thousands of dollars, dependent on what metal..