google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: oil discovery

  • Zenith Energy. Congo Update!

    Zenith Energy. Congo Update!

    Just a quick update on Zenith Energy (LON: ZEN). Those that follow this blog will be aware that I’ve been tracking the company for quite some time. You’ll also be aware that, unlike others, who’ve told a pack of lies and have ‘flooded’ the super information highway with malicious musings, which have been completely wrong, ‘Yours Truly’ has called this stock correctly as well as the ‘machinations’ within, outside and online ‘correctly’.

    Zenith has a range of assets: Tunisia, Italy and the one that should interest you, Tilapia, situated in the The Republic of the Congo. For those that don’t know the Republic of Congo is one of Sub-Saharan Africa’s largest oil producing countries with circa 1.6 billion barrels of proved crude oil reserves, 3.2 TCF of proved natural gas reserves, and a daily production of approximately 300,000 barrels of oil per day. It has an established history of prolific oil production operations, specifically by majors including ENI and Total who have been operating in-country since 1968.
    Now I like Tilapia, I think it’s a ‘company maker’ and the chance of success (COS) is certainly much higher than is understood at present. And here’s one of my reasons. The Align Research Note on Tilapia when the licence was held by AAOG, African Oil & Gas. This is what Richard Jennings wrote in January 2019:

    "Anglo African Oil & Gas (AAOG) joined AIM in March 2017 and
    subsequently acquired a 56% stake in the Tilapia Field in the Republic of
    the Congo for US$5 million. This was a cracking deal as Tilapia is a proven
    producing asset with substantial upside potential in the Lower Congo
    Basin, an established and prolific location for hydrocarbons. Multiple
    discoveries have been confirmed from the TLP-103C well in the R2 and
    Mengo reservoirs and now the well is being drilled deeper.
    Mengo discovery and R1/R2 look set to boost production to 750 bopd
    A 44m oil column in the Mengo has been confirmed - nearby fields produce
    500 bopd per well with stimulation. Experts believe that 400 bopd is
    achievable with water flooding from the TLP-101. Added together, this
    suggests a minimum of 750 bopd, making AAOG nicely cash flow positive.
    Djeno is the big prize and success here could be transformational
    TLP-103C is now targeting the Djeno, a reservoir where Eni, TOTAL, CNOOC
    & SOCO are all producing nearby at a naturally pressurised 5,000 bopd per
    well. Even if AAOG miss it this time round, lessons learnt will be invaluable
    in drilling TLP-104, planned to be drilled back to back with TLP-103C.
    Existing infrastructure allows discoveries to go into production rapidly
    AAOG is shaping up to be a profitable company, even ahead of any success
    in Djeno. The company benefits from having existing topside infrastructure
    which allows the team to quickly turn confirmed resources into production.
    Risked NPV suggests upside of more than 170%
    Our conservative valuation shows the potential. We initiate coverage of
    AAOG with a first target price of 28.23p and a Conviction buy stance."

    And here’s what FinnCap wrote in June 2018

    "3 in 1 oil. This well is targeting three separate reservoir horizons with a range of risk/reward – low risk appraisal of 2mbbls of producing reserves in the R1/R2 sands (6.3p/sh), appraisal of an 8-24mmbbl undeveloped discovery in the Mengo sands potentially worth 18-45p/sh on a risked basis, and a deeper exploration prospect in the Djeno sands, assigned gross prospective oil resources of 16-42mmbbls. This final target carries higher risk (25% CoS) but also higher reward. Our risked valuation range for the Djeno of 16-39p/sh rises to 69-159p/sh when fully de-risked."

    So, regardless, of who wrote what and when it was written, the value which was assigned to AAOG by the two research notes is by irrefutable ‘Vulcan logic’ transferred to Zenith Energy. To say that this point has been lost in the vitriol that’s plagued ZEN is an understatement. Tilapia is a big play with potential oil flows of 1,000 bopd, from a low case of 26M barrels to the high case of 5,000bopd from circa 70M barrels of oil.

    Further more you may have noticed that a delegation from Congo was in Italy having meetings with Zenith and were visiting the companies Italian gas assets. I’m hearing that the delegation went away impressed with the site visits and the company’s abilities in the O&G sector. Now that’s important because there’s further upside in Congo vis-à-vis Congolese gas and it’s my gut feeling that Zenith will be invited to take part as a preferred bidder in any licence rounds that may come up in the future. 

    So with all that said I’m currently trying to arm twist Zenith Energy into allowing me a site visit to Tilapia. It’ll more than likely fall on deaf ears but should it happen, I’m now throwing out a challenge to ‘The ShareProphet’, Tom Winnifirth. I will foot all Toms costs if he wishes to accompany me to the Tilapia  drill site in the Republic of The Congo. Do please pass it on to Tom.
     

    Viva


    Dan


  • Union Jack Oil. Latest Arden Research Note!

    Union Jack Oil. Latest Arden Research Note!

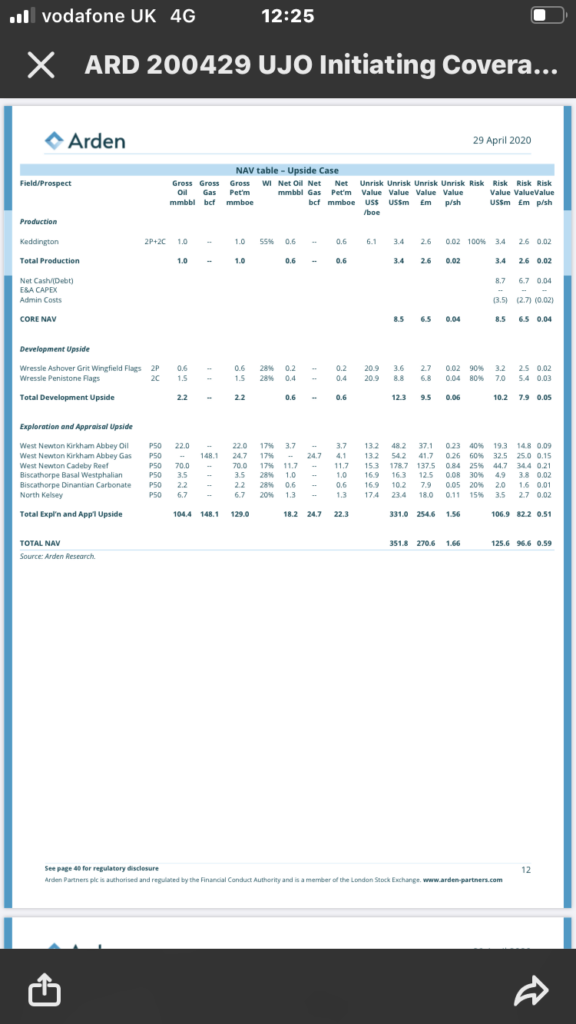
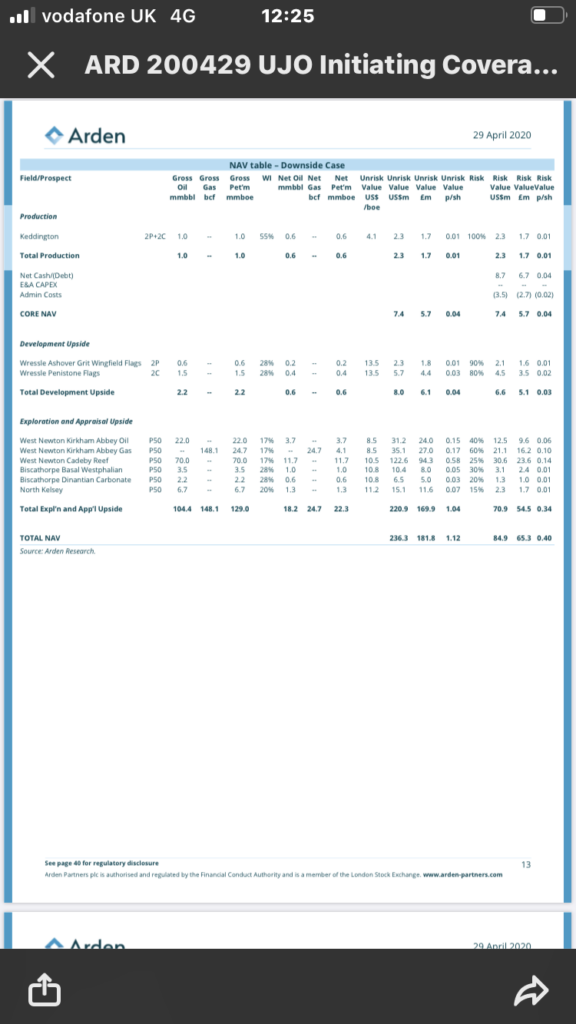
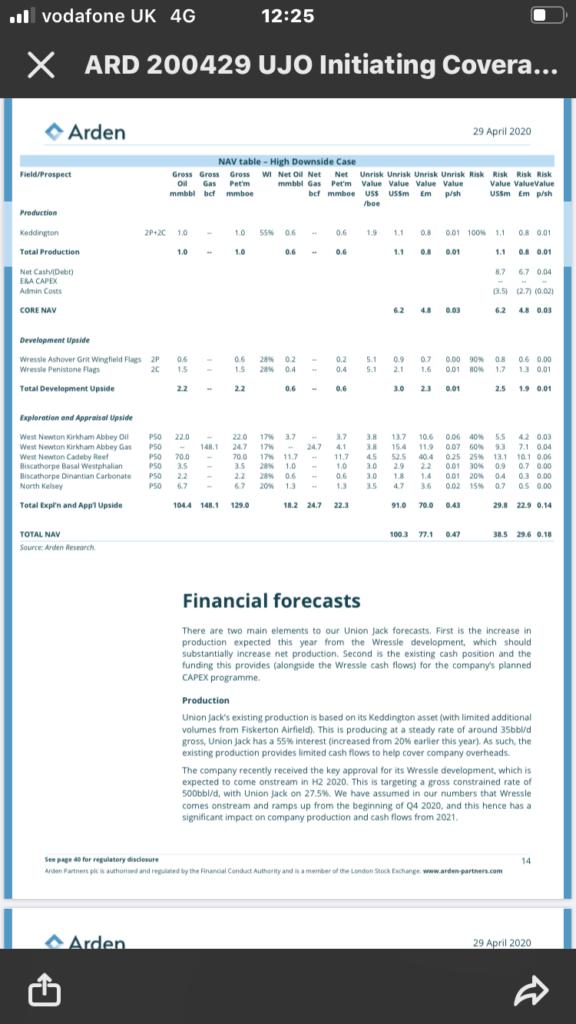
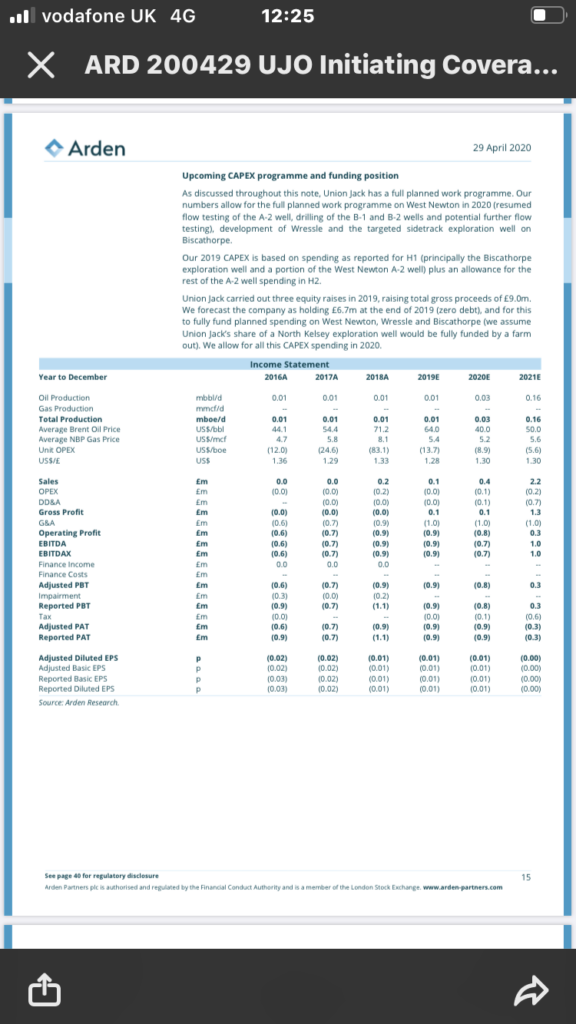
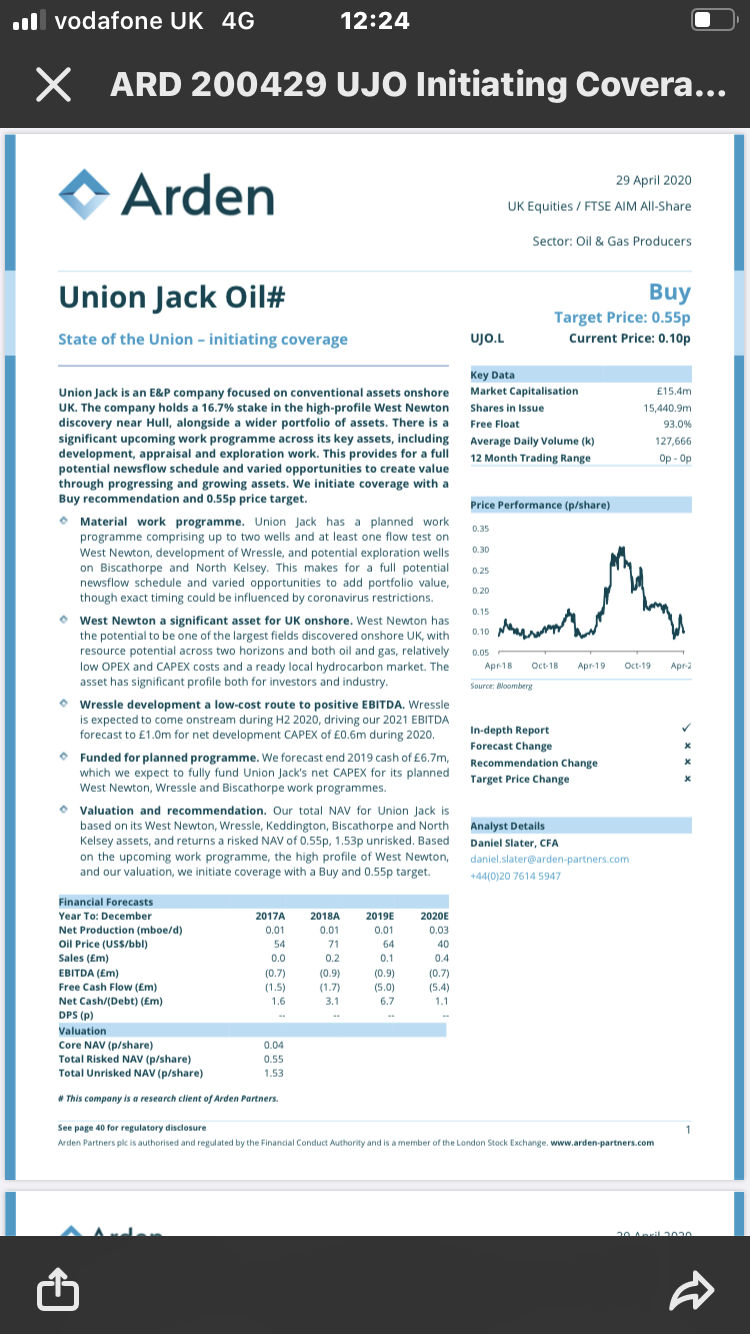
    This is the latest hot off the press Union Jack Oil (LON: UJO) Research Note.

    I’ve used my PDF embedder so you can scroll through it by hovering your cursor on the note.

    Enjoy the read.

    Dan

  • ShareProphets, Tom ‘Pepper’, Red Faces All Round on Zenith Energy!

    ShareProphets, Tom ‘Pepper’, Red Faces All Round on Zenith Energy!

    It’s an absolute shocker today for the ‘erstwhile’ writers at ShareProphets and Mr Marmite, Tom Winnifrith.
    For month upon month over a considerable period of time, they’ve ran ‘interference’ (LIES) on Zenith Energy & the CEO Andrea Cattaneo. A campaign of spite and hate has today been exposed by Zenith’s successful award of the Tilapia2 Congo licence.

    For those unfamiliar with the ShareProphets ‘Jackanory’ here’s the basics. TW has been attacking Zenith at every opportunity not only by claiming numerous times on ShareProphets & Twitter that the company had lost it’s Tilapia licence but by constantly making unfounded complaints to the FCA. The campaign has culminated in decimating the Zenith Energy SP, to all time lows, Shareholders have paid the price and lost huge amounts of cash on the, to put it mildly, ‘Ravings’ of Tom that Zenith had “lost the Tilapia licence.” 

    I warned Tom that his ‘Ravings‘ were inaccurate not only damaging to Zenith but their Shareholder base. Zenith never ‘lost the licence’, they were in a renegotiation with the Republic of Congo. At worse and at best, It was a binary outcome. However to refuse to change course, away from the lies and objectively ‘tell it as it is’ has now resulted in one almighty embarrassment for ShareProphets & Red face TW. ‘Cause believe me Tom Winnifrith will be cringing today.. Oh to be a fly on the wall at Winnie Towers….

    If they had told it as it was the SP of Zenith would probably be 2/3p today. There failure is a failure of truth. To ‘bear false witness against they neighbour’  serves nobody, especially when it comes from several malcontents who were feeding your ego with spurious lies, greedily swallowed by ShareProphets for nothing more than clicks & subscriptions. But that ‘Click Bait’ has now come full circle to bite your arse. Did I tell you Tom or did I tell you?

    Tom Winnifrith now owes each & every Zenith shareholder an apology. A full ‘mea culpa’ with an even bigger personal apology to the CEO who has conducted himself with gentlemanly aplomb.

    But don’t hold your breathe, the only thing that’ll come will be Weasley words…

    Time to ‘fess up’ Thomas Pepper, admit that you got it wrong ‘Bigly’. Pack in the Hate Campaigns. Base your articles on known, verified parameters.

    Then you too can be like me. Telling it as it is, good or bad. The Truth will set you free! 


    Viva


    Dan

    x


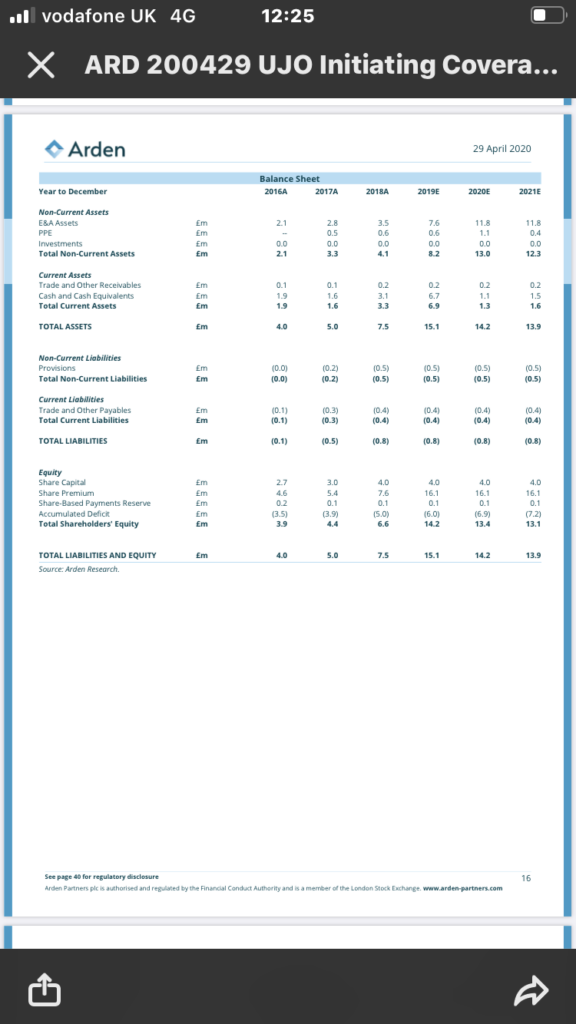
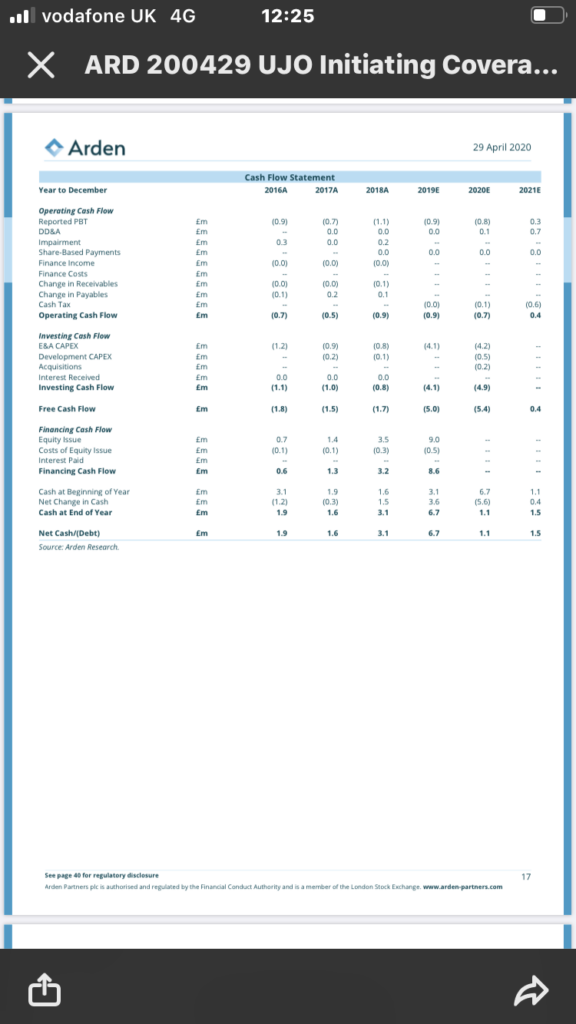
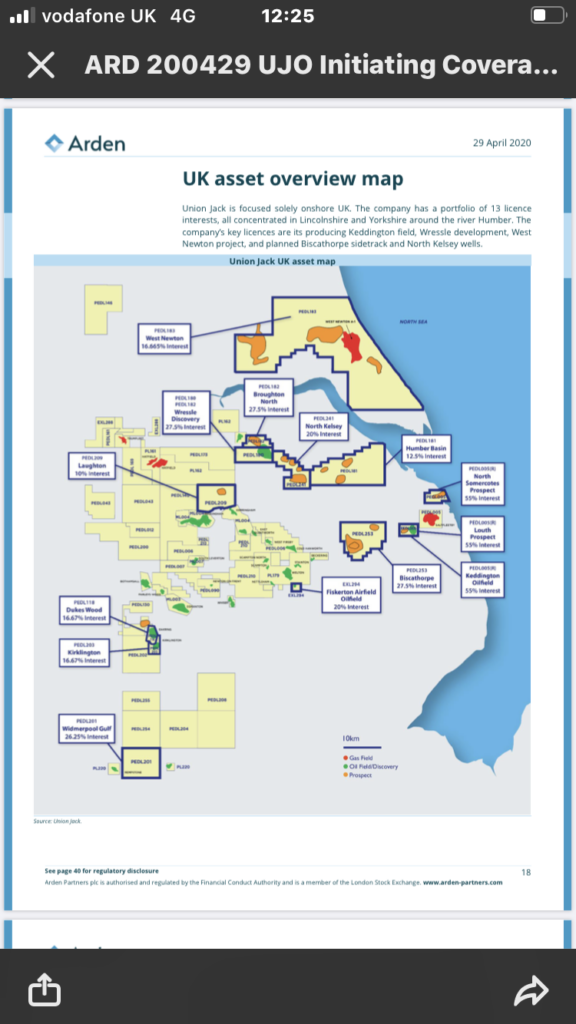
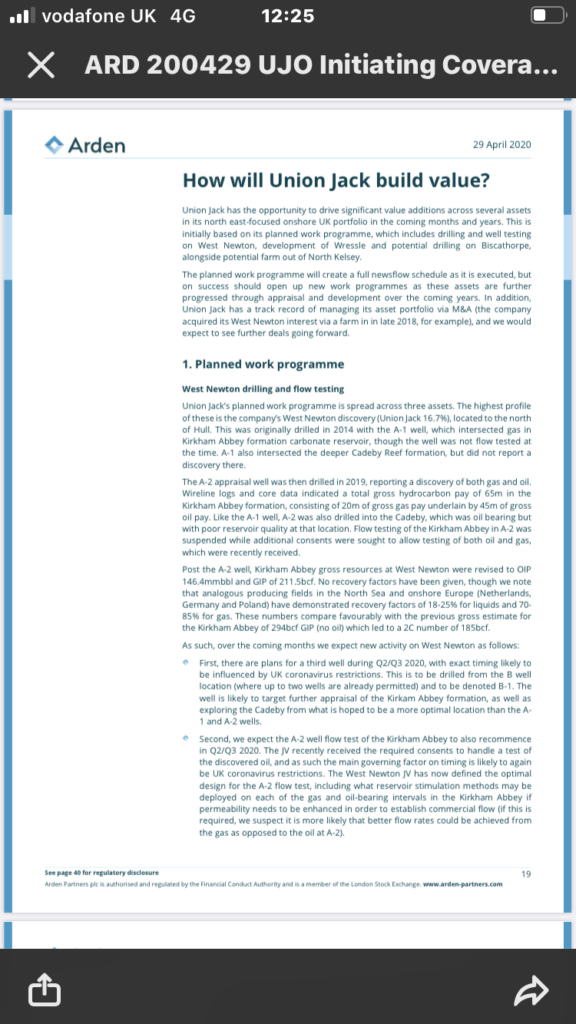
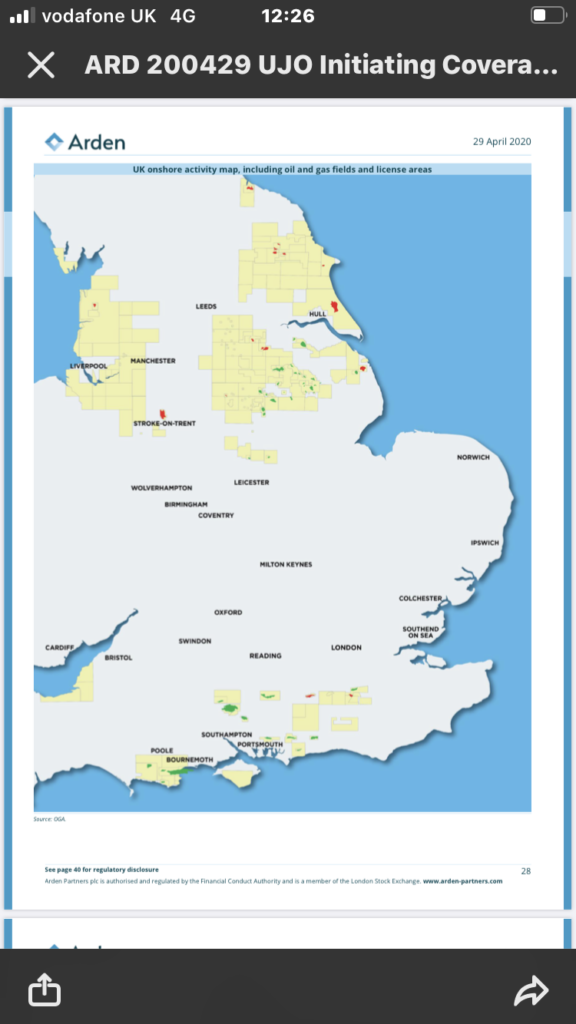
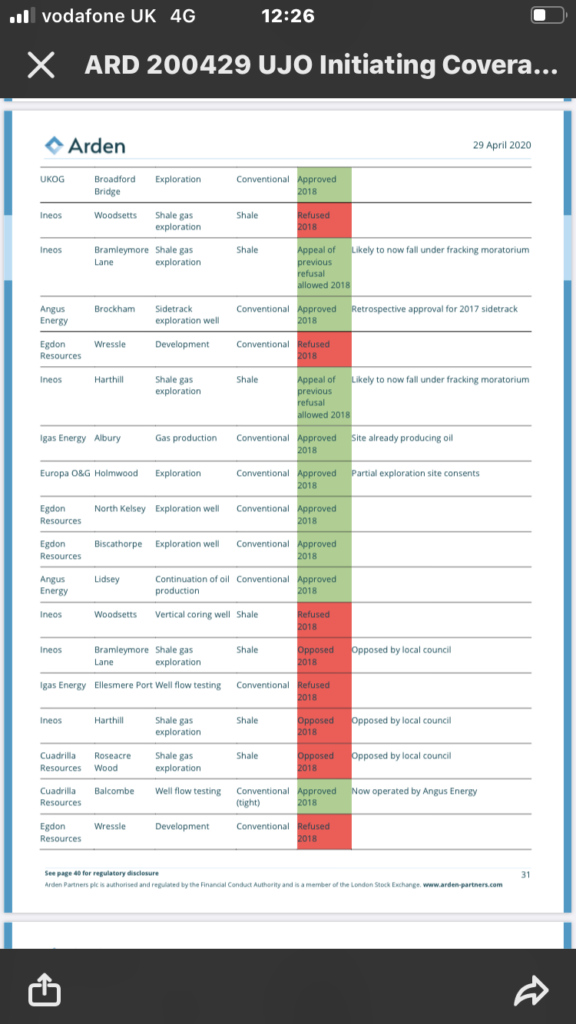
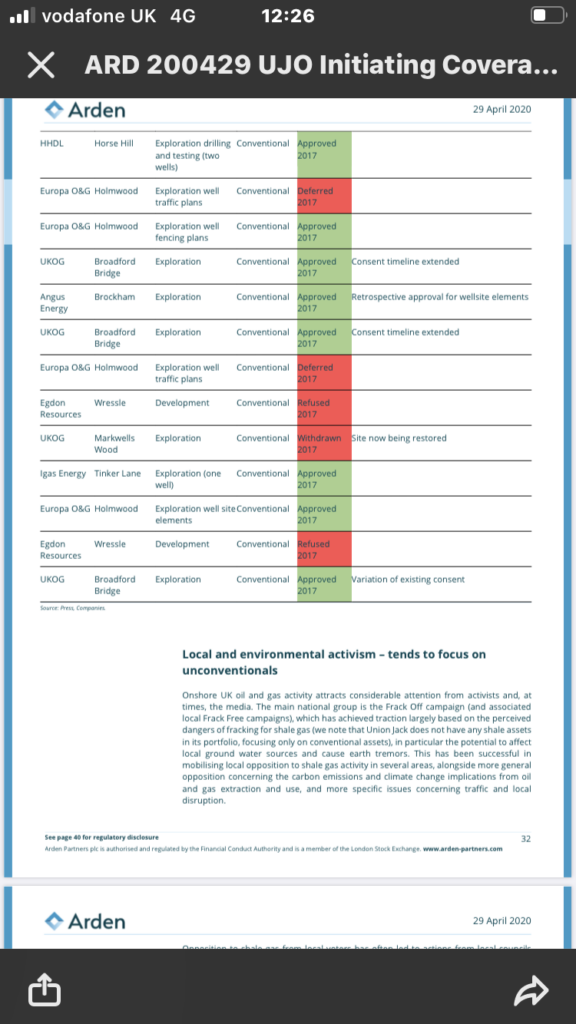
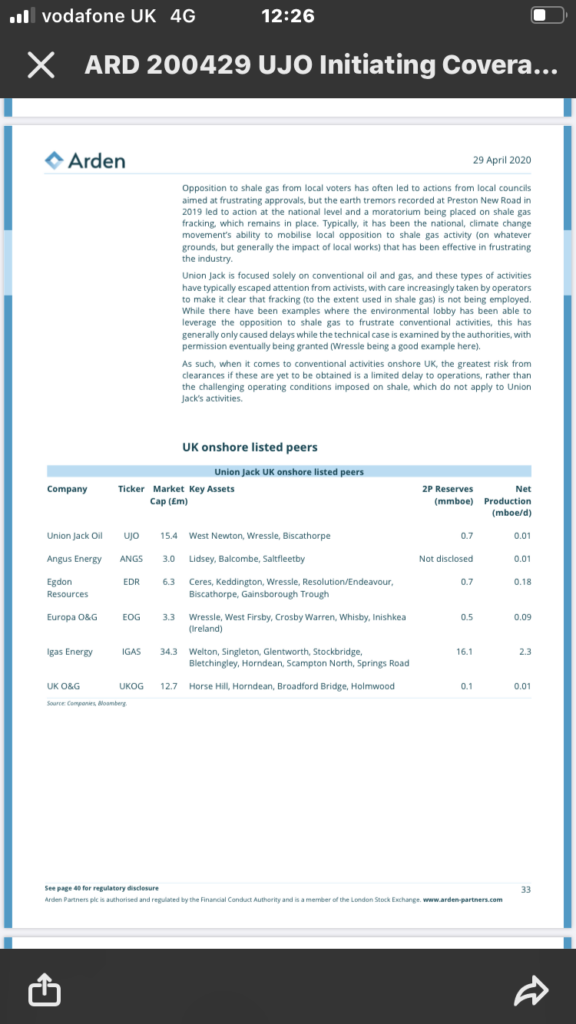
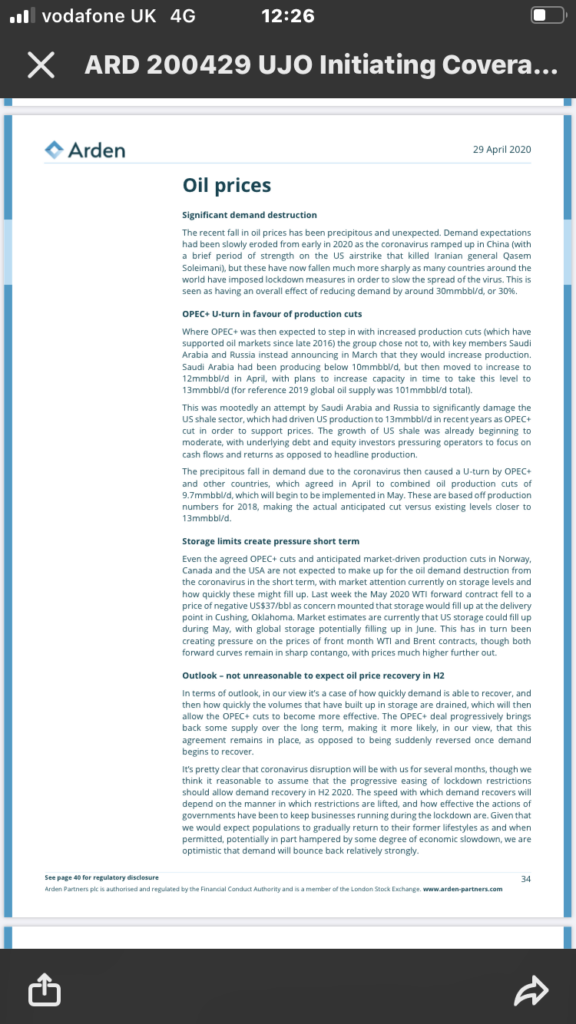
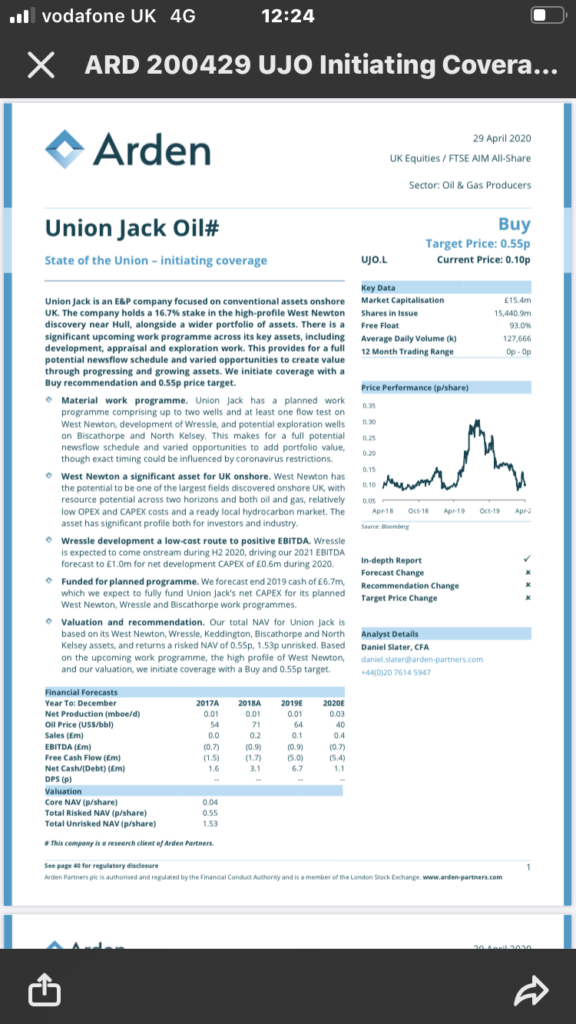
  • Arden Partners Coverage: Buy Union Jack Oil: Upside 450%…..

    Arden Partners Coverage: Buy Union Jack Oil: Upside 450%…..

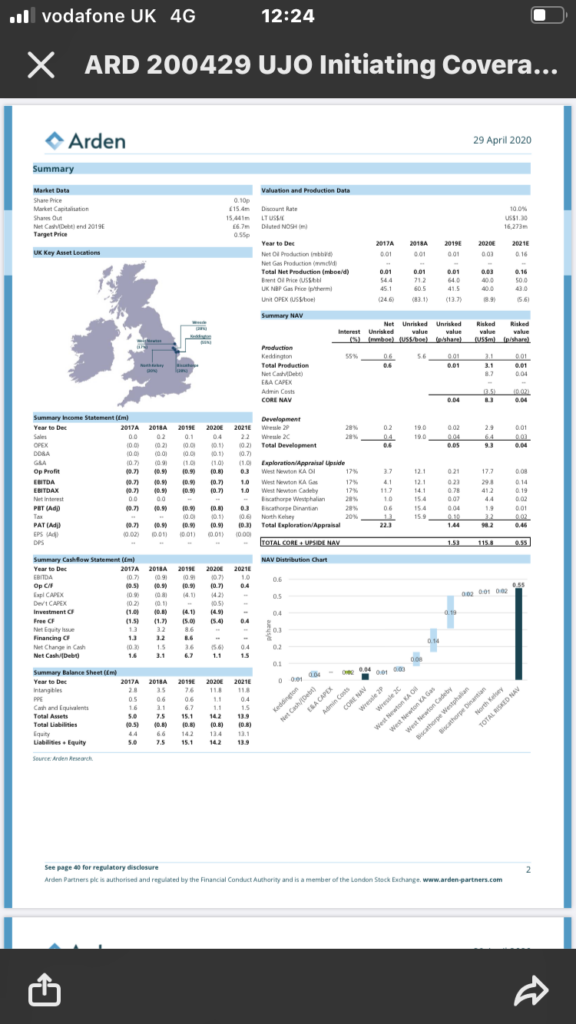
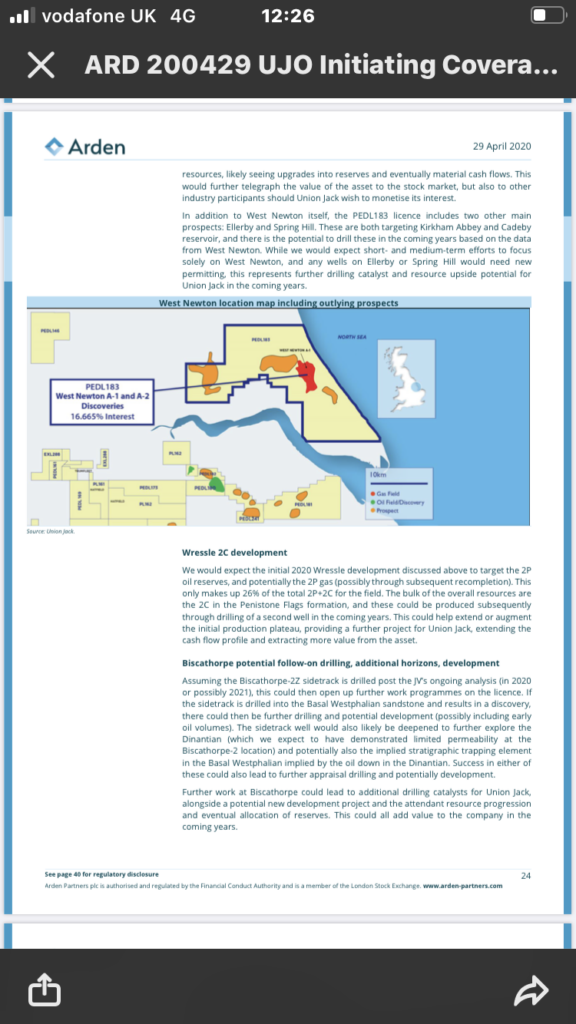
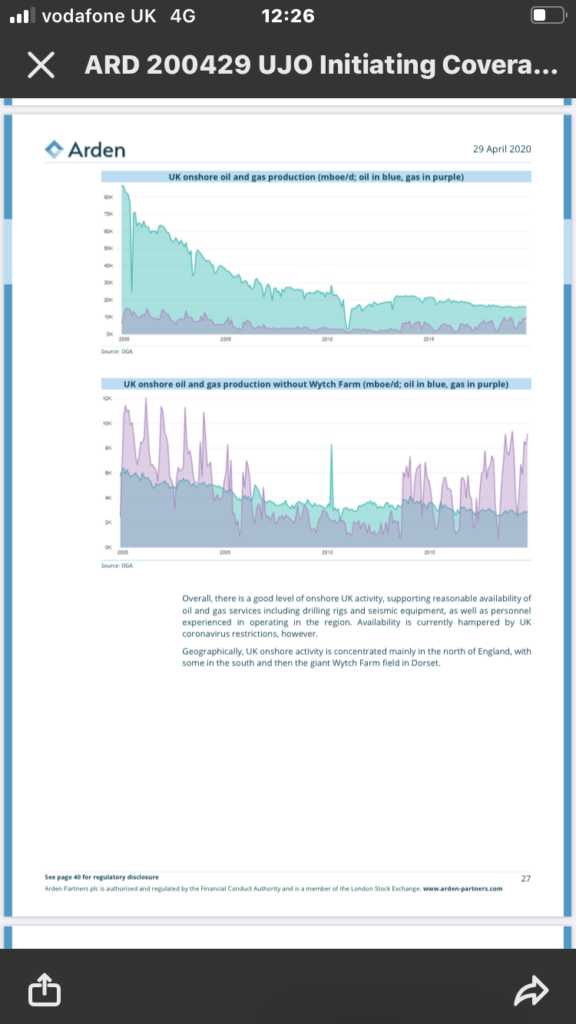
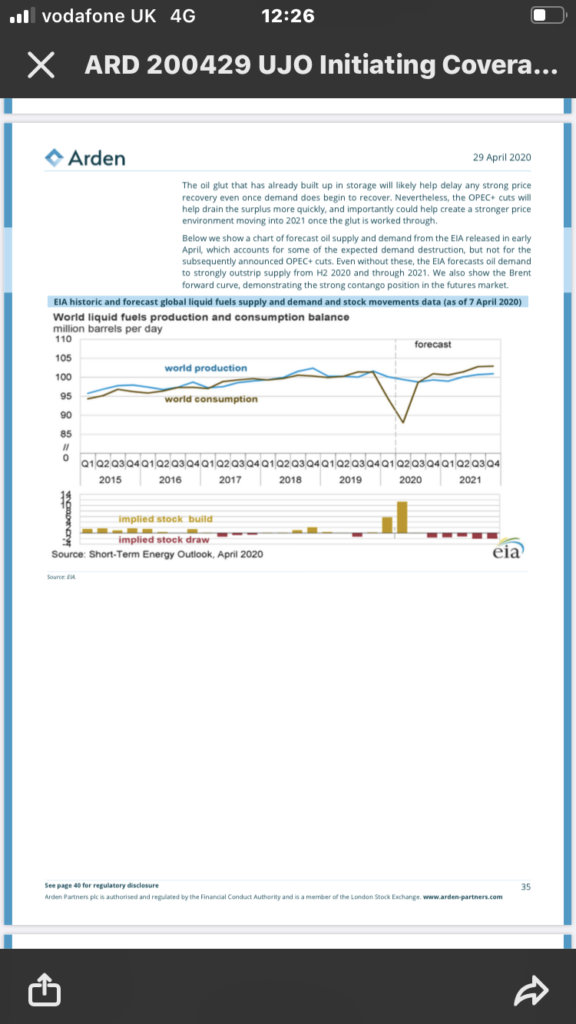
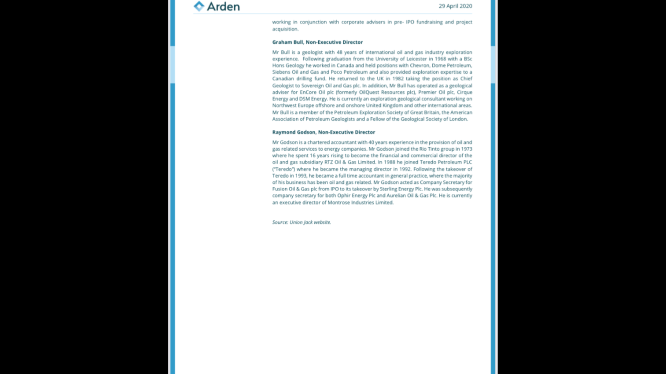
    As stated on twitter yesterday, I’ve managed to get hold of the latest Research Note on Union Jack Oil (LON: UJO). It’s by Arden Partners who are a ‘dedicated corporate adviser and multi-service stockbrokers’. A small outfit and themselves a listed company.

    I don’t propose to go into a convoluted epistle on the pros & cons of buying, trading, investing in UJO. I’m going to leave that to the reader of this ‘Hot Off the Press’ Research Note.

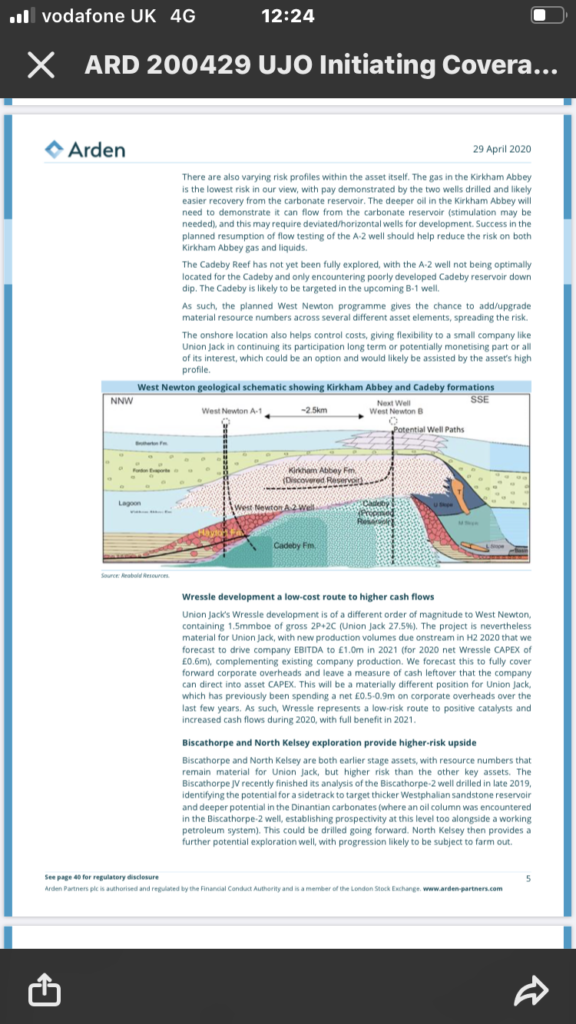
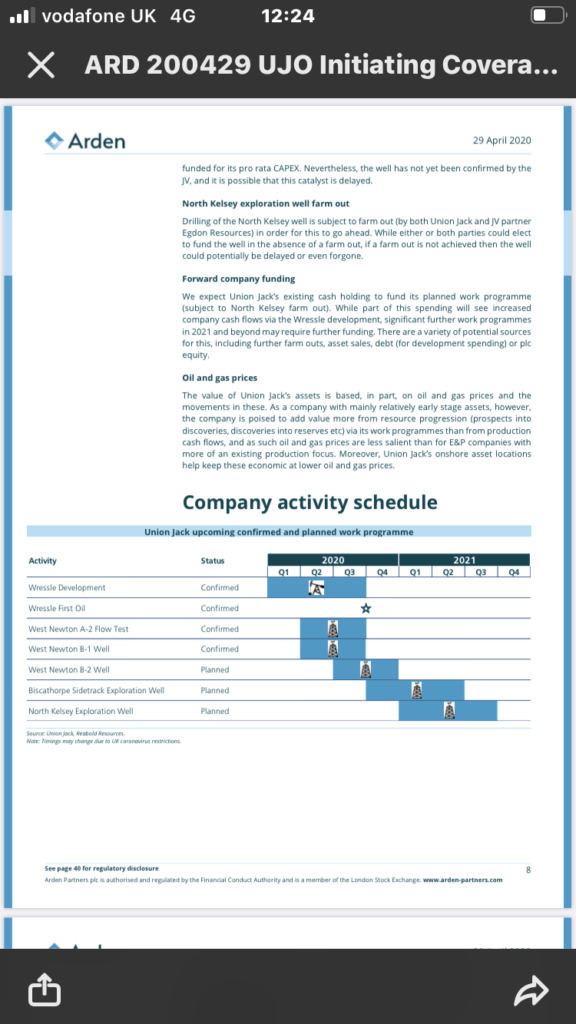
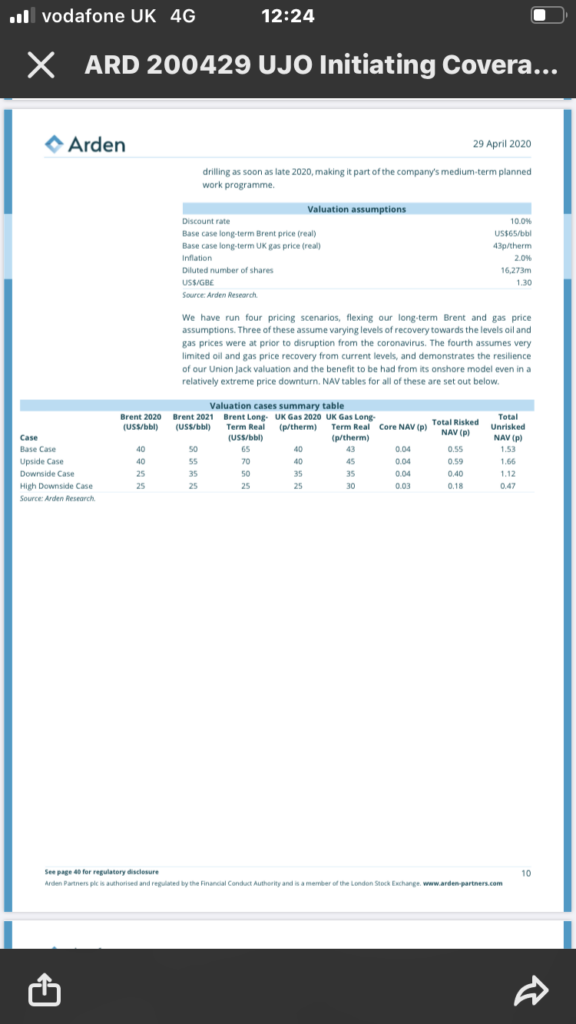
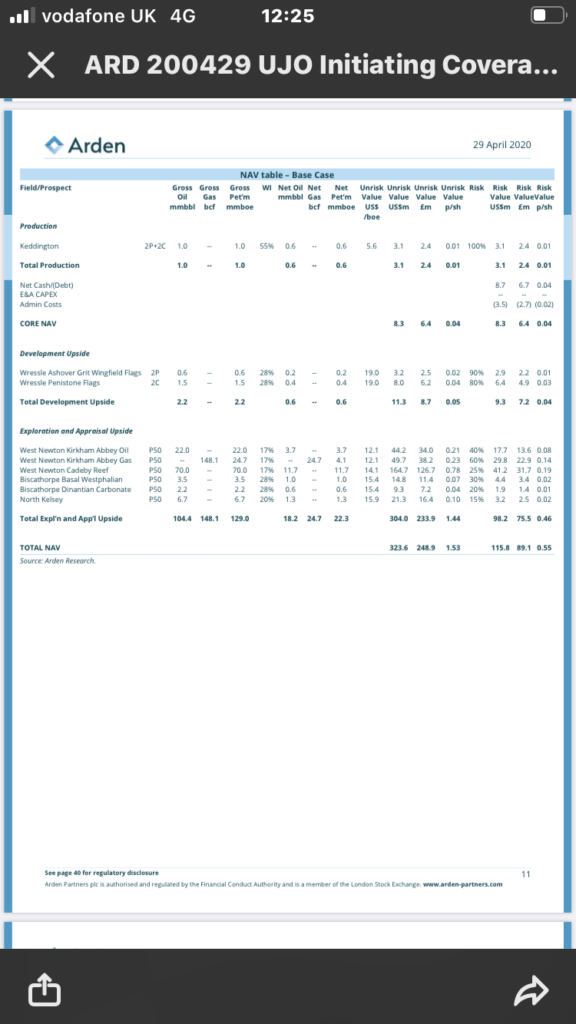
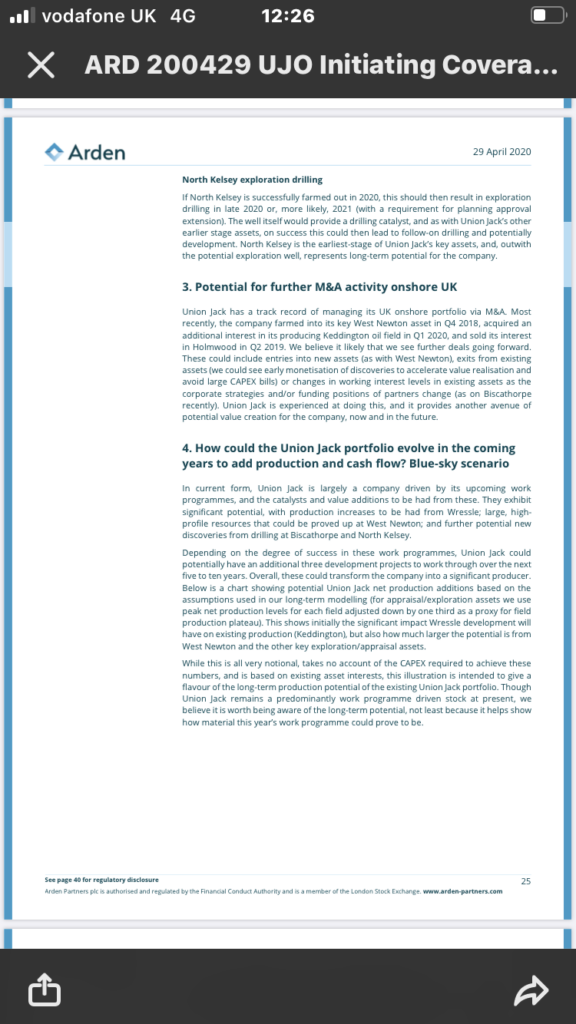
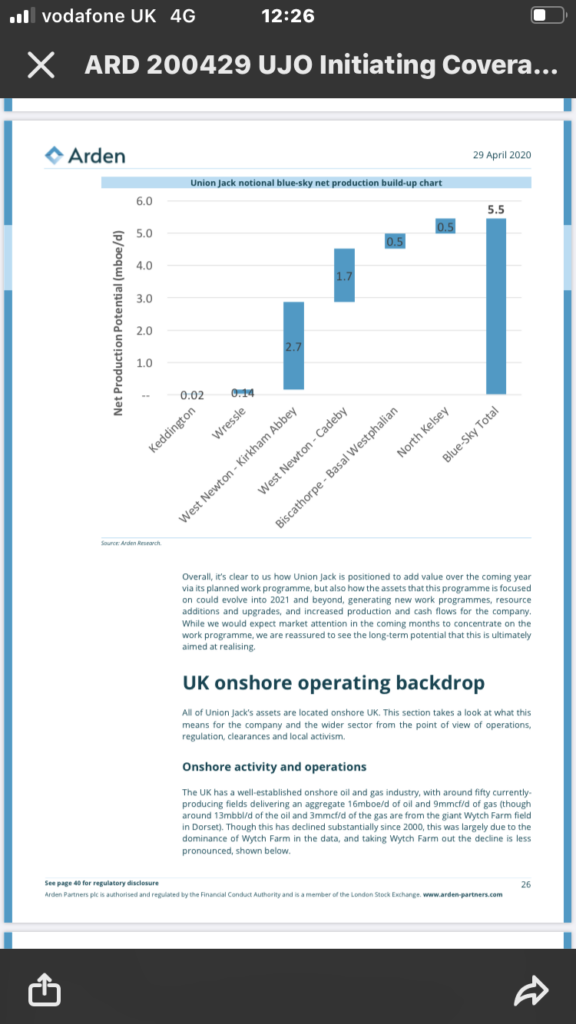
    Suffice to say it’s a buy rec’ with an unrisked NAV of 1.53p and a risked NAV of 0.55p which equates to a 450% gain from yesterdays SP of 0.10p.

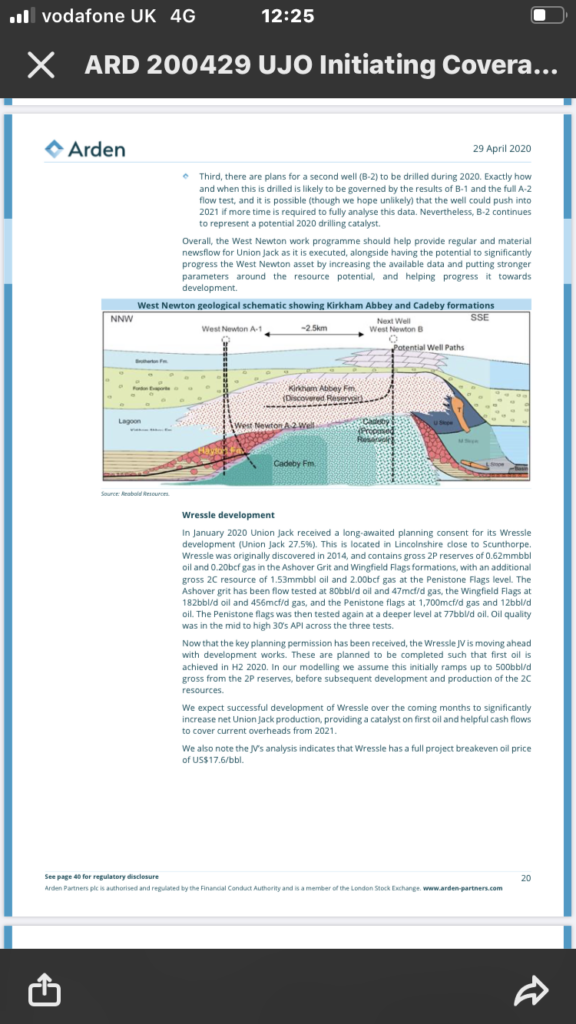
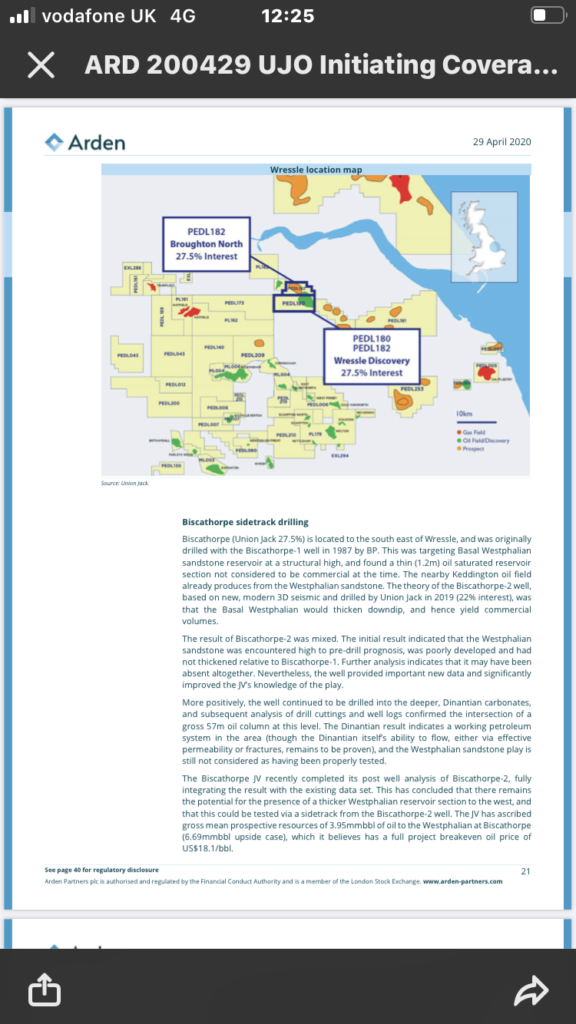
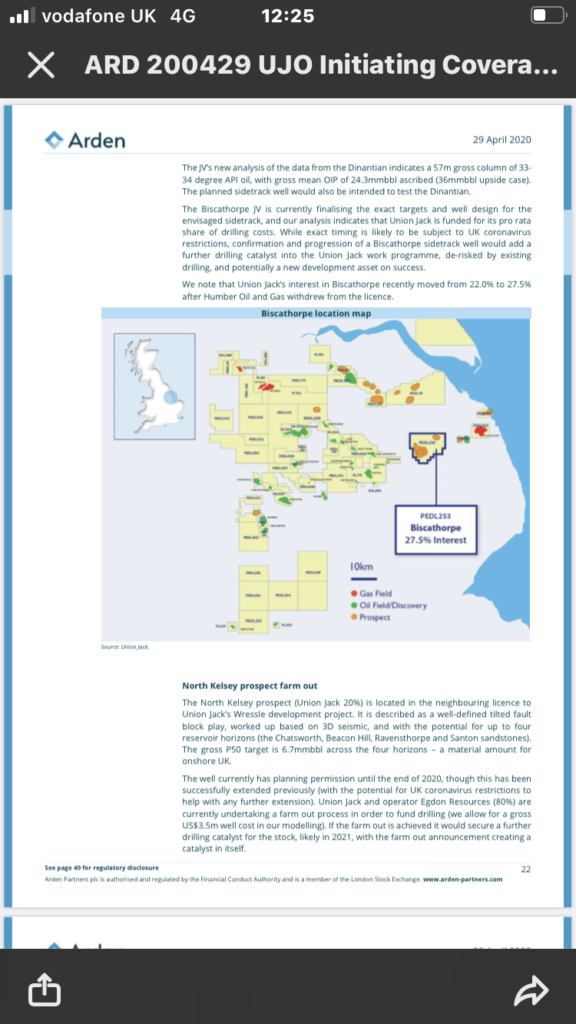
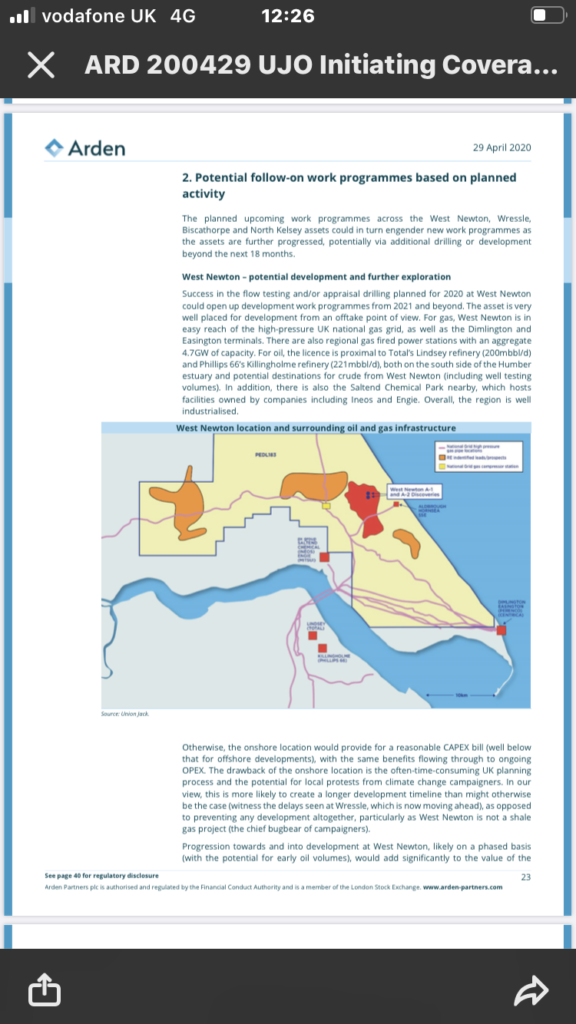
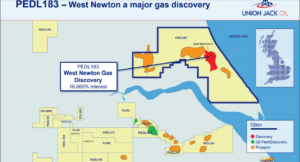
    By now most of you should be up to speed on all things West Newton, Biscathorpe, Wressle, Keddington and North Kelsey. Success at the fast approaching West Newton discovery via flow test will launch the SP upwards. 

    Happy reading and good luck.


    Viva

    Dan

    Page 1
    Page 2
    Page 3
    Page 4
    Page 5
    Page 6
    Page 7
    Page 8
    Page 9
    Page 10
    Page 11
    Page 12
    Page 13
    Page 14
    Page 15
    Page 16
    Page 17
    Page 18
    Page 19
    Page 20
    Page 21
    Page 22
    Page 23
    Page 24
    Page 25
    Page 26
    Page 27
    Page 28
    Page 29
    Page 30
    Page 31
    Page 32
    Page 33
    Page 34
    Page 35
    Page 36
    Page 37
    Page 38
    Page Bio
    Disclaimer
  • West Newton. The Reality Is It’s A Billion Dollar Oil Discovery. Clarification For The Morons.

    West Newton. The Reality Is It’s A Billion Dollar Oil Discovery. Clarification For The Morons.

    To hold or not to hold? That’s the question being asked by share-holders of Union Jack Oil (LON: UJO)  & Reabold Resources (LON: RBD)

    There’s been a lot of piss & wind posted recently on the, Rathlin operated, West Newton major oil & gas discovery. The key to investing and even trading is to pick your entry and your exit, based on what you know as opposed to what’s being eternally spouted on social media. There’s one twitter lunatic who seems to think (Wrongly) that UJOs’ head honcho is responsible for putting in the HSE, O&G paperwork as well as ordering all the capital equipment for the imminent drill/s and any delay is their fault.

    Oil & gas drilling by its very nature is bureaucratic. It’s the Operator Rathlin who lodge ALL West Newton applications. Partners have a non operated interest.  If you have any doubts on your trade/investment in any company or in any sector then sell up and move on. It’s as easy as that. Get out, there’s no shame in selling.

    Yesterdays Rathlin update was forced due to the amount of erroneous speculation circulating on social media. 

    “Rathlin Energy (UK) Limited, as operator of the West Newton A-2 well, is providing the following update regarding the Extended Well Test.

    Preparations for the retesting of the well are progressing both from an operational and a regulatory standpoint.

    Coordinating the availability and timing of services, equipment, personnel and other aspects of operations with the requirements of our regulators is imperative.

    These activities and approvals are often dependent upon one another.

    Rathlin Energy (UK) Limited will provide operational updates via this website when appropriate.

    Kind regards

    THE RATHLIN ENERGY (UK) LIMITED TEAM”

    So with the above in mind, here’s exactly what’s going on. The Extended Well Test and site mobilisation are a matter of days away. All equipment has been sourced with a date pencilled in for the EWT, and the drilling by Rathlin of West Newton 2B could happen in concert or be very close behind the EWT. One rubber stamp is awaited from the EA. That application, according to my sources, went in last week. The usual turnaround from the HSE/EA is 14 days. So my ‘back of the fag packet calculations‘ are end of this week beginning of next. Site mobilisation and EWT are imminent. Don’t be fooled or get caught out. When the news drops the SPs are only going one way. 

    Reabold and Union Jack are fully funded for at least 18months, both have paid up in advance. There should be no placings in 2020. Especially UJO whose asset/production base are all UK onshore. Onshore drilling, compared to offshore, is way, way less expensive.

    There are at least 2 oil predators awaiting the EWT oil flow results. That means that if it flows, as expected, from the  60,000,000+ boe then there’s a real possibility, depending upon how far West Newton 2B has progressed, that the asset will be bought out by either one or both Majors in partnership, circling.

    Share-holders of both listed companies need to remember that West Newton is a billion dollar oil play:

    A major UK onshore Oil & Gas discovery has already been called by the companies. It’s of National importance and as such oil minnows or their interests get swallowed up. That’s how it works in the oil sector.

    Any investor thinking that Rathlin will remain the operator of a Major UK O&G discovery are in ‘la’ la’ land’. An offer or offers will come. That’s a given. Of course oil has to flow. There are only 2 companies i’m invested in: Reabold & UJO. That’s because both have exposure to West Newton. I’m not looking at any of their other assets regardless of how good they maybe. It’s all about West Newton for me. All the companies involved are convinced that (barring a major onsite explosion or a military takeover of the UK) oil will flow. It doesn’t get any better than that…..

    Viva


    Dan


  • West Newton. Oil Discovery Briefed To The Corporates Behind The Scenes.

    West Newton. Oil Discovery Briefed To The Corporates Behind The Scenes.

    Some times, in life, one scratches the ‘proverbial’ head. trying to understand the mechanics/reasons of companies listed on the London AIM. AIM is an incubator where companies list in-order to grow into fully fledged self sustaining profit making business’s. Part of that process involves the timely release of  market sensitive information. There are numerous valid reasons why such information is withheld. But holding back material price sensitive information from retail investors while at the same time furnishing that information to ‘selected’ Funds, Brokers and Analysts isn’t one of them. Neither is withholding  RNSable information from retail investors so as not to upset or appease protesters!

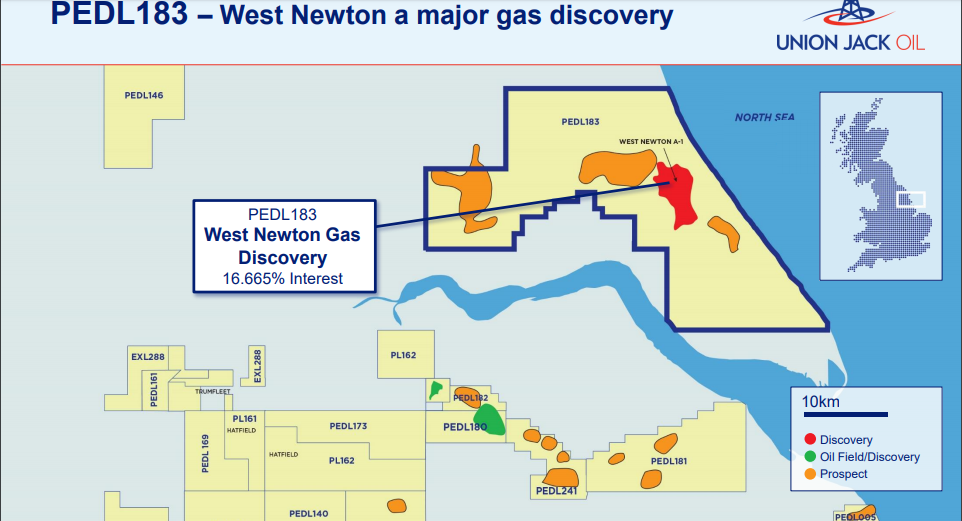
    Documents seen by ‘Yours Truly’  on West Newton state that the initial well results and gas discovery are ‘Outstanding”. With25 metre net pay gas which is likely to be upgraded to 300bcf” The whole report reads like a lottery win.

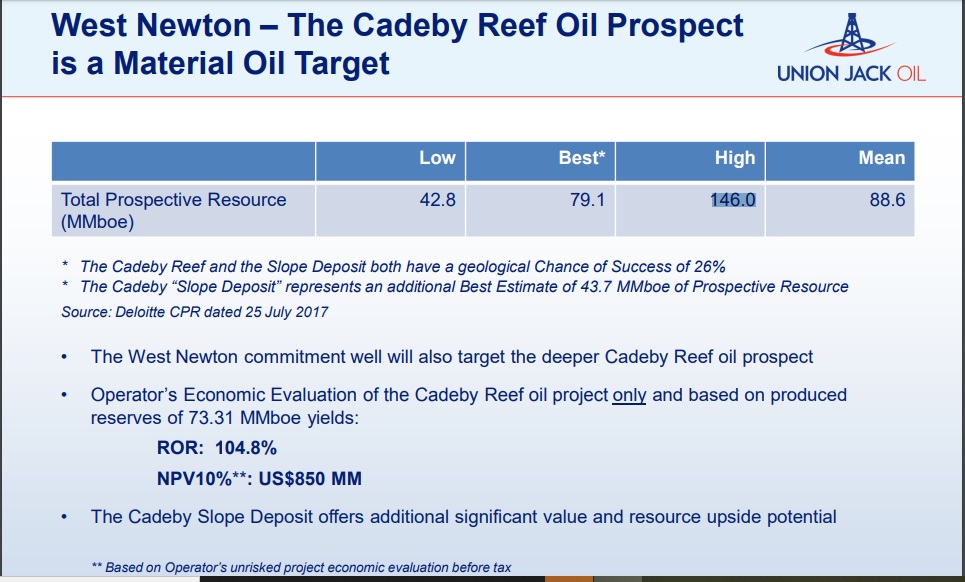
    Cores taken from the Cadby Reef are “Oil Saturated”. Raithlin and partners are quoting a “40 Metre Net Oil/Condensate column” just under the gas cap, with an expected “70-100 million barrels from the 40 Metre Oil/Condensate column”.

    One has to question why this information has been given to Corporates and not the retail hoards? Why has none of the above been explained via RNS?

    Further down in the report it states thus: “Due to the environmental sensitivities <sic> from the operator (Raithlin) regarding the Oil Discovery <sic> high alert from the anti-frac contingent”

    It really does take the biscuit when corporates are being briefed behind the scenes of an OIL DISCOVERY let alone a Gas Discovery, while the great unwashed are left in the dark to scrabble around trying to read the runes.

    How many investors have sold out on the lack of news flow in RNS’s? Every thing I’ve read in this report has been supplied to the corporates by Raithlin and the partners, yet, I challenge any one to find that information in the RNS’s of Reabold Resources (AIM: RBD), Union Jack Oil (AIM: UJO) or by Raithlin. Yet this ‘Privileged Information’ has been supplied freely to the corporates by the Operator and the management teams of their partners. And these fookers are targeting “a 3x return on 0.25p initial investment”

    The playing field should be level. Certain groups shouldn’t be briefed while others are kept in the dark.

    We ALL now know. Those behind the scenes believe, there’s an Oil Discovery underneath the Gas Discovery on site at West Newton. (The Gas Discovery itself is a company maker). So, with the well about to be ‘perfed’ tomorrow & Tankers on standby isn’t it time both listed partners coughed up exactly what they’ve been telling Corporates behind the scenes?

    Your duty is to your shareholders not a rag, tag, bag of anti-frac protestors who regardless of what you try to do would still be there. 

    Potentially The Biggest Oil, Gas & Condensate Discovery in 50yrs, second only to  Wytch Farm.

    Of course there’s always a risk regardless, it’s O&G, but knowing what’s being quoted by the corporates gives us all a better understanding when it comes to making our decisions. Information is key….

    Viva!


    Dan


  • #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    There’s a ‘hefty‘ lot of  Reabold Resources (LON: RBD) investors/traders out there, awaiting news on the company’s up-coming drills. Wick & Colter. If you don’t know what those drills are then I suggest you get researching because unlike certain other UK Onshore Oilers the RBD drills (Offshore UK) are the real deal. A ‘Roll of the dice’ with a decent chance of success (COS) on BOTH drills, particularly Colter. Which, once they actually get to rig ‘mobilisation stage’ will push this SP much higher. I personally hold some stock here, so am always on the hunt for information. The problem is the company are not releasing the news. Good or bad I publish what it is. You can moan all you want but it’s better to know what’s going on than not. It’s how you make money and it’s how not to lose money. It was pencilled in for a 12 noon release but I’ve been cashiered into 12:30pm ’cause one of the ‘twittermen‘ has to finish his go-karting with the family. What a nice guy I am….  🙂

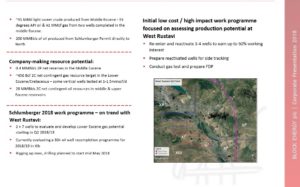
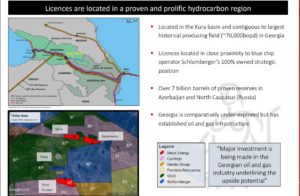
    Now it’s been a long time since I wrote on Reabold and new information has come my way via the BMD ‘sauces‘ pipeline. There’s a major whisper that this company are farming into a Georgian gas asset which is ‘controlled’ by, the soon to IPO, Block Energy. Fortunately I’ve managed to get my hand on not one, but three Block Energy prospectus’. The Georgian gas asset is flagged up as “Substantial potential from 608 Bcf 2C gross unrisked contingent gas resources at West Rustavi, analogous play being tested by Schlumberger in 2018 and 2019 on adjacent licence”

    This is more good news if it comes to pass, as it further flesh’s out RBD with another potential quality licence farm-in. A value driver.

    In the constant hunt for good returns, Reabold, sub 1p, could provide excellent returns. The SP could hit 2p/3p/4p/5p dependent on how successful they are. It will almost certainly break through 1p soon enough.
     

    Fully funded with a big following and an even bigger following waiting on the side-lines to jump in once the drills start to crystallise as a reality. The placing has been done so unless they’re running a ‘double bluff‘ holders should be able to sit tight and wait for the move upwards. Of course the placing flippers are still at work exiting, however most of them will now be out. Good place to start researching is HERE
    This is going over 1p soon enough. The only question is when? Not if! But as ever do your own research etc. Remember I hold stock as such I could be construed as a Rose Tinted Spectacle wearing leftie… 🙂


    Viva


    Dan


  • ENCORE. Cladhan/Catcher. A thought here!

    The Reuters Building in Canary Wharf, London B...
    Reuters UK

    As previously mentioned here Premier are known to be discussing Encores Catcher operators’ licence and greedily eyeing their stake.

    However there are now two schools of thought currently being discussed here in the city.

    The recent Cladhan drill has certainly put the wind up Premier vis-a-vis Encores’ Catcher stake.

    The news from this end is that Cladhan now puts Wintershall in the driving seat for a possible takeover of Encore bearing in mind that Wintershall are tied into the Catcher discovery with a 20% interest. (See Reuters link).

    Premier will now know that Wintershall are the front runners in any attempted takeover/asset sale the best that Premier can hope for is an Encore sale of Catcher if Premier become the operator of Catcher. Now this can’t happen until the full oip ,which is expected to increase, is known.

    The Wintershall interests in Catcher and Cladhan (which again is expected to be at the top end of the 200 million and will probably surpass it) given Encores raison d’etre must surely add up to at the very least an asset sale to them with the cash being returned to stock-holders via a special dividend. The more likely scenario is a full blooded takeover by Wintershall of Encore.

    So goes the thought here.

    There could quite literally be a bidding war here for all or part of Encore.

    My advice is to hold your stock and top up on any fall.

    Encore could be handing out big cash divis’ at the very least before Xmas or as most analysts think be gobbled up by one of the above mentioned Oilers.

    Sell at your peril Massive gains are on the horizon here for those that hold.

    Daniel

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights