google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: Production

  • Saffron Energy. There’s more to come… Gas that is!

    Saffron Energy. There’s more to come… Gas that is!

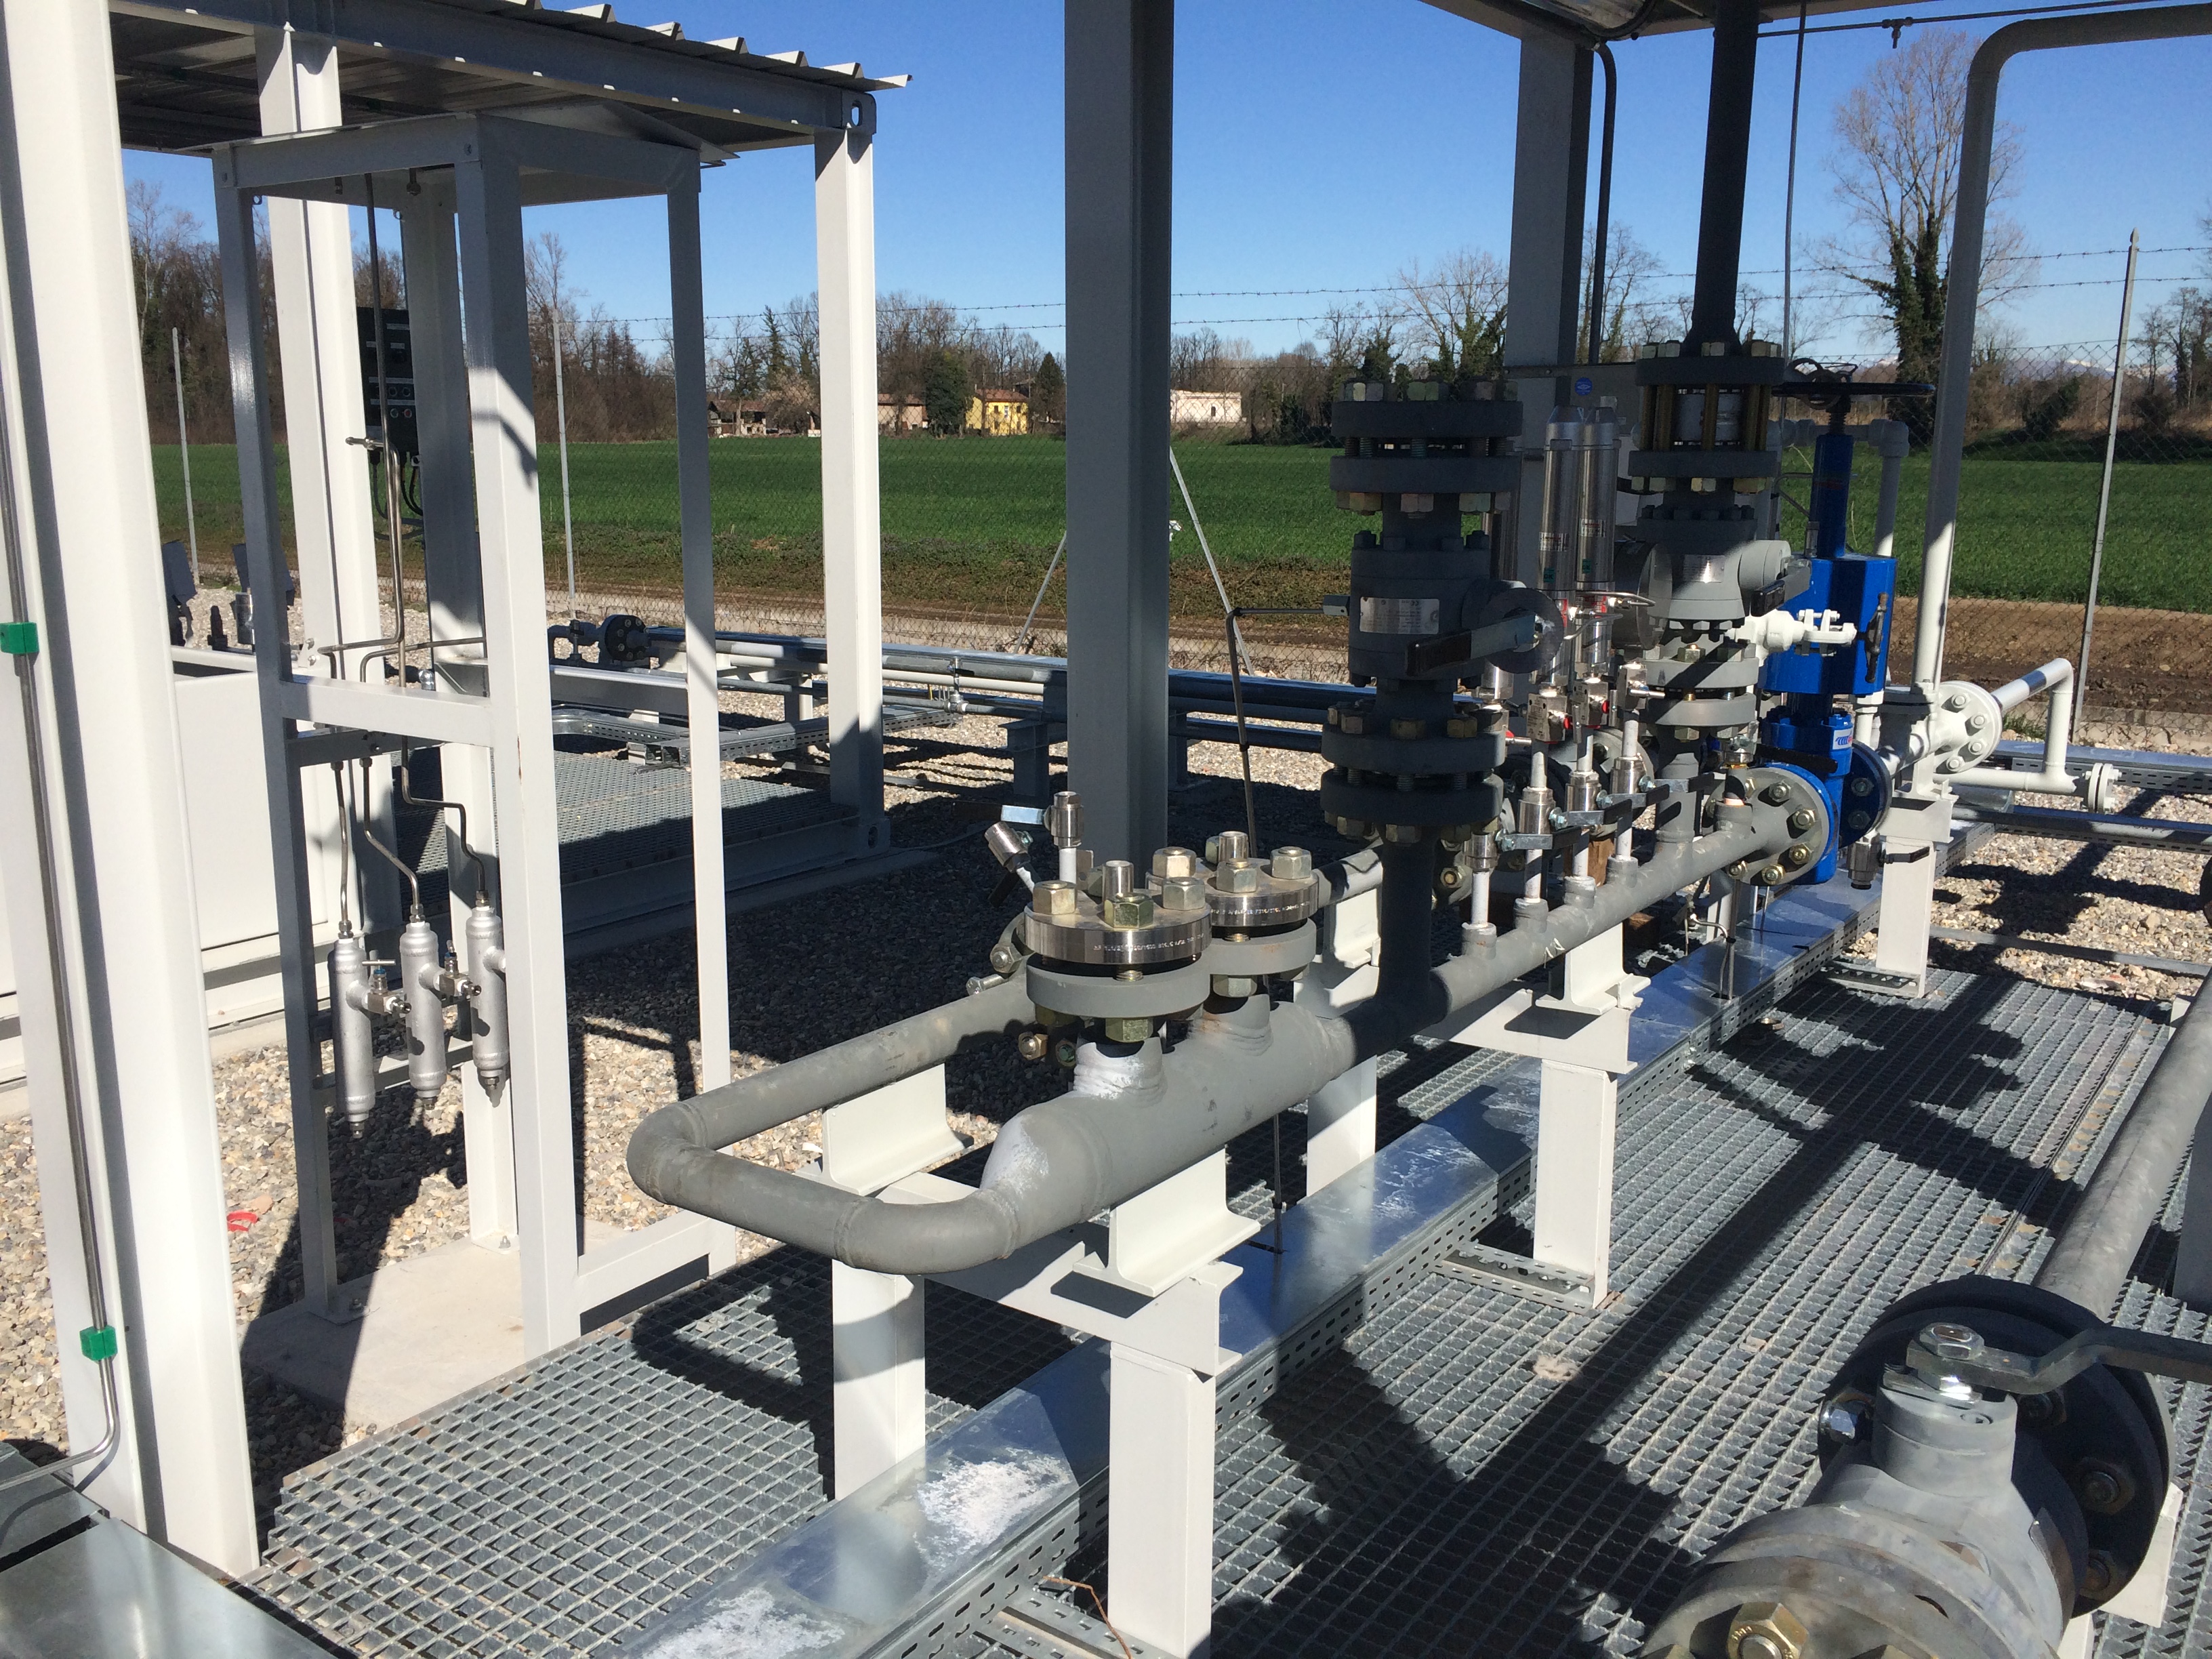
    Today Saffron Energy (LON: SRON) finally announced what was already basically known by those who follow and read www.guerillainvesting.co.uk  That is that Bezzecca gas production has now come on stream at 30,000-40,000 scm per day. This when added to 10,000scm currently being produced from their Silaro field gives them production of 40,000-50,000 scm per day. Financially this is over three hundred thousand euros per month. Circa £250,000 per month times this by twelve and we get £3,000,000 per annum in revenue. That is a phenomenal success story in the world of micro-cap oil and gas.

    SHAREPRICE
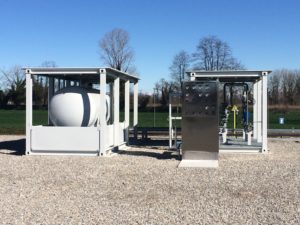
    Shiny ‘Mac Shine’. Brand new kit now producing…

    The SP has spluttered on very good news! When in actual fact it should be heading towards 10/11p etc. One of the quirks of the AIM is that impending good news is usually forward sold into by the brokers and the ‘canny’ high net worth’s. You can see it in the late trades that were being announced over the last two weeks. Profit taking. Every one is entitled to take it. So when you’re looking at Saffron or any other Company remember think ahead and don’t be discouraged by a rise that spluttered on good news. There’s always a reason for it. Normal service will be resumed once the SP settles down.

    WHISPERS

    Sources here are indicating that gas production from Bezzecca could easily surpass 50,000 scm per day as the Company work out their best flow rates over the coming weeks. Again any increase in production will significantly add to their revenue. These are a bargain at todays SP. I did hear that their CEO (Masterman) was in the UK and will be having a tete a tete with investors this week. A question I would ask if I was their would be this; “Bearing in mind what was being discussed on the recent site visit, will the 100,000scm per day be reached this year?”

    Great little producer this. Could be 12p-15p by the end of this year….

     Viva!

    Dan
  • Anglo African Oil & Gas  Watchlist/Research!

    Anglo African Oil & Gas Watchlist/Research!


    HomeApologies to all this one should have gone out on Jekyll & Hyde pre-IPO.  Unfortunately the ‘Securitate’ deemed it too sensitive and conflicted. Hence why it’s now going out on Guerilla Investing. Some minor changes post IPO… You can join the UK’S Premier Tip Sheet Jekyll & Hyde by CLICKING HERE

    Get Anglo African Oil & Gas (LON: AAOG) on your watch lists and research it! START HERE. They came to market yesterday. What I like about this one is that the placing ended up hugely over-subscribed.  It’s always a good sign. They have great potential  going forward very quickly to increase production in 2017. The management are a decent lot and have been working for two years on their IPO. The Directors intend to distribute free cash to shareholders through regular dividends, once production reaches a sustained level of 1,000 bopd and provided that oil prices are not less than USD 30/barrel. Now that’s some thing no other AIM oiler will do. It’s a good pointer. Also some of their close neighbours such as ENI have production of circa  5000 barrels’ a day from basically the same geology/horizon as Anglo plan to drill.

    Anglo currently produce 38 bopd but it is in their potential to increase this to circa 750-5,000 bopd that could push their SP much higher. Now if they get anywhere near this figure then the SP will correspondingly move upwards. Everything is now in place. Assets, infrastructure, funding and more importantly sentiment. Which is very strong. The only drawback when I first penned this piece was their website which looked like it’s came out of Noah’s Ark. Thankfully the powers that be responded to this concern and updated it to a nice healthy one. In line with the rude health that AAOG are now in.

    The assets are located in the Republic of Congo (RoC). Development of the near offshore Tilapia field could significantly increase production in the near term to circa 250/750bopd. “The company also aims to conduct exploration and appraisal of proven deeper reservoir targets to raise production to in excess of 5,000bbl/d in the medium term. The acquisition of Petro Kouilou would result in AAOG gaining extensive onshore surface infrastructure comprising: 5,000bbl storage tank, separator, in-field pipelines and other associated facilities. These facilities would cost US$15-20m if they were constructed today. Consequently, the company will not need to spend any other capex than that associated with the proposed work programme. The new wells can simply be connected and new production can brought onstream almost immediately.  Low-cost workover programme. AAOG intends to workover two wells on Tilapia field at a cost of US$300,000 which would increase production from 38bbl/d to 250bbl/d. On the assumption of a successful IPO this work would be conducted during 2017.”

    So the drivers of the share-price are many and varied. There’s existing production, increasing production, multi million-barrel potential from existing production and multi million-barrel exploration potential. The IPO price was 20p. If you can get in as close to this as possible then hold for news on increasing production/exploration. How high could it go? On any where near 5,000bopd it will rocket. On a bread and butter 250-750 bopd it should get to 50/60p. 25p-40p should be your near term target. Remember profit is the game. It doesn’t matter if you make £100s or £1,000s derisk as you go. Good solid little oiler that could/should be financially self -sustaining by the end of 2017. By that time the bopd will be many multiplies of where it is today.


    Viva!


    loginDan


  • The Ascent Of Ascent. 2017 Will be Their Year.

    The Ascent Of Ascent. 2017 Will be Their Year.

    Ascent_LogoAscent Resources (LON: AST) as most genuine objective investors/traders know we here do not constantly pump out utter shite on an hourly basis. We watch, listen, research and get to know what is going on vis-à-vis the company’s we blog on or target. It can take weeks or months to form an opinion that’s because most genuine information isn’t in the retail domain, it’s hidden from view in the Corporate World. Not for the eyes of Retail Investors.

    (Hence why when we recently exposed Mkango Resources as a busted financial flush with a history of telling whoppers to our Canadian retail investor cousins, about their piss poor paper licences and their true dire financial postion, we were proved 100% correct. MKA and their shyster advisors ‘Dubious’ Dzubinski  told so many lies it was only a matter of time before financial gravity struck.  They placed after 6 months NOT 18 months which is what every man, jack and idiot were spoon fed and greedily swallowed said turd. The red faces are there for all to see and most objective investors know BMD was spot on. Mkango, Dawes, JubCapital and the hoards of P&ders  have been strung up for all to see as PROVEN LIARS. Which is why you should stay well away from company’s that lie to their shareholders. In another 12 weeks they’ll be after yet more cash).

    Not so Ascent Resources. I was negative on them for quite a long time particularly because of the legal shenanigans and the known market abuser, Christopher Potts, who had a position. Potts made a fortune from news of a proposed Cadogan takeover, one that never came to fruition.

    Not so know. Lot of rumours swirling around from my sources that their Slovenian gas asset/s could contain substantially more gas than first thought. The commercial supply of the gas to Croatia in early 2017 and rumours of yet several potential game changers coming to the fore in Q1 2017 finally convinced me that Ascent are  a turnaround play. I can’t report those rumours until they are firmed up’.  However I can confirm that my research/sources are more reliable than most. 99% that there’s truth to them.

    The present board are starting to get it right and are making all the right noises with the right moves. CEO Colin Hutchison has been in negotiations several times in 2016 on value accretive deals. That is 100% correct. Don’t be surprised if there’s some form of ‘input’ upon AST by Henderson Global. There’s major news in the proverbial pipeline for 2017.


    Eyes on. Hold for the news.


    Viva!


    loginDan

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights