There’s never a dull moment when you’re researching investments. I’ve alluded to ‘The Secret Nomad’ once or twice in a few of my epistles. It would seem that some-one or one of the regulated companies has stole my line “The Secret Nomad”. More to that they’ve registered a domain and launched a website. It really does take the biscuit. The absolute cheek of it! I found this site yesterday when I noticed a new twitter follower….. https://thesecretnomad.com/
The Secret Nomad
But what’s rather interesting is that the articles published by The Secret Nomad (TSN) tend to show that it’s either a real or maybe a retired Nomad or some one who has a vastly superior knowledge of the Markets than most of us. Myself & SharepProphets will obviously be following TSN very closely….
What’s even more interesting is that if I know the FCA & AIM regs they’ll be all over this like a cheap suite. As will the financial press.
It’s looking decidedly grimmer and grimmer as each week passes on ‘Uber dog & ‘Uber’ ramped Chesterfield Resources (LON: CHF) This outfit are without doubt the biggest crock of shit currently on the small cap mining resources sector. They’re a mining copper play with bits of paper laying claim to ‘Copper Riches’ beyond your wildest dreams, in Cyprus.
Having spoken to ‘The Secret Nomad’ on all things standard listed and gone through every RNS and company presentation/s I can now tell you exactly what’s in store for any mug punter who falls for the ‘Greeks Bearing Gifts’ spiel currently being vomited out by this POS and their paid promoters.
Chesterfield listed on the 29th August 2017 raising £1.3M at 5p. Two months later the company was suspended, apparently a reverse takeover, so with a new prospectus they announced on 28th June 2018 that they’d raised £2M at 7.5p and had also issued 6,666,667 shares (£500K) of stock to HKP Exploration Ltd to take them over for the rights to 7 permits. HK Exploration paid nominal sums for the permits which were now incorporated into the new improved POS Chesterfield.
In September 2018 they released their Interim Results up to 30th June 2018. Where the cash balance was circa £900K. Now here’s the conundrum. On 28th June they confirmed the relisting and £2M raise. Their Interim’s are up to 30th June 2018 yet CHF state they have £900K. Have CHF ‘Jazz-funked’ away £1.1M in the space of 2 days of being relisted? If so then Whilst in suspension CHF must have been bust. The licences were paid for in shares. What was the £1.1M spent on, in two days, other than debts? It gets worse. If the above is correct then £2.4M in total has been spent over 10 months from listing to re-listing. Which leaves CHF £900K as of June end 2018, 8 months ago. The Company needs to clarify their cash position pronto!
If the £1.1M of the £2M has gone then they were burning cash at circa £240K per month up to June 30th 2018. How much cash has CHF got left? Well, on the cash burn up to June 2018 they again would be? Bust.
Invest your money here! One of hundreds of abandoned mines on Cyprus…
But let’s be generous because I’m a good guy. Lets say they decreased their cash-burn by 66% for the 8 months up to today. That means the Company have circa £100K in cash. And believe me ‘Uncle Dan’ is being extremely generous in cutting their cash-burn down by 66% per month. CHF are running on vapours. Mining, by it’s very nature, is hugely expensive. It’s hundreds of millions of pounds of capital expenditure (Capex) before a mine can be opened.
But here’s the ‘wibble in the wobble’. Being a standard listed company they can only issue 20% of their shares in actual issue in any one 12 month period, unless of course they come up with another ‘Acquisition’ and suspend and re-admit yet again….. If they go for a placing, 20% of shares are circa 12M shares. At 2p that’s one months cash-burn. At 3p that’s 6 weeks cash-burn. Or on the “generous good guy” figures of £100K per month 10 weeks or 15 weeks. Of course they’ll have to wait about 90 days before they issue.. There’s a very real possibility that CHF may well have to submit another prospectus and suspend. As Yoda would put it, ‘Vapours, almost certainly running them on’.
Cyprus was famous in antiquity for its copper resources. In fact the very word copper is derived from the Greek name for the island, Kupros. Cypriots first worked copper in the fourth millennium B.C., making tools from copper, which at that time could still be found on the surface. The discovery of rich copper-bearing ores on the north slope of the Troodos Mountains led to the mining of Cyprus’ mineral resources in the Bronze Age at sites such as Ambelikou-Aletri.
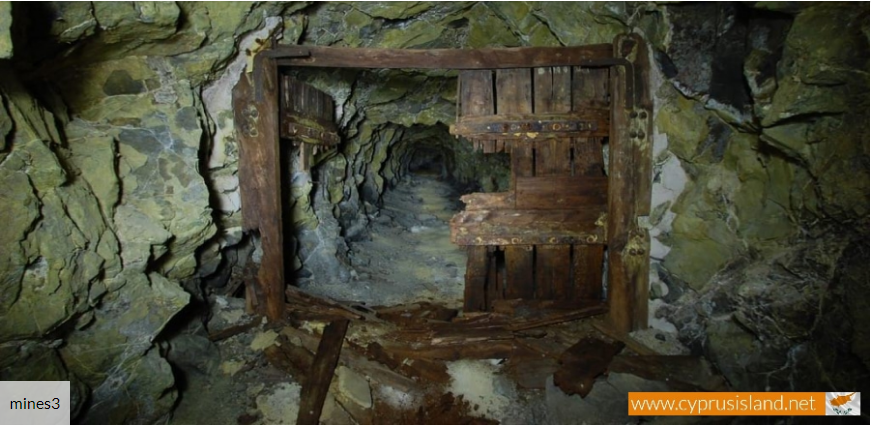
Toxic Abandoned Mine Cyprus. 1 of 100s…
Of course today after 3,000 years of mining one may want to ask exactly what’s left? Other than a few small time privateers, since 1970 the Cypriot mining industry has been in recession. Copper produced used to come from low grade dumps. That’s to say; processing of waste material from previous mining operations such as the Skouriotissa mine owned by Hellenic Copper Mines Ltd. Who’re a small scale producing copper mining company on Cyprus. In fact, Hellenic Copper Mines Ltd. are the one and only mining company on the island of Cyprus. Why is that? Answer. Because they have all the mining waste from their previous operations. In other words there’s fook all left. The only copper being produced in Cyprus comes from waste. Slag heaps. If you’d like to buy a permit and try your hand at finding the mother-lode of copper, gold or any other metal on Cyprus the cost is circa £8K per permit.
If you believe that defunct mines that cost a minimum of $200M dollops to clean up and get into production is good business then you need to send me all your money because I’m opening a gold mine at the back of a pawn shop in Didsbury….
Now we’ve all heard of that pithy saying “Beware of Greeks bearing gifts”. So here are the facts
Most mines on either side of the ‘Green Line’ (Google it) are of special scientific interest to the worlds archaeologists. That’s the Cypriot, copper industry in its entirety. There are 100’s of toxic abandoned mines. A full producing mine costs hundreds of millions of dollars to get into production. This lot have zippo cash and are about as far away from producing copper as I am from receiving a Royal Pardon and an invitation to become a ‘Lord’ of the realm. It’s a fantasy ‘Paper Mine’. Nothing more nothing less. Of course the ‘howler monkies’ will scream and scream and scream some more as reality bites.
I’ve seen it before. It’s an old worn ‘recipe’. Pick an area that’s had a history, get some spurious exploratory permits, throw in a few RNS’s, add a dash of diamond drill sampling, over-promote, give a few quid with an expenses paid jaunt to a couple of P&Ders, a pinch of ‘Total Market Shite‘, light the blue touch paper, sit back and laugh as you Mine the City of London via Mug punters.
Having spoken to ‘sources’ on what’s likely to be going on within this POS, I can only say commiserations if you’ve been suckered in by the blatant P&Ding that’s got you to this point in your trading/investing methodology where you greedily suck up more shite than a portaloo, suction cleaning vacuum.
This so called mining copper riches story is very similar to another one. In fact you could say it’s right out of the mining play-book for ‘Suckers‘. For those of us who recall the ‘Greek Tragedy’ that was Emed Mining. I’ll tell you this. It didn’t end well… Emed Mining were, (note the word “Were) a copper mining riches beyond your wildest dreams with licences in? Yes you’ve guessed it, £8 grand a ‘pop’ permit, Cyprus…
It’s Suspension, Placing or Both. Shell value 0.60p
It’s not looking good for holders of Reabold Resources (LON: RBD). News has reached ‘Yours Truly’ from strong City sources of an orchestrated ramp & dump, pre an imminent Placing. Of course they’ll now deny it and maybe they’ll put it back a week or so. But placing they are…..
Yes folks there’s a placing on the way for a minimum of £2,000,000+. In fact they need £4,000,000 just to stand still. (Explained Below). I’ve been watching the order book price action over the last fortnight which tipped me the wink that some thing was afoot. On research now undertaken, sources and I mean multiple City of London sources have confirmed that there’s a placing on the way! Which is why some of the ‘choice’ P&Ders are quietly off-loading their positions in-order to reload up in the placing. And make no mistake a placing IS coming! If you don’t believe me then ask the one man band bullshitter Adam ‘Dubious‘ of Jub Crapital the sacked broker of ‘Lord’ @ChrisOil or the House Broker ‘Turner you over Holy Pope’. As a matter of fact ask each one of them to sign a legal binder that RBD aren’t placing. You’ll get the usual ‘corporate waffle’. That’s because they’re selling! Why? Because they’re organising the placing!
Now that’s not to say that Reabold don’t have potential, I tipped them on J&H and if you’d have listened to me then you’d have made good money. They have a decent story but that story is deliberately being used to sucker in the gullible to keep the share-price up so that they can get away another placing. Well that’s just not ‘cricket’ in my book….
The last half-yearly report stated RBD had cash in hand of £353,000. The new team of Stephen Williams and Sachin Oza raised a further £5,720,000 in 2 placings ( £3.96M & £1.76M ) which fleshed the company coffers out with circa £6M in cash. In November 2017 £1.5M of that cash was quickly gobbled up via a 35% stake in the private Oil company Corallion. Following on from that in December 2017 a further £1.5M was gobbled up in an ASX listed company called Danube Petroleum to buy a stake of the Parta Gas project. It’s the worst kept secret on the London Alternative Investment Market (AIM) that they’re also looking to bring in another asset, which if they run true to form, will cost £1M+ if we consider the same level of investment in this new asset at say £1.5m that leaves cash at hand of £1.5M. Now don’t forget that the Colter drill is being touted for April 2018. The rig for that will wipe out the cash. Indeed the deposit will do that in itself. Placing.
KILLER THAT NAILS IT!
The killer fact that nails the placing is thus: Corallion are currently in the City of Mammon trying to raise between £3.5M-£6M to fund drilling of their UK license P1918 which includes the “Colter” asset. If Reabold don’t want their 35% stake heavily diluted then they will have to come up with at least £1.6M-£2.1M in cash to keep their 35% stake of Corallion and the assets. This would then leave Reabold with a negative balance of -£590,000!
PLACING
Answer. A Casino! Where the House (Corporates) tell lots of lies…
Common sense dictates that to keep the lights on with say £1m cash at hand Reabold will need to raise at least £1.6M that’s before any cash calls from Corallion or Danube for project development and cash calls will come. Placing. To keep the company progressing its investment opportunities the company must raise £4m! Which is why they’re secretly trying to keep the SP up. Expect lots of ramptasic horse shit with denials from paid promoters. Then a placing.
Shares are trading circa 0.65p which gives a market cap’ of just over £10m. Cash raised will have to be at a discount which is par for the course on the AIM Casino. That means a potential whopping 20%-40% discount to current levels.
Sell & buy back in the Placing. Because that’s what the P&Ders are sneakily doing!
Todays RNS seems to have caused quite a kerfuffle amongst the die hard Nostra Terrible Oil & Gas (LON; NTOG) Pump & Dumpers.
On the face of it getting out of a $1,300,000 liability for $100K looks like good business. Sadly this is yet another smoke and mirrors exercise from the disgraced CEO Lofgran. The CEO who loaned 150,000,000 of his own shares to YAGlobal to assist them in shorting/destroying his own shareholders & company value. You can read all about Lofgran’s despicable betrayal HERE.
Reading todays RNS it slowly becomes apparent that all of TransGlobes liabilities pre NTOG taking their 25% stake in East Ghazalat have now been transferred to NTOG & their partner Independent Resources (LON: IRG). Those liabilities are a ticking financial time bomb. Here’s why. For a company big or small to waive a hard cash $2,300,000 payment in exchange for off loading their liabilities on an asset, they sold, must mean that there are liabilities. If there were NO liabilities then they wouldn’t have agreed to the deal.
The question now is just how big are those liabilities? We know at the very least they are $2,300,000. The release of “TransGlobe from any potential warranty and indemnity claims, which it may have had under the original sale and purchase agreement, and indemnifies TransGlobe in respect of any claims, which may arise from TransGlobe’s prior ownership of East Ghazalat.In return TransGlobe has agreed to forgo the outstanding $2.3 million balance on the Loan Note and any claims for accrued interest since completion of the acquisition in October 2015.”
Looking at it from TransGlobes perspective they are now totally out of the frame on liabilities that could come in at tens of millions of dollars! And liabilities there must be because common sense dictates that TransGlobe would not give up $2,300,000 in cash if there were none. A smart piece of business on their part and yet another act of desperation by the cash strapped Nostra Terra & it’s cash strapped partner IRG.
So here’s a few questions for Matt Lofgran. How big are the liabilities you’ve just indemnified Transglobe from? The liabilities start from $2,300,000 and as with all unknown liabilities in the oil and gas sector it most certainly is much higher than $2.3M! It could be in the tens of millions of dollars which is why TransGlobe agreed to todays deal . Let’s take a guess. Will you be booking in those liabilities on the next set of accounts? Answer NO. Another question; Egypt has a controlled currency. Why have you not informed the market that any cash coming from Egypt is paid in Egyptian pounds and cannot be converted into dollars unless the applicable State/Ministry authorise such?
Mired in debt, no production money, rotten business practices and a CEO who helps to short his own company. Stay well away from this POS.
Once again yours truly has been proved 100% correct. We predicted that as soon as the consolidation was completed over at Nostra Terrible Oil & Gas (LON: NTOG) that the pump & dumpers would be out en-force and the company would then revert to type and begin the usual raft of dilution and placings. That raft of placings and dilution has now begun in earnest. There will be more placings and more dilution. That is 100% guaranteed by the Nostra Terra ‘form book’.
The pumpers and dumpers, who are acting on information given to them by the company and with the company blessing, always use the exact same modus operandi. Which is thus; Pick a small cap company desperate for cash. Contact the company, broker, nomad and their PR and begin a dialogue, get others onside to push it and begin chatting about it on twitter, email, mobile, texts, London South East, ADVFN, etc. They then Flood the chat sites with various fake accounts, bombard twitter with wild predictions and shite. Get it on sharepickers, a few tinny podcasts, articles on one or two small blogs etc. Organise a shareholders piss up and jobs a ‘good un’. It’s always the same. You can see it in real time on twitter. Every stock these fookers write about is the best thing since the invention of the wheel. Blag, Blag Blag…. The truth of AIM is that there are only a small number of genuine resource stocks worth looking at. That fact in itself is the truth that exposes the continual lies shat out on a daily basis by the pump and dumpers.
Mike Whitlow the notorious liar and head pumper and dumper, receives payment from some of these companies. The company he uses is this one Volant Services, http://www.bizdb.co.uk/company/volant-services-vsl-limited-09759614/ where he describes himself as a ‘financial consultant’ the emphasis on CON. To form a company which is unregulated and to state you are a Financial Consultant is a criminal act https://www.the-fca.org.uk/consumers#scams-67211 Whitlows’ professional credentials? He worked in the water treatment industry. A sewage worker.
They are low level conmen. Traders/Investors should tread very carefully when dealing with such people. As for those CEO’s daft enough to align themselves with such low level conmen, remember this, you ‘reap what you sow’ and that is all too often share holder discontent and revolt.
Today we learned that Matt Lofgran, CEO of NTOG, has yet again diluted and raised £250,000. A keep the lights on placing while they await the cash from the sale of Chisholm Trail and the disastrous Egyptian East Ghazalat production revenue, that has still not landed. What’s galling genuine share-holders is that the sale of assets such as CT, which has had millions upon millions of dollars spent upon it, has been sold off at a huge loss. There’s growing evidence that more assets may have been sold off without market notification. NTOG should come out and clarify share-holder concern that other assets have been sold and not RNS’d. After all if they were announced via RNS when bought then they should be announced via RNS when sold.
I used to have a good relationship with Mr. Lofgran, who I still believe is a good guy, sadly the way he was cosying up to the Mike Whitlow (a.k.a Doc Holiday) pump and dump gang that operates on twitter has now lost the support of myself and many others. Basically what happened was that Whitlow was beginning to dictate to Matt what he should do. In one instance he demanded that Nostra remove their logo from a website that CaliforniaJoe and ABM McKinley (2 Good Guys) were trying to build. Lofgran contacted the guys and told them to remove the company logo. That for me was the last straw and I withdrew my support for the company and sat back to watch it burn, as it is now. In fact we later found out that Whitlow had contacted every company that these guys were working with, making scurrilous, malicious accusations of a sexual nature and drug dealing which were wholly untrue. They were malicious and without one shred of fact whatsoever. Lies. The tirade of abuse from Whitlow on twitter ended up with twitter banning him. Of course he then tried to set up a base on Instagram which ended up in the toilet. He then crawled out from under his rock back to twitter with a new account. Hilarious….
These are the people who are now dictating Nostra policy.
The nomad has to intervene here and should check exactly what communications have been passed through email and telephone calls. The company’s relationships with these pump and dumpers needs investigating.
It’s time Matt Lofgran realised that when you lie down with dogs you get up with fleas.