google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: stocks

  • ADVFN SHAREHOLDER ACTION GROUP?

    ADVFN SHAREHOLDER ACTION GROUP?

    The ‘Natives’ (Shareholders) of the much maligned ADVFN are getting restless. So restless that they reached out to me last Friday 22/11/2024. That approach resulted in several Telegram group chat’s and a video meeting.

    The Tele’ group has over 40 members/shareholders who stated that they’re in contact with other small time holders and have got hold of damning information of malfeasance within ADVFN. Which I took with a pinch of salt.

    One groups ‘damning information’ usually ends up being no more than wishful thinking, as in this case claimed exorbitant Director expenses. That’s not going to fly. It was a very interesting weekend, quite funny in many ways not least that they asked me to help, formalise and draft a Requisition, ‘You know the ropes Dan on how to get the job done’. Even offered a ‘fee’ and a position within the company ‘Head of RestructurIng’ LOL!

    Their lead man/woman, whose identity and holding I have confirmed via the actual ShareHolder Register they provided, (No mean feat in itself to get hold of) came across as a decent individual. I did give them one tip. Don’t organise on ADVFN chat BBs and for fucks sake never name your source on the ‘inside’. Loose lips sink ships. Fortunately that dies with me. Lesson learnt.

    Today’s 5% drop in the SP will no doubt add fuel and more members to the Action Groups cause. But is that ’cause’ a lost cause?

    I can vouch that the Group certainly has enough stock to call a Requisition, but that’s far short of ADVFNS’ Executive, family & no doubt ‘friends’ holdings of at least 30%, so it’s an upward struggle, but there are, this is key, other ‘Malcontents’ and just over 28% of stock ‘not in public hands’. So theoretically there’s 6o% ish of votes out there. That would need a huge concerted push of a ‘clandestine nature’ to reach out and pitch your ‘Antidote’ to the current ‘Malaise’ engulfing the company and it’s share price. They certainly have the stomach for it. However traipsing round the City of London, and beyond, pressing the flesh campaigning for votes is time consuming.

    I’ll be meeting them in person next week in the City of Mammon…


    Stay tuned…

    Viva

    Daniel

    x

  • Balochistan The Last Great Onshore Oil, Gas & Mineral Resource Play On The Planet…. Coro Energy *BUY*

    Balochistan The Last Great Onshore Oil, Gas & Mineral Resource Play On The Planet…. Coro Energy *BUY*

    I guarantee 99% of UK O&G traders/investors have never heard of Balochistan. Indeed having just read some of the BB loons I’m changing that to 100%. That is about to change. Balochistāns’ capital is Quetta it is by land mass the largest province situated and the westernmost province of Pakistan, bordered by Iran to the west, Afghanistan on the northwest, Khyber Pakhtunkhwa and the Punjab provinces northeast and east, by Sindh province on the southeast and by the Arabian Sea on the south.

    It’s the last great onshore oil, gas and mineral resource play left on the planet. That is a fact. The province POTENTIALLY contains huge Oil, Gas and Mineral Resources. Estimates vary from 6 billion barrels of oil to 75 billion with gas in the hundreds of TCF. It’s the main reason why the Chinese have spent $40 billion constructing the Chinese Pakistan Economic Corridor known as the CPEC, as well as financing and building the port of Gwadar taking a 99 year lease to operate it. Think about that…….. Or better still google the ever shifting sands of Geo Political Alliances currently slugging it out on the world stage, seeking control of the earths resources. Make no mistake Balochistan is now coming into play and that play is huge. 

    Now lets get down to the UK Privateer Coro Energy pantomime: “O yes they are. O no they’re not in negotiations”,  currently doing the rounds on the BBs, Twitter, and Financial Forums. Are we to believe anonymous posters or do we believe sourced articles circulating in Pakistan/Balochistan as well as UK’s Upstream Online?

    Occam’s Razor: If it walks like a duck, quacks like a duck, looks like a duck, it’s a duck. There is no doubt that Coro Energy are in negotiations re O&G licences in Balochistan. At what point those negotiations are at isn’t known. What is known is that Coro must have physically been in Balochistan/Pakistan and held high level ministerial meetings as well as meetings with virtually all the main Pakistani O&G companies, if it hadn’t have happened it wouldn’t be reported in over 10 different Pakistan Newspapers/Journals… Just because it’s written in Urdu doesn’t make it any less valid. It’s happening.

    The article in Upstream writes that Coro are seeking Joint Ventures one of them is purported to be a 100Million barrel of oil with 850Bcf of gas ‘stranded asset’. If that is even half correct the financial implications of such a tie up would catapult the Coro SP into multiples of multiples. We’re talking literally billions of dollars in production. The kicker is, subject to Due Diligence, a stranded asset has already been discovered. There’s no uncertainty: the hydrocarbons have already been found

    I’m thinking out loud here. Going back to the GKP days. Gulf Keystone managed to manoeuvre themselves into Iraq/Kurdistan a region beset by a full scale ‘Shock and Awe’ USA lead war. One of the main movers in GKP was Ewen Ainsworth. We all know the story and the meteoric rise in the SP of GKP. Ainsworth is a board member at Coro Energy. Balochistan doesn’t have the instability of  full scale war, what it does have is internal disputes between State and Federal governments on the share of Mineral, Oil & Gas resources, with a very low level local insurgency that’s on its last legs. With the appointment of a new Balochistan Chief Minister who has made it clear that it’s time to develop the provinces mineral/hydrocarbon wealth, Ainsworth is probably worth his weight in gold. 

    There’s literally 1,000s of oil seeps all over the Baluchistan region. So much so the locals often come across them. This video is well worth a watch.

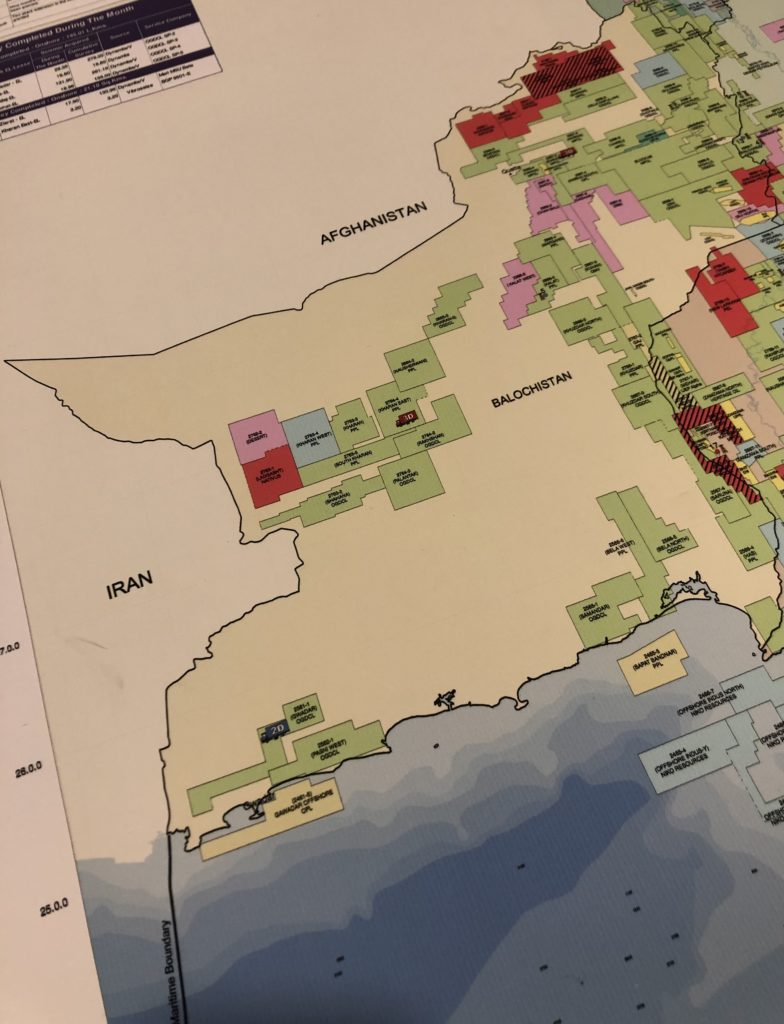
    Baluchistan Licence Blocks
    Current Balochistan Licences

    There’s nothing on the AIM, and hasn’t been for several years, that has caught investors imagination, mainly bread and butter plays. Balochistan is totally different it is huge. Whatever the true state of play of these negotiations is, any deal or JV signed has the potential to be earth shattering especially if the oil is already there…

    The driving force behind Coro is James Parsons and it is JP who has travelled, literally 100s of 1,000s of miles every year seeking deals trying to bring value back for share-holders. To go where no one else or any company would go is impressive. It takes guts. No CEO should get an easy ride but to search the globe year after year all the while being hounded by disgruntled BB howler monkies can’t be pleasant. The tenacity of JP should be applauded. This, if it comes to pass, is a company maker.

    Coro may be on the verge of entering the last great Onshore Oil, Gas & Mineral Resource play on the planet. 10% 25% 30% of any deal OR JV, if struck, would be transformational. To put it into context 1TCF of gas is 166Million BOE. At a $76 a barrel that’s over $10 Billion dollars gross. 25% of that is what? The market cap of Coro is circa $8M.

    This SP could motor upwards over the next few months especially if there’s a JV with a stranded asset. Currently trading at a third of a British penny. Short term 3p, 5p 10p isn’t out of the question. If there’s a deal on a multi billion dollar stranded oil/gas discovery we could see 50p on production. Remember GKP? Of course I’m now a shareholder.

    Any thing under a penny is an absolute steal!!!


    Viva

    Dan

  • West Newton Update: 150M -350M Barrels of oil/gas?


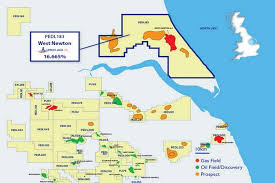
    The West Newton discovery is now on track to be the largest UK onshore discovery since 1973,  (Wytch Farm). This is huge, of National importance to the UKs energy security. The B-1Z well encountered a gross 62 metre hydrocarbon bearing reservoir interval in the primary Kirkham Abbey target formation, as of now the declared ‘scores on the doors’ are an oil/gas column of at least 118 metres, significantly exceeding previous observations.

    Lot of information will start to filter through over the weeks and months, the difficulty is that you have to sort out the wheat from the chaff. The big question is how does this latest discovery convert into barrels of oil? That’s the question yet to be officially confirmed. But make no mistake Rathlin and the partners have done the calculations. As soon as production casing has been run then I’d expect news. Possibly even before..

    However sources, indicate that the West Newton players believe that the oil/gas in place will significantly increase. Reservoir/accumulation on this discovery all but nails it! When company’s tell you that they’re sat on the biggest onshore UK discovery since Wytch Farm then I’d tend to believe them!

    The range of the barrelage, which is obviously unconfirmed and subject to all the usual caveats as per my last article, is 150M BOE up to 350M+ BOE. Now regardless of where the needle eventually settles those numbers are phenomenal. 

    As for will it flow? Does a bear shit in the woods? Enhanced porosities of over 14%. observed on wireline logs, says it will. Plus I’m hearing that this discovery is more oil than gas. 

    West Newton is a multi-billion dollar play now. So expect some predatory action round about or just before Extended well testing….


    Viva!


    Dan


  • NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    NUOG: ‘Hans Christian Andersen’ The Emperor’s ‘Nu’ Clothes……

    Commenting on stocks and shares can at times feel like a character from a Hans Christian Andersen tale, one in particular, “The Emperor’s New Clothes” springs to mind every time I read or see the utter shite constantly pumped on social media by various shysters on both sides of the fence, corporate and retail.

    It doesn’t take a genius to see the metaphors from fairy tales played out on City of London listed companies by traders and corporates alike who rely on ‘greed’ to blind ‘common sense’. The target being lumpen-proletariat small time mug-investors or as I call them ‘the meat in the liquidity sandwich’. The goal is to push the ‘tall tale’ using various ‘ruses/ploys’; such as ‘behind the scenes briefings’ to certain well known P&D merchants who take a position as well as small fees with ‘warrant packages’ then go out heralding the news of riches beyond your wildest dreams….

    Which brings me on nicely to Nu-Oil & Gas (AIM: NUOG) the current nudge, nudge, wink, wink is in full flow not least on the BBs and twitter sphere. NUOG are a shell they have absolutely no value whatsoever other than there listing value. The old Board of Directors are being paid out, then kicked out, with a new team set to come in post GM ratification. The ‘new deal’ is deliberately structured in such a way that a select group of Novum placees (no more than 4/5 individual connected investors) are taking 1,000,000,000 shares of stock at a 50% discount to today’s SP, while a newly formed corporate entity holds £2,500,000 of loan notes (again at a 50% discount) to flip out as and when you ‘the meat in the liquidity sandwich’ are buttered up into believing in ‘Fairy Tales’. Mugs buying in at 0.075p are paying a 50% premium to that placing and loan note package. £3,000,000 will be flipped out into the orchestrated rise. A rise that will be predicated on a ‘hope value’.

    If by now you haven’t worked out the implications then let me spell it out. You’re starting a race with a handicap. You can never beat the corporate flippers because they have a 50% head start with access to the news flow. If today you were 20% down on your stake bought at 0.075p they would still be 30% up. It’s a race you can never win.

    ‘Weaver’ Fumagalli?

    The company holding the £2,500,000 loan notes are C4 Energy Ltd. That paper company is the brain child of one Marco Fumagalli (Continental Investment Partners, Sound Energy, Coro, Echo) and Mr James Parsons (JP) (Sound Energy, Echo energy and Coro). Both are connected at the hip as is Mr Andy Dennan proposed director NUOG, (current CFO & Director CORO, Sound Energy Holdings Italy Ltd, Alpha Growth Plc, Baron Lux LLP). I know them all, have met them, broke bread with them and talked all things O&G with them. They’re decent people in their own way. But as corporates go I wouldn’t trust them with a ‘birds nest’. They are ‘corporate bastards’. NU-OIL, at this stage of its evolution, isn’t about finding oil or gas in Cuba, Mexico or some far field of a foreign land that’s forever England, it’s about corporates playing the system using a tried and tested method to make money regardless of finding oil or not. 

    …..  ‘Weaver’ JP? …..

    All of the above have made substantial sums of varying degrees, of a reputed £200,000,000 million generated from the Sound, Echo and CORO ventures. The largest slice of the pie going to the moneyman who finances the companies: Fumagali/Continental and their various offshore exotic mechanisms.


    The ownership of C4 Energy wasn’t disclosed in the RNS of 2nd October 2019. That omission was deliberate. It was a calculated ploy to set the NUOG shareprice to spike in an attempt to replicate the fantastic gains of the early days of Echo Energy. Pump and Dumpers were briefed to scream it from the rafters. It ultimately failed. 

    Sadly all three companies Sound, Echo and Coro ‘ultimately’ bombed. Now that isn’t a critique of any wrong doing. Far from it. In the real world the best any investor can ask for is a company does what it says on the tin: i.e. They get their licence, and drill it. All 3 companies have done exactly what they said they would do. They have ran and continue to run within the rules and regulations. On the whole their biggest failure has been geological and it’s geology that determines financial success or failure for shareholders. However it’s not the geology that determines success or failure for corporates it’s selling heavily discounted stock into ascending share prices.

    The whispered Cuban licences for NUOG are a fantasy. One only needs to do what Liargas did with his ‘Fairy Tale’ and speak to the British Ambassador to Cuba who explained that O&G exploration in Cuba was 15-20 years away due to the Geo-political situation vis-a-vis the USA. Exit stage left Liargas from Cuban oil into cannabis.

    Based upon historical performance of those now taking control of NUOG if it runs true to form then it’s nothing more than a corporate carve-up pre change of control…….

    So, the questions are many. Too many for this blog. But questions will be put to those running the show and answers sought next week. Such as: Since when did an Oil & Gas CEO (JP) decide that issuing vulture finance packages and organising a select placing at ‘mates rates’ to mates, become more productive than finding oil and gas?

    Viva


    Dan


    N.B:  Kejserens nye klæder) is a short tale written by Danish author Hans Christian Andersen, about two weavers who promise an emperor a new suit of clothes that they say is invisible to those who are unfit for their positions, stupid, or incompetent – while in reality, they make no clothes at all, making everyone believe the clothes are invisible to them. When the emperor parades before his subjects in his new “clothes”, no one dares to say that they do not see any suit of clothes on him for fear that they will be seen as stupid. Finally a child cries out, “But he isn’t wearing anything at all!” The tale has been translated into over 100 languages.

  • Reabold Resources ‘Project Wallace’

    Reabold Resources ‘Project Wallace’

    Tip: I often see and hear this: "Know The Game". Let me tell you something, anyone who consistently espouses this shite is 'at the bollox'. Investing/trading at any level isn't a 'game'. It's deadly serious. Those that tweet, podcast or write such shite are in the main Pump & Dumpers, who'll say and do anything to manipulate small cap' micro stocks. Using a whole host of anonymous twitter, BB accounts, DMs, Private chat, phone calls and email groups. It's easy to ramp telling 'porky pies' about crap companies you're taking kickbacks from or dumping shares into the ramp. Silence is better than bullshit.

    What isn't easy is getting your hands on quality information. Base your strategy on well sourced information. Remember losing several thousand pounds for most of us has financial consequences. Rather than know the 'game' 'Know Their Game'. Here endeth the lesson...

    There’s no a hard & fast rule, in the not so glittery world of financial commentary, but occasionally one has to make a ‘judgement call’ in the interests of transparency for shareholders, traders and investors who’re all too often kept in the dark, when really companies should be reaching out to their shareholder base and the wider market, instead of skulking around behind the ‘corporate curtain’, raising cash. 

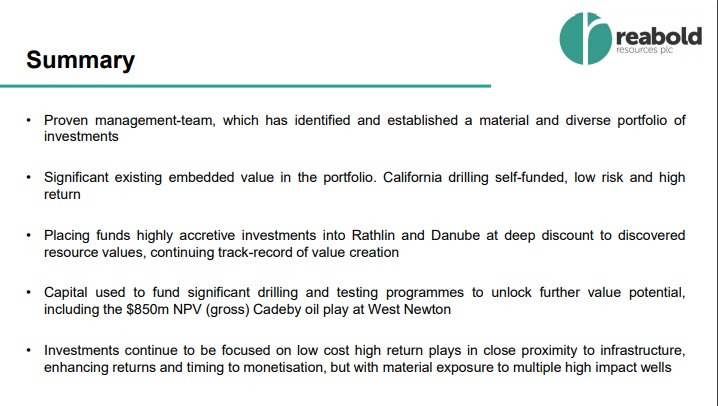
    Some financial placings actually have merit and one, if given the chance, can see the raison d’être or not. Which brings me on nicely to “Project Wallace”. Documents now in my possession confirm that Reabold Resources (LON: RBD) basically think that they’ve hit the ‘Oil Jackpot’ at the West Newton drill site.

    Project Wallace is the corporate (Stifel) Institutional overview/pitch of all licences held by Reabold, with summary’s pertaining to each of their licence holdings: Reabold California (USA), Rathlin/West Newton (UK),  Danube Romania,  Corallian (UK)


    For the purposes of this blog post I’m specifically concentrating on the West Newton/Rathlin transaction that can be summed up as thus: “$29m investment for $274.4m of additional value” which doesn’t take into account the potential value/oil from the Cadeby oil play which has a further value of $850m NPV (gross). The proposed placing price was 1.2p. That may have changed post the ShareProphets scoop and RNS confirmation. We’ll know soon enough. For those of you who wish to read the complete unabridged Stifel overview there’s a ‘Click Me’ button at the bottom of this post.

    It’s glaringly apparent that RBD and their partners believe that West Newton is a major onshore oil/gas discovery that will flow oil & gas and could net well in excess of $1,000,000,000 at $11.50c net back based upon as yet the unpublished CPR and the volume-metrics that will soon be released. The Extended Well Test is due Q4 2019, which means West Newton is gearing up, news should start to drop next few weeks or so….

    To me it looks to be the ‘real deal’ based upon what’s been going on behind closed doors however ‘Caveat Emptor’ always applies. It’s not in the bag until it’s in the bag. RBD will be fully funded with an increase in West Newton which is basically their crown jewels. UJO are already fully paid up for the EWT and have £2,600,000 cash at hand, they’ll probably sell out after the oil/gas flows. It’s known that Bramhill (CEO UJO) has consistently rebuffed offers of financial backing from several institutions.

    So, how much O&G is there? We’ll get an idea once the CPR/Volume metrics are released which should come pre EWT. A 65 metre hydrocarbon column in the Kirkham Abbey is in itself a company maker. Add in the Cadeby and it’s probably the best O&G play on the London Stock Exchange. Especially since all the Major holders have all basically ‘sold off’. That brake has gone. Expect TR1s with the inevitable deceitful ones double speaking trying to talk both companies down. Par for the course, i’m afraid.

    Once oil/gas flows at West Newton then RBD could hit in excess of 5p and UJO anything up too 2p. Of course it’ll be a bumpy ride with many peaks and troughs but that’s again ‘par for the course’ in the Oil Sector. So, now we ALL know the facts on West Newton and the proverbial playing field has been levelled. Courtesy of Dan! The Man! Whose got no hair but doesn’t care LOL!

    Good Luck


    Viva!


    Dan

  • Union Jack Oil. Their Time Has Come. Buy A Slice Of The Pie…. Here’s Why!

    Union Jack Oil. Their Time Has Come. Buy A Slice Of The Pie…. Here’s Why!

    *Take Note!  Before I start some wise words to those who read & follow: Lot of interest in emails/texts and private DMs over the last few months on why I’m not as prolethic writing/tweeting/tipping stocks every day on companies. There’s a good reason: The simple truth is this: Most of the time investing/trading is about not getting suckered into the horse-shit. It’s about protecting capital while biding ones time until a real opportunity comes along, then getting your research done. Usually it’s a company that I’ve been tracking on the watch-list for months if not years. If that company gets to a point in time where it’s a crock of shit then I write it up negatively, if there’s a real opportunity then I write it up positively. Hence UJO which I’ve been following since the Wressle discovery. The way to keep some semblance of integrity/credibility is to resist running with the known rampers/mug punters. Plough your own farrow and always remember that it’s not as these fookers say a ‘Game’ it’s deadly serious peoples liveleyhoods are at stake.

    The majority of companies never get there. Because they’re life-style companies. The AIM is awash with them. If, like me, you’ve been around for an age and a day, you know that most companies burn up. Any blogger/market commentator or financial platform that consistently writes, posts, podcasts/tweets on a daily basis nothing but ‘positivity’ on super dooper oil, tech, mining stock plays etc. Is a ‘scatter-gun cowboy’.  And should be treated with the utmost caution. No one can call 40/50 stocks in a year positively. That is a fact! If you can get 5/6 right then you’re doing extremely well.
     

    Occasionally, along comes a company that manages to get to a point in its business cycle of ticking all the right boxes. It doesn’t happen often but when it does there’s potential for huge financial gains. Such is the time for Union Jack Oil (LON: UJO). It’s a small micro-cap oiler that’s mainly under the radar, trading at one tenth of a penny (0.10p). What marks them out, as of now, is that their asset base, which is onshore UK, has the potential in the coming months of transforming them into a genuine UK oil producing company. Not many of those around these days…..

    UJO have an interest in a whole host of UK onshore licenses, but for the purposes of this blog I’m concentrating on three of the licenses that will cause a re-rate should they do what most expect them to do, strike oil and gas or be allowed to get the production going (Wressle).

    1/West Newton Gas Discovery: (16.6%) West Newton A-1 gas discovery (Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross), the West Newton conventional appraisal well is planned to be drilled in Q1 2019.

    2/Wressle: (27.5% ) Is an oil discovery that’s mired in ‘legals’. It’s a bread and butter asset that has flowed oil and gas. The estimates of oil are circa 2.1 million barrels. Wressle is expected to flow at 500bopd minimum but could hit 1,000 bopd that’s somewhere between 137-264bopd net to UJO. All going well this should be resolved in late 2019/20.

    3/Biscathorpe: The mean Prospective Resource volume for the main reservoir objective, as calculated by Egdon Resources (35.8%) is circa 14 million barrels of oil. Additionally, there’s a potential for stratigraphic trapping at Biscathorpe, which, if present, could increase the expected gross Prospective Resources to 41 million barrels of oil. UJO Own 22%. Drilling late 2018.

    Now here’s the nub. 22% of 14m barrels of oil is circa 3m barrels net to UJO. If it’s 41M barrels then it’s circa 9m barrels of oil net to the company, on The West Newton A-1 gas discovery the Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross, the West Newton conventional appraisal well is planned to be drilled in Q1 2019. That’s circa 5MMboe net to UJO. On Wressle which is a discovery and has already flowed there’s 2.1m barrels of oil, 27.5% net to UJO that’s 550,000 barrels.

    In total (not including their small producing assets), over the next few months, at the top end of the numbers Union Jack Oil are involved in three licences in play for circa 75,000,000m – 47,500,000m barrels of oil or equivalent. That’s more oil and gas than any UK onshore company currently listed on the London Alternative Investment Market (AIM). There is NO company that comes close to them.
    Their share of the oil and gas is bigger than two of the biggest over-hyped POS’s currently deluding investors with fantasy claims of billions of barrels of oil in the Weald. While producing zippo! (UKOG and Angus Energy).

    The difference in the SP and the market capitalisation is astounding. As is the quality of the UJO licences which by far out-strips UKOG & Angus Energy’s. It is only a question of time before they come on the radar and out-perform, SP and oil production wise, the Liargas plays and what’s more UJO are a conventional oiler. No fracking, all environmental regulations are adhered too.

    UJO have quietly manoeuvred themselves into a potential winning hand. What’s more their recent placing takes out the spectre of imminent dilution. They’re fully funded going forward. Debt free. It doesn’t get any better than this for a micro-cap play.

    How high can they go? That’s the million-dollar question. On the run up to the Biscathorpe spud if investors get behind it they could double or triple in value. If they strike oil at Biscathorpe and bring in the West Newton discovery revenue will start to flood in, then 0.50p-1p isn’t hard to see. Could hit 2p we just don’t know.

    One thing is certain the SP will rise the closer the drills get and interest starts to pick up. Get a slice of the pie while it’s cheap, because ‘campers’ when it’s 0.30p you’ll be cursing!

    Viva!


    Dan


    Nota Bene: I hold stock in UJO. Not that it’s any of your business!!!
     

  • Online Blockchain. It’s all coming together. I Buy for the Boom!

    Online Blockchain. It’s all coming together. I Buy for the Boom!


    Online Blockchain have been quietly going about their business and news has been and is being dampened down, particularly on their mining operation and the on-going negotiations that are always just an RNS away, there are deal/s in negotiations. Such as the Gibraltar Stock Exchange negotiations that were never RNS’d. OK that deal didn’t complete but somewhere along the line a big deal will come off. That is why I hold this stock.

    It’s already spiked to £1.85p. And it will no doubt surpass this as the crypto nerds focus in on OBC. (Oil & Gas traders don’t understand this market and should stay away).What those deals are will become apparent IF they’re signed up. Remember, the Chambers ethos is that only ‘signed deals’ are RNS’d, negotiations are not disclosed. (More of which I’ll go into later in this blog).

    OBC have now launched five crypto-coins. Buenos, Brazio, Manila, Veggie and the original Plus1 Coin. What most investors haven’t realised is that those five crypto currencies are seeds and look set to net OBC circa $1,000,000+ in Bitcoin forked coins over the next year or so. Each crypto, before it’s launch, is pre-mined. That’s to say that up to 20% of each coin is mined by OBC. I know that Buenos, Brazio Veggie and Manila coins were pre-mined. Now here’s an accountant’s question. Plus1coin has a MC of $250k. So hypothetically now there’s a $50k crypto currency asset. When it goes to $1M that’s $200k. That scenario is the same for each coin that OBC launch.

    Like all seeds time is the key. Bitcoin took 8-9 years before it spiked at $20,000 per coin. It’s now $6,000 per coin. The secret of crypto coins is to create a use for the coin. Each of the OBC coins has a user case. Therein lies the development cycle to the increase in value. Each Crypto currency has its own unique development cycle which can take time to work through. You must launch a Crypto that has a use, such as the Brazio coin, that’s been developed for the Brazilian capital markets and each Crypto has a wallet that brings revenue into the company. The more it’s mined the more they make. The Brazio Coin has only recently been released on the Brazilian market and is now tradeable on the Brazilian Crypto Hub Exchange.

    Now it has been quite some time since I updated on Online Blockchain (LON: OBC). That’s because information is hard to come across as the Board run a very tight-ship, for reasons best known to most of the quality disruptive techno’ companies they navigate carefully around the City of London, not wanting to draw the attention of the regulators and banks etc. That’s because this technology, Blockchain, is slowly creeping into the financial markets. People and industries especially the Financial industries are nervous about protecting the hegemony that is being slowly eroded.

    As for the deals and the way forward for OBC I do know that there’s certain pointers I use, whispers of negoiations, Coin launches, Wallets, Revenue, Warrant exercises, Hash rates etc. One such whisper is that they may have been approached to launch on the Canadian market. That’s important. If OBC take a listing in Canada (TSXV) then this SP will go through the roof, again. Why? Because Canada has two sectors that are world leading, one is Medicinal ‘Weed’ the other is Blockchain/Crypto. The Blockchain companies listed in Canada do so because the Canadian Investors are the most ‘savvy’ in that global sector. The UK Crypto/Blockchain Investor/writer really doesn’t exist. It’s a ‘Hodge Podge’ of traders/bloggers and ne’er-do-wells. People who don’t understand how the sector works and why it’s so boomtastic. I recently had a ‘JawJaw’ with a certain well-known financial writer, who admitted he knew fook all about ‘Blockchain and disruptive tech’. That hasn’t stopped the self-confessed ‘dilettante’ from opining on OBC. Lot of dis-information has been spewed out on the Chambers Crypto/Blockchain play. From people who admit they don’t have a ‘Scooby Doo’ about the tech’. Their ignorance has been my gain. I now hold circa 100,000 shares. I await the boom and boom it will…..

    At the time of writing the SP is circa 40p. That’s the basic reflection of the fundamentals but not of their potential to multi-bag on any given RNS.

    Get researching and use the opportunity to learn. It’s better to be in front of the Blockchain wave instead of chasing it.

    Hold for news. My spider senses are tingling. News will come.


    Viva


    Dan


  • Nostra Terra The ‘Circus’ of Lies. Back in Town. Clown Players Exposed!

    Nostra Terra The ‘Circus’ of Lies. Back in Town. Clown Players Exposed!

    Image result for PUMP AND DUMPI’ve been sat on some of this information for quite some time, as a matter of fact since 21st April 2018. Now remember that date, (which I’ll explain later down the thread). I’ve been waiting for a big enough example of the disgraceful, wholesale lies and fraud perpetuated by the main ‘players’ to appear and yesterday’s Nostra Terra Oil & Gas (LON: NTOG) so called ‘MM short’ that has been pumped out over the twitter and BB sphere now gives me the easiest example of the many failed Pump & Dump attempts this lot have perpetuated (not only on NTOG) on the gullible investors/traders, that can be duped into swallowing the utter ‘horsepox’ the band of not so ‘Merry Men’ perpetually scream online.

    Yesterday and no doubt today, which isn’t the first and won’t be the last, there were five accounts on twitter and various accounts on London South East & ADVFN, pushing yet another Nostra Terra Oil & Gas SP manipulation. Come on down the ex-Vox booted director David (pay me, I’ll Ramp 4U) Burton, ably assisted by his ‘Clowns’ Ben Turney, Alex McKinley & Mikey Whitlow and last, but not least the NTOG shorting CEO, proven Liar and bullshitter Matt ‘scumbag’ Lofgran. All five are on twitter and four of the named individuals have separate platforms that blast out utter spurious guff, masquerading, as financial AIM market commentary 24 seven.

    Apparently, according to ALL of the above, including the CEO of Nostra there’s a Market Maker (MM) short of stock in NTOG, inferring a ‘short squeeze’. One may ask how all 5 of these chaps came to that CONclusion? Bearing in mind that there’s absolutely no truth whatsoever to this unsubstantiated claim. Just quite what a CEO is doing on twitter stating such nonsense breaks every AIM rule in the book on sensitive financial disclosures…

    Well let me tell you. On the 21st April 2018 the day of the UK Investor Show, four of the above met in a public house (Mr Burton, Mr McKinley, Mr Whitlow & Mr Turney) where they agreed, among other things, to form a ‘mutual self-help society‘ i.e. they made a pact and conspired to ‘Promote’ each other’s tweets and blogs/articles/podcasts. Sources who witnessed it also tell me that they believed they could become a force greater than ShareProphets. The deluded ‘Wannabees‘ thought they were going to take over the world of micro-‘crap’ info…… 
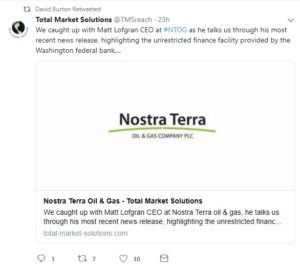
    The terms of said ‘Clown Pact’ were/are to retweet and back up each other’s tweets/blogs/news/articles/podcasts. If you check all four twit timelines, (Deletions galore post this blog)  you’ll notice an unhealthy correlation between ALL four accounts when it comes to certain stocks. Take for instance Nostra Terra Oil & Gas the piss poor microcap that cannot self-sustain without continually raising cash. It has to duck & dive via placings, warrant sales, it’s in debt up to its eyeballs, mired in legal disputes ad infinitum and has piss poor stripper well fields, which are touted as ‘company makers’. (Stripper well fields contain wells deemed economically at the end of their productive life and require constant cash burning workovers to slurp up the remaining dregs of oil left. Such wells produce a few barrels of oil per day, at best, then require shut-in for workovers etc.).

    The economics of stripper well production when combined with the cash burn of an AIM listed company to flesh out the ‘Jackanory’ has one purpose and that is to fool the mugs into trading the stock to increase the liquidity so that the company can place and keep the balls in the air. ‘Balls’ being the fat fees those running the show take! Those that assist with the bogus promotion often trade into the rises and some like Turney & Burton and no doubt the others get paid or have been paid by the CONpanys. It’s nothing short of a scam.

    The history of Lofgran is one of total failure and scurrilous lies. There is no short squeeze here. No Market Maker desperate for stock to close a short. It is sheer fantasy to enable, nay manipulate, the SP upwards for the yet again Placing that is inevitable. The shorting Shyster has been running around the City gauging the appetite for a Placing. Hence the continual ramptastic horseshit of the Band of not so ‘Merry Men’.

    The Gang of four will no doubt deny it, however using NTOG as the example just check how many tweets, blogs, articles and podcasts there’s been on this POS from the ‘Merry’ men that’s been cross pollinated between themselves. Of course it could all be just a coincidence….. Sadly, the form book on other stocks they’ve all been cross-pollinating and ramping kills that Trumpian defence stone dead. As does their ‘Meeting’ in the boozer at the UK Investor Show on the 21st April 2018. Witnessed and 100% correct!


    The ringmaster of this ‘circus of lies?’ David Burton of Tell Mugs Shite (TMS). The sad clowns perform for a few shekels……  Oh, what a wicked web we weave when we practice to…… Tell Mugs Shite! 


    Now not a lot of people knew this, but they do now!


    Viva


    Dan


google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights