google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: UK Onshore

  • West Newton: Twist, Fold Or Hold?

    West Newton: Twist, Fold Or Hold?

    ** Before I give my update, there are a few things that mug punters & genuine followers, readers need to address and that is your own personal situation and attitude! If you feel at any time, ANY misgivings on any trade or investment then move on, sell up! It really is that easy! There’s no shame in selling, it’s not a ‘pissing contest’ or a game of chicken or indeed as the pump & dumpers would have you believe ‘Know The Game’. It’s not a game, (any one who tells you this should be blocked, unfollowed and ignored). Take responsibility for your portfolio. It’s your money, ultimately it’s your call. Here Endeth The Lesson….

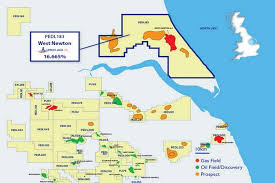
    Twist Fold or Hold? That’s the question currently on the minds of some UK traders/investors hoping for a big Onshore UK Hydrocarbon discovery at the Rathlin operated licence, West Newton.

    As of last week numerous city sources indicated that whispers (Unconfirmed) of a big hydrocarbon discovery were circulating. I tweeted this out last week. My gut tweet etc. So it’s with a few caveats that following on from that, after more research that I’m now in a position to state that West Newton has had Major Hydrocarbon shows in the Kirkham Abbey formation side track drill. I believe that the partners may be on the cusp of finalising logs, data prior to an announcement of, potentially, one of the biggest UK Onshore Hydrocarbon discoveries.

    When I say ‘Hydrocarbon’ I state that because as good or bad as I am at sniffing out information. I don’t know what the make up is. It could be any one from 3, any two from 3 or all three i.e. Oil, Gas, Condensate. I don’t have access to Rathlins data suite…. I also don’t know when the result good or bad or confirmed either way will be RNS’d. And remember there’s always a chance, as a contact of mine said that I ‘could be wrong or am being feed horse shit, by contacts’. I take that into consideration as this has happened to me 7/8 yrs ago by Evolution Securities on Tower Resources. There’s always risk regardless.... There’s no certainty until it’s in an RNS.

    But I do know 99% that the West Newton result is now known by the Operator, Rathlin and in my opinion it’s coming in!

    Make your decision/s based on your situation, don’t come howling to ‘Yours Truly’ if it comes in or doesn’t. Or if share prices rise 300%-400% and you miss it or you don’t…. Contrary to pithy epithets, Fortune doesn’t favour the brave and He who dares doesn’t always win! He who knows the outcome does!

    Twist, Fold or Hold!


    Good Luck


    Dan


  • West Newton. The Reality Is It’s A Billion Dollar Oil Discovery. Clarification For The Morons.

    West Newton. The Reality Is It’s A Billion Dollar Oil Discovery. Clarification For The Morons.

    To hold or not to hold? That’s the question being asked by share-holders of Union Jack Oil (LON: UJO)  & Reabold Resources (LON: RBD)

    There’s been a lot of piss & wind posted recently on the, Rathlin operated, West Newton major oil & gas discovery. The key to investing and even trading is to pick your entry and your exit, based on what you know as opposed to what’s being eternally spouted on social media. There’s one twitter lunatic who seems to think (Wrongly) that UJOs’ head honcho is responsible for putting in the HSE, O&G paperwork as well as ordering all the capital equipment for the imminent drill/s and any delay is their fault.

    Oil & gas drilling by its very nature is bureaucratic. It’s the Operator Rathlin who lodge ALL West Newton applications. Partners have a non operated interest.  If you have any doubts on your trade/investment in any company or in any sector then sell up and move on. It’s as easy as that. Get out, there’s no shame in selling.

    Yesterdays Rathlin update was forced due to the amount of erroneous speculation circulating on social media. 

    “Rathlin Energy (UK) Limited, as operator of the West Newton A-2 well, is providing the following update regarding the Extended Well Test.

    Preparations for the retesting of the well are progressing both from an operational and a regulatory standpoint.

    Coordinating the availability and timing of services, equipment, personnel and other aspects of operations with the requirements of our regulators is imperative.

    These activities and approvals are often dependent upon one another.

    Rathlin Energy (UK) Limited will provide operational updates via this website when appropriate.

    Kind regards

    THE RATHLIN ENERGY (UK) LIMITED TEAM”

    So with the above in mind, here’s exactly what’s going on. The Extended Well Test and site mobilisation are a matter of days away. All equipment has been sourced with a date pencilled in for the EWT, and the drilling by Rathlin of West Newton 2B could happen in concert or be very close behind the EWT. One rubber stamp is awaited from the EA. That application, according to my sources, went in last week. The usual turnaround from the HSE/EA is 14 days. So my ‘back of the fag packet calculations‘ are end of this week beginning of next. Site mobilisation and EWT are imminent. Don’t be fooled or get caught out. When the news drops the SPs are only going one way. 

    Reabold and Union Jack are fully funded for at least 18months, both have paid up in advance. There should be no placings in 2020. Especially UJO whose asset/production base are all UK onshore. Onshore drilling, compared to offshore, is way, way less expensive.

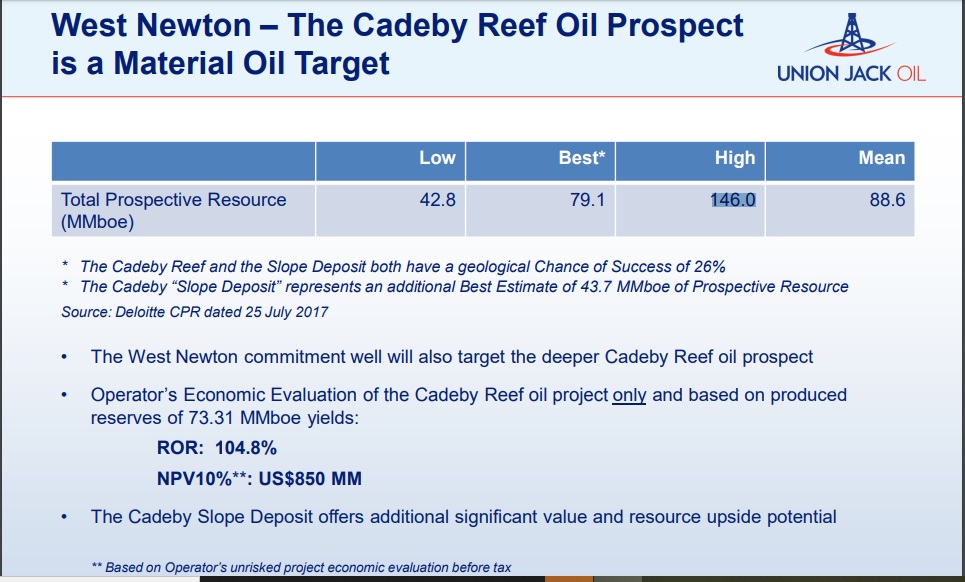
    There are at least 2 oil predators awaiting the EWT oil flow results. That means that if it flows, as expected, from the  60,000,000+ boe then there’s a real possibility, depending upon how far West Newton 2B has progressed, that the asset will be bought out by either one or both Majors in partnership, circling.

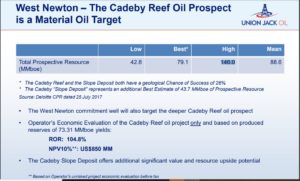
    Share-holders of both listed companies need to remember that West Newton is a billion dollar oil play:

    A major UK onshore Oil & Gas discovery has already been called by the companies. It’s of National importance and as such oil minnows or their interests get swallowed up. That’s how it works in the oil sector.

    Any investor thinking that Rathlin will remain the operator of a Major UK O&G discovery are in ‘la’ la’ land’. An offer or offers will come. That’s a given. Of course oil has to flow. There are only 2 companies i’m invested in: Reabold & UJO. That’s because both have exposure to West Newton. I’m not looking at any of their other assets regardless of how good they maybe. It’s all about West Newton for me. All the companies involved are convinced that (barring a major onsite explosion or a military takeover of the UK) oil will flow. It doesn’t get any better than that…..

    Viva


    Dan


  • Union Jack Oil. Their Time Has Come. Buy A Slice Of The Pie…. Here’s Why!

    Union Jack Oil. Their Time Has Come. Buy A Slice Of The Pie…. Here’s Why!

    *Take Note!  Before I start some wise words to those who read & follow: Lot of interest in emails/texts and private DMs over the last few months on why I’m not as prolethic writing/tweeting/tipping stocks every day on companies. There’s a good reason: The simple truth is this: Most of the time investing/trading is about not getting suckered into the horse-shit. It’s about protecting capital while biding ones time until a real opportunity comes along, then getting your research done. Usually it’s a company that I’ve been tracking on the watch-list for months if not years. If that company gets to a point in time where it’s a crock of shit then I write it up negatively, if there’s a real opportunity then I write it up positively. Hence UJO which I’ve been following since the Wressle discovery. The way to keep some semblance of integrity/credibility is to resist running with the known rampers/mug punters. Plough your own farrow and always remember that it’s not as these fookers say a ‘Game’ it’s deadly serious peoples liveleyhoods are at stake.

    The majority of companies never get there. Because they’re life-style companies. The AIM is awash with them. If, like me, you’ve been around for an age and a day, you know that most companies burn up. Any blogger/market commentator or financial platform that consistently writes, posts, podcasts/tweets on a daily basis nothing but ‘positivity’ on super dooper oil, tech, mining stock plays etc. Is a ‘scatter-gun cowboy’.  And should be treated with the utmost caution. No one can call 40/50 stocks in a year positively. That is a fact! If you can get 5/6 right then you’re doing extremely well.
     

    Occasionally, along comes a company that manages to get to a point in its business cycle of ticking all the right boxes. It doesn’t happen often but when it does there’s potential for huge financial gains. Such is the time for Union Jack Oil (LON: UJO). It’s a small micro-cap oiler that’s mainly under the radar, trading at one tenth of a penny (0.10p). What marks them out, as of now, is that their asset base, which is onshore UK, has the potential in the coming months of transforming them into a genuine UK oil producing company. Not many of those around these days…..

    UJO have an interest in a whole host of UK onshore licenses, but for the purposes of this blog I’m concentrating on three of the licenses that will cause a re-rate should they do what most expect them to do, strike oil and gas or be allowed to get the production going (Wressle).

    1/West Newton Gas Discovery: (16.6%) West Newton A-1 gas discovery (Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross), the West Newton conventional appraisal well is planned to be drilled in Q1 2019.

    2/Wressle: (27.5% ) Is an oil discovery that’s mired in ‘legals’. It’s a bread and butter asset that has flowed oil and gas. The estimates of oil are circa 2.1 million barrels. Wressle is expected to flow at 500bopd minimum but could hit 1,000 bopd that’s somewhere between 137-264bopd net to UJO. All going well this should be resolved in late 2019/20.

    3/Biscathorpe: The mean Prospective Resource volume for the main reservoir objective, as calculated by Egdon Resources (35.8%) is circa 14 million barrels of oil. Additionally, there’s a potential for stratigraphic trapping at Biscathorpe, which, if present, could increase the expected gross Prospective Resources to 41 million barrels of oil. UJO Own 22%. Drilling late 2018.

    Now here’s the nub. 22% of 14m barrels of oil is circa 3m barrels net to UJO. If it’s 41M barrels then it’s circa 9m barrels of oil net to the company, on The West Newton A-1 gas discovery the Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross, the West Newton conventional appraisal well is planned to be drilled in Q1 2019. That’s circa 5MMboe net to UJO. On Wressle which is a discovery and has already flowed there’s 2.1m barrels of oil, 27.5% net to UJO that’s 550,000 barrels.

    In total (not including their small producing assets), over the next few months, at the top end of the numbers Union Jack Oil are involved in three licences in play for circa 75,000,000m – 47,500,000m barrels of oil or equivalent. That’s more oil and gas than any UK onshore company currently listed on the London Alternative Investment Market (AIM). There is NO company that comes close to them.
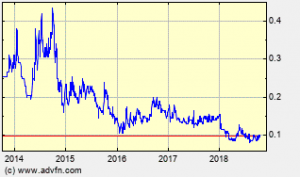
    Their share of the oil and gas is bigger than two of the biggest over-hyped POS’s currently deluding investors with fantasy claims of billions of barrels of oil in the Weald. While producing zippo! (UKOG and Angus Energy).

    The difference in the SP and the market capitalisation is astounding. As is the quality of the UJO licences which by far out-strips UKOG & Angus Energy’s. It is only a question of time before they come on the radar and out-perform, SP and oil production wise, the Liargas plays and what’s more UJO are a conventional oiler. No fracking, all environmental regulations are adhered too.

    UJO have quietly manoeuvred themselves into a potential winning hand. What’s more their recent placing takes out the spectre of imminent dilution. They’re fully funded going forward. Debt free. It doesn’t get any better than this for a micro-cap play.

    How high can they go? That’s the million-dollar question. On the run up to the Biscathorpe spud if investors get behind it they could double or triple in value. If they strike oil at Biscathorpe and bring in the West Newton discovery revenue will start to flood in, then 0.50p-1p isn’t hard to see. Could hit 2p we just don’t know.

    One thing is certain the SP will rise the closer the drills get and interest starts to pick up. Get a slice of the pie while it’s cheap, because ‘campers’ when it’s 0.30p you’ll be cursing!

    Viva!


    Dan


    Nota Bene: I hold stock in UJO. Not that it’s any of your business!!!


  • #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    #BNS! Reabold Resources Big Georgian Gas Licence On The Way?

    There’s a ‘hefty‘ lot of  Reabold Resources (LON: RBD) investors/traders out there, awaiting news on the company’s up-coming drills. Wick & Colter. If you don’t know what those drills are then I suggest you get researching because unlike certain other UK Onshore Oilers the RBD drills (Offshore UK) are the real deal. A ‘Roll of the dice’ with a decent chance of success (COS) on BOTH drills, particularly Colter. Which, once they actually get to rig ‘mobilisation stage’ will push this SP much higher. I personally hold some stock here, so am always on the hunt for information. The problem is the company are not releasing the news. Good or bad I publish what it is. You can moan all you want but it’s better to know what’s going on than not. It’s how you make money and it’s how not to lose money. It was pencilled in for a 12 noon release but I’ve been cashiered into 12:30pm ’cause one of the ‘twittermen‘ has to finish his go-karting with the family. What a nice guy I am….  🙂

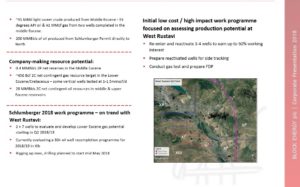
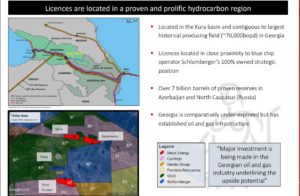
    Now it’s been a long time since I wrote on Reabold and new information has come my way via the BMD ‘sauces‘ pipeline. There’s a major whisper that this company are farming into a Georgian gas asset which is ‘controlled’ by, the soon to IPO, Block Energy. Fortunately I’ve managed to get my hand on not one, but three Block Energy prospectus’. The Georgian gas asset is flagged up as “Substantial potential from 608 Bcf 2C gross unrisked contingent gas resources at West Rustavi, analogous play being tested by Schlumberger in 2018 and 2019 on adjacent licence”

    This is more good news if it comes to pass, as it further flesh’s out RBD with another potential quality licence farm-in. A value driver.

    In the constant hunt for good returns, Reabold, sub 1p, could provide excellent returns. The SP could hit 2p/3p/4p/5p dependent on how successful they are. It will almost certainly break through 1p soon enough.


    Fully funded with a big following and an even bigger following waiting on the side-lines to jump in once the drills start to crystallise as a reality. The placing has been done so unless they’re running a ‘double bluff‘ holders should be able to sit tight and wait for the move upwards. Of course the placing flippers are still at work exiting, however most of them will now be out. Good place to start researching is HERE

    This is going over 1p soon enough. The only question is when? Not if! But as ever do your own research etc. Remember I hold stock as such I could be construed as a Rose Tinted Spectacle wearing leftie… 🙂


    Viva


    Dan


  • UKOG, LordLieALot (Lenigas) & Angus Energy, Game Over…..

    UKOG, LordLieALot (Lenigas) & Angus Energy, Game Over…..

    It was only ever going to be a victory for ‘Yours Truly’ on the whole Horse Hill, Weald Basin “Billions I tell Ya Billions of Barrels of Oil”  ramptastic David Lenigas claims. I take great delight in seeing the last fig leaf blown away in such a dramatic fashion late yesterday via the disastrous UKOG RNS. Confirmation if ever it was needed that the oil locked in Kimmeridge clay doesn’t flow naturally to surface it has to be fracced and on a frac only 1%/2% is recoverable, which is why every single major oil company has stayed well away from it.

    For those in the know, who took the time to thoroughly research these wild, ridiculous claims and the history of shysters such as David Anthony Lenigas and his cohorts at Optiva/Jermyn St. It was only a matter of time before the cold, hard reality of their web of lies and deceits spun around a grain of truth came crashing down.

    Of course like all Lenigas ramptastic scams the fat Aussie shyster has long gone selling out into the orchestrated rises. His Modus-Operandi should now be well known by every single Trader/Investor in the UK. Because it’s been well-known for the last 10 years by the ‘corporates’ in London.

    Liargas

    Aussie Shyster SOLD all his UKOG ANGS shares into his orchestrated P&D

    Lenigas is finished in the United Kingdom. (And he knows it) Which is why you’ll now find him spinning his lies on the Canadian, Australian & piss poor OTC markets. This is because he has been made persona non-grata by the London Alternative Investment Market (AIM) abuse team.

    For any Aussie, Canadian or  small time US investor who happens to be reading this I have this message for you. Whatever you do and regardless of what this fooker promotes get as far away from it as is humanly possible. Research this mans history. It is a litany of lies and shysterism where every single company fails, leaving mug punters and a puppet regime to hold the baby.

    What is very concerning for myself is how these two CONpanys have been allowed to not only raise hundreds of millions of pounds for assets that are patently uneconomic and paint them as ‘world changing’ when they’re quite clearly uneconomic but the damage to the communities, the environment and wild life in one of the United Kingdoms most treasured areas of outstanding natural beauty.

    Weald: Area of Outstanding Natural Beauty

    Saxon Weald. UK Heritage has to be cherished & saved.

    The Weald is thirty miles south of London and half way to the South coast of England it’s an area of outstanding natural beauty combined with a fascinating history.  This was, to the Saxons of 900AD, part of Andredesweald (the forest of Andred the Roman fort at Pevensey), that stretched from the marshes of Kent to the New Forest in Hampshire – 120 miles long and 30 miles wide. The Weald of Kent, Surrey and Sussex encompasses the Lancaster Great Park formed in 1372 which was renamed as the Ashdown Forest in 1672.

    The Organ Grinder & his monkey…

    Angus Energy and UKOG have been pouring thousands of gallons of toxic chemicals and acids into the substrata of the Weald. For what? The damage to the environment, flora and fauna and upset caused to the communities surrounding these bogus drills has been rightly meet with anger. It’s high time that these so called ‘gushers’, that never gushed any thing other than lies, are shut down. As an O&G investor even I can recognise that they are not adding anything to the National Interest. They’re a fantasy orchestrated by the fat Aussie to rape UK Investors.

    BB Loons

    I don’t have any sympathy for the BB and twitter Loons who deliberately took part in this hoax. Those on twitter and London South East will be nursing a not very ‘Tight Hole’. My sympathy is for the genuine investor who has once again been shafted and finds themselves holding stock that is destined to continue to head well below 1p. The fundamentals on UKOG are horrific.

    Angus Energy

    The fundamentals on Angus Energy may be a little better but their Weald basin ‘Jackanory‘ now lies in tatters. Messrs Vonk & Tidswell are now desperate to change the ‘Jackanory‘. You’ll note that ANGS are shifting away from their ‘Brockham mega gusher’ and trying to direct attention to their recent Balcombe farm-in. This is what they do. Constantly change the story away from their failures. Brockham, just like Lidsey and correctly predicted by this site, is a bread & butter oil play at best. Piss poor. It, like Lidsey, is uneconomic for a public listed company. Now you don’t have to take my word for it but do check out the production numbers on the Government O&G portal or better still read the British Geological Survey.

    UKOG & Angus Energy are a race to the bottom. Get out and stay out!

    Viva!

    Dan

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights