 This is the latest hot off the press Union Jack Oil (LON: UJO) Research Note.
I’ve used my PDF embedder so you can scroll through it by hovering your cursor on the note.
Enjoy the read.
Dan
x
This is the latest hot off the press Union Jack Oil (LON: UJO) Research Note.
I’ve used my PDF embedder so you can scroll through it by hovering your cursor on the note.
Enjoy the read.
Dan
x
David Bramhill is one of the best CEOs out there. His integrity, honesty and genuine belief that UJO are sat on one of the biggest UK onshore oil/gas discoveries is beyond reproach. That’s a fact. You really couldn’t get a better CEO at this level.
I spoke to a broker and an analyst this morning, their opinion is that Union Jack Oil (LON: UJO) did the right thing by placing now. They believe that if the pandemic continues to take hold, raising cash in 2021 would be difficult. It was prudent of Bramhill to get the cash in. Ergo he did what was in the best interests of shareholders. A bitter pill to swallow but one that puts Union Jack on a firm financial footing.
The drill rig for the West Newton discovery is imminent. Wressle should be pumping oil some time in October/November. Keddington will be worked over/drilled, BOPD will increase, Biscathorpe will be drilled. The company are now fully funded for at least 12 months. I don’t expect to see another placing post West Newton success and Wressle going onto production. In my opinion there should be no more placings, the proviso being success or  the sale of West Newton.
As for the ‘background noise’ out there post the Union Jack £7M placing that dropped yesterday. Lets get some facts out there. The financial BBs were awash with placing rumours a full 10 days before I managed to confirm a placing.
Understandably people are ‘pissed’, I get that. It’s always a kicker when companies raise cash but it’s par for the course on AIM listed stock no matter how good or bad the company’s are. Regardless of who raises, by its very nature a placing usually leaks out. That’s specifically down to the broker/s running the book who in order to fill the book have to reach out to their clients and other brokers and their clients. That’s how it leaks and that’s why it was all over LSE, ADVFN, III, chat threads etc.
Which brings me on nicely to some of the utter shite currently being posted on social media.
The attacks on Bramhill and his company are nothing short of vile. The conspiracy theories are so wide of the mark that they’re up there with ‘Lizard People‘ controlling humanity from Mars.
What these trolls do is to blame everyone else for their failure. How can you be sat on 50%,60%70% 80%90% profit and not derisk? If you can’t understand that then it’s easy to see why you hurl abuse. You’re not mentally adept to be trading on the AIM Casino. Better you buy premium bonds. Crawl off under your rock, leave it to those of us man enough to deal with the ups and downs of investing/trading.
One moron who got caught holding a big chunk of shares and regularly trades in and out of UJO came up with a belter last night, told me how I’d sold at the top and bought back at the bottom ’cause I knew there was a placing. I derisked most of my UJO at the height of the lockdown pandemic/oil crisis in May, after sitting on a £30k loss I managed to basically break even. I, like you, have other financial commitments, I missed the huge rise but I don’t seek to apportion blame for my missed opportunity. It’s one that got away. No great secret and all a matter of recorded fact with UJO and my broker. 
However, inventing smears out of thin air and posting/emailing/phoning vile abuse to a 69yr old CEO at his home is a reflection on you. You really shouldn’t be trading AIM stocks. Baseless accusations of shorting, insider dealing and the calling for the jailing of the company PR girl is about as laughable and ignorant a rant as I’ve ever seen on financial BBs.
It’s all to play for at West Newton. It’ll be interesting to see these ‘pussies’ currently howling shite, change tack should the biggest UK Onshore oil/gas discovery finally flow. Just remember who they are.
 Viva!
Dan
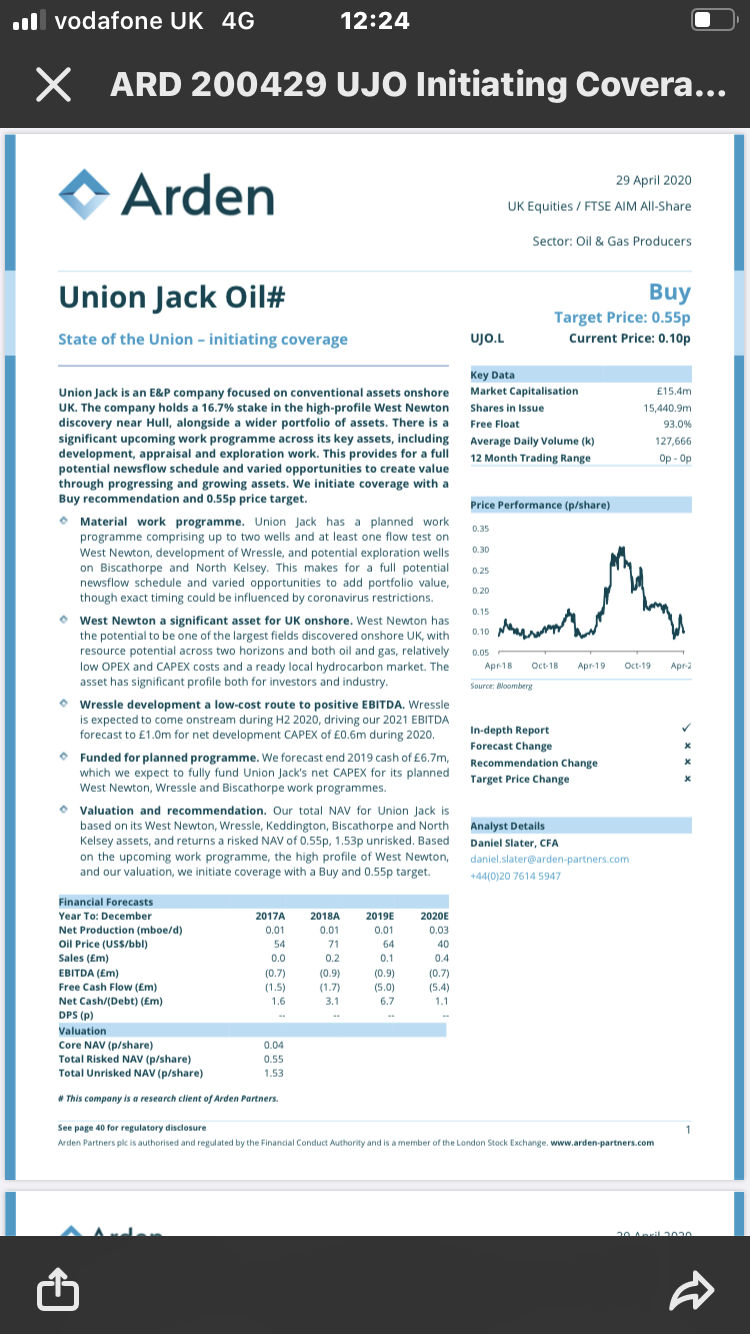
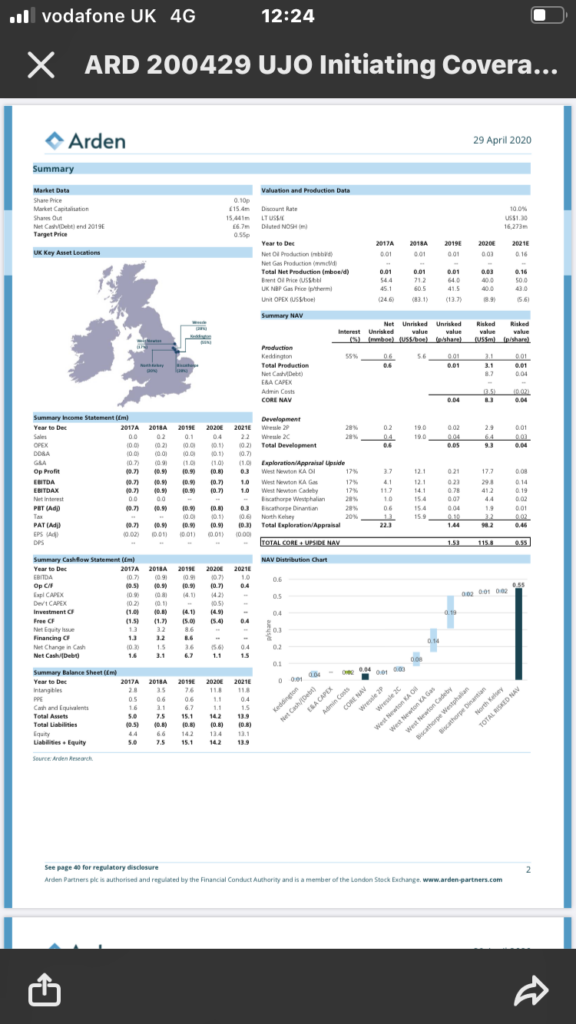
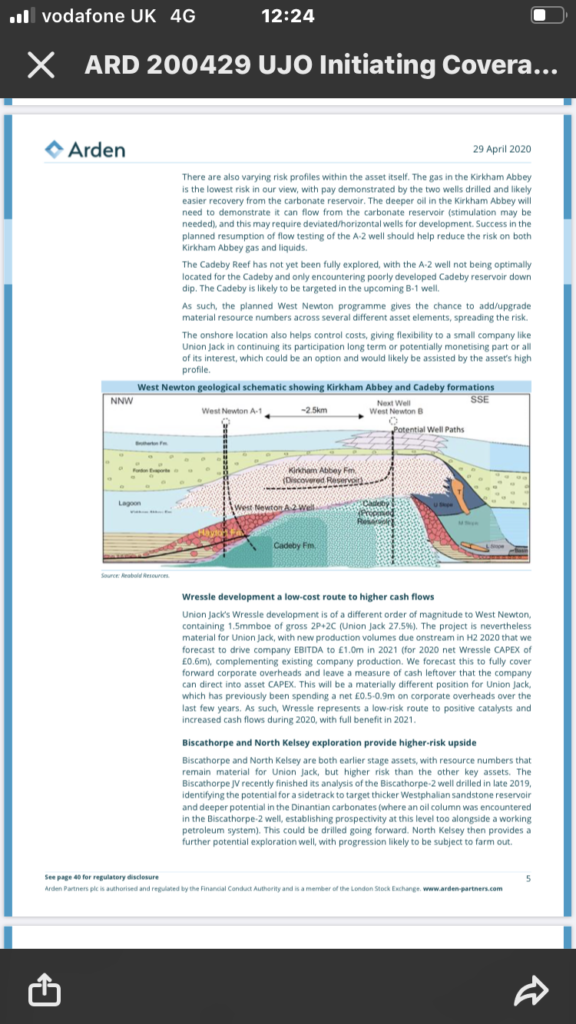
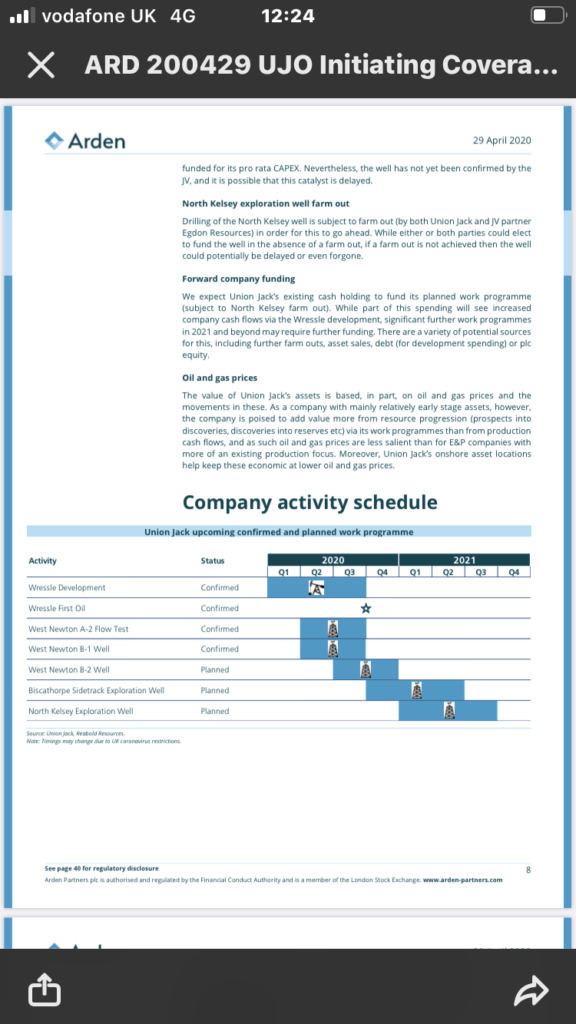
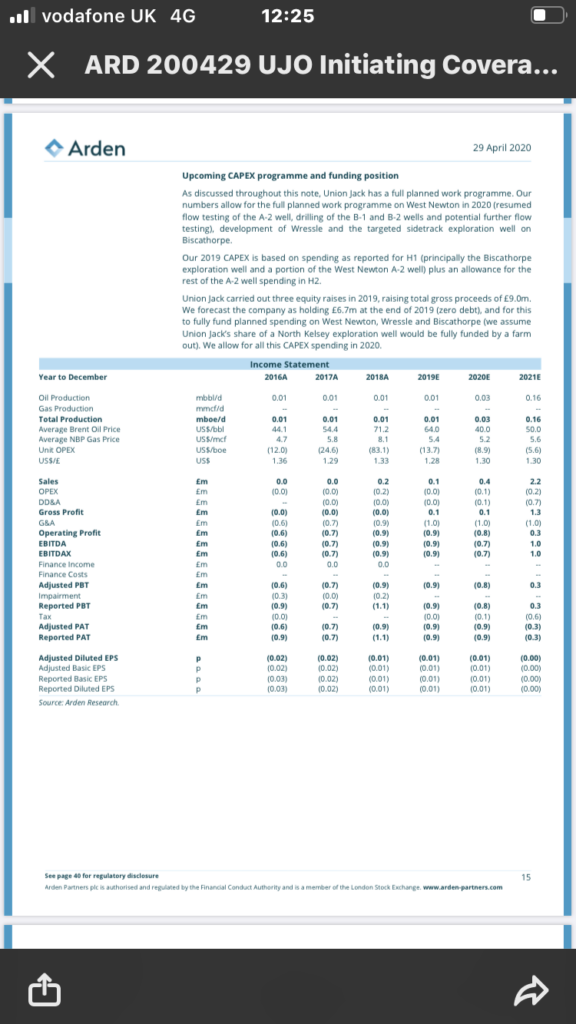
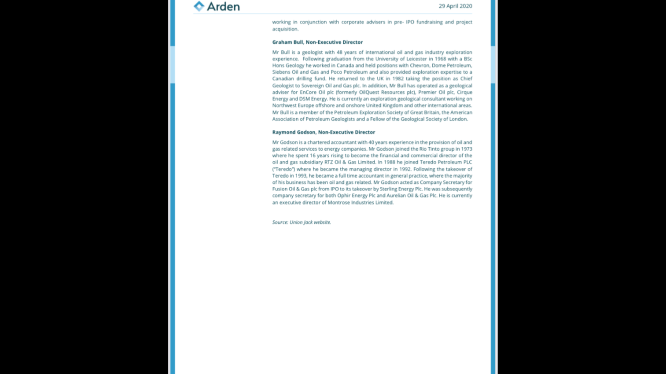
As stated on twitter yesterday, I’ve managed to get hold of the latest Research Note on Union Jack Oil (LON: UJO). It’s by Arden Partners who are a ‘dedicated corporate adviser and multi-service stockbrokers’. A small outfit and themselves a listed company.
I don’t propose to go into a convoluted epistle on the pros & cons of buying, trading, investing in UJO. I’m going to leave that to the reader of this ‘Hot Off the Press’ Research Note.
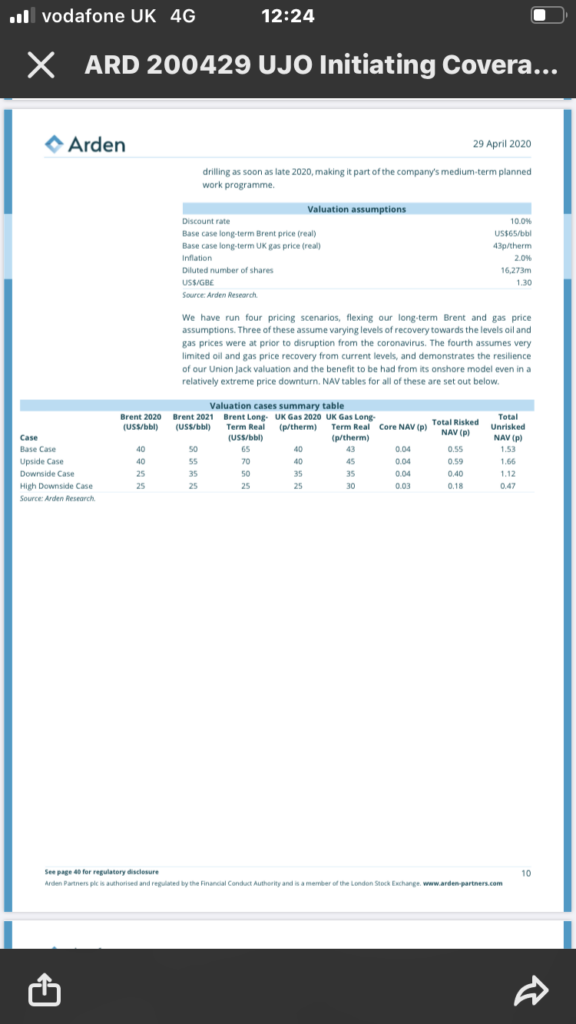
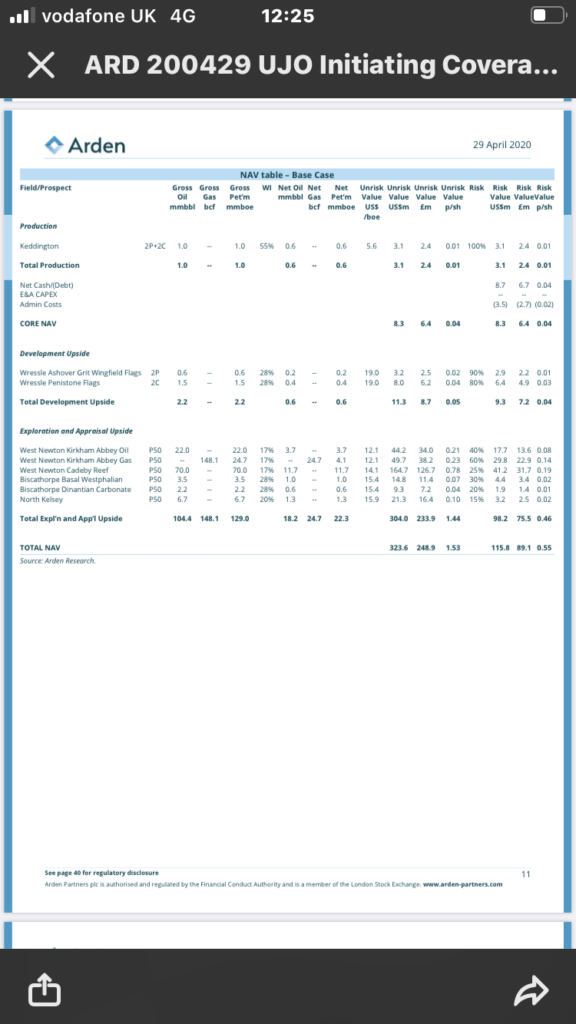
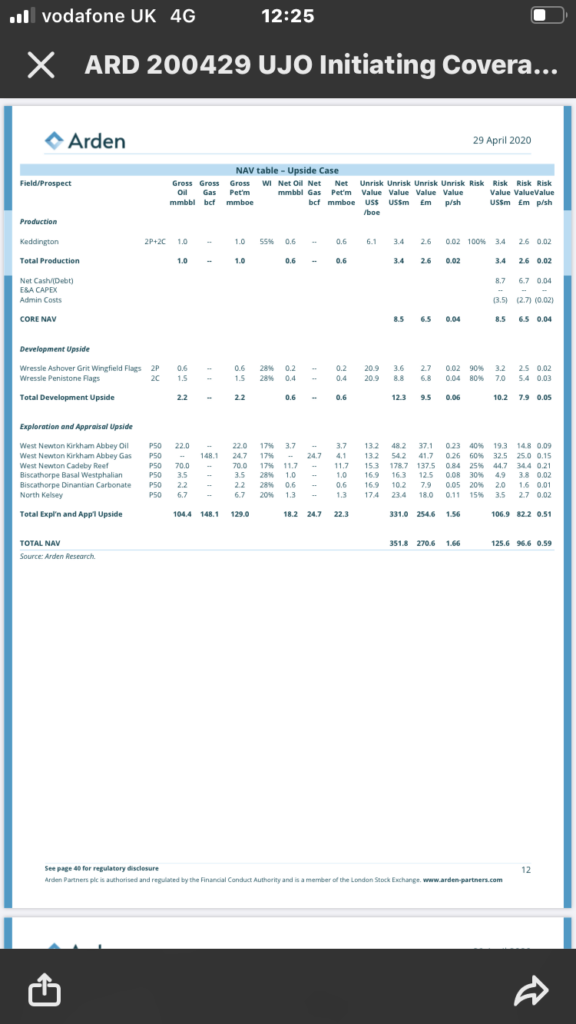
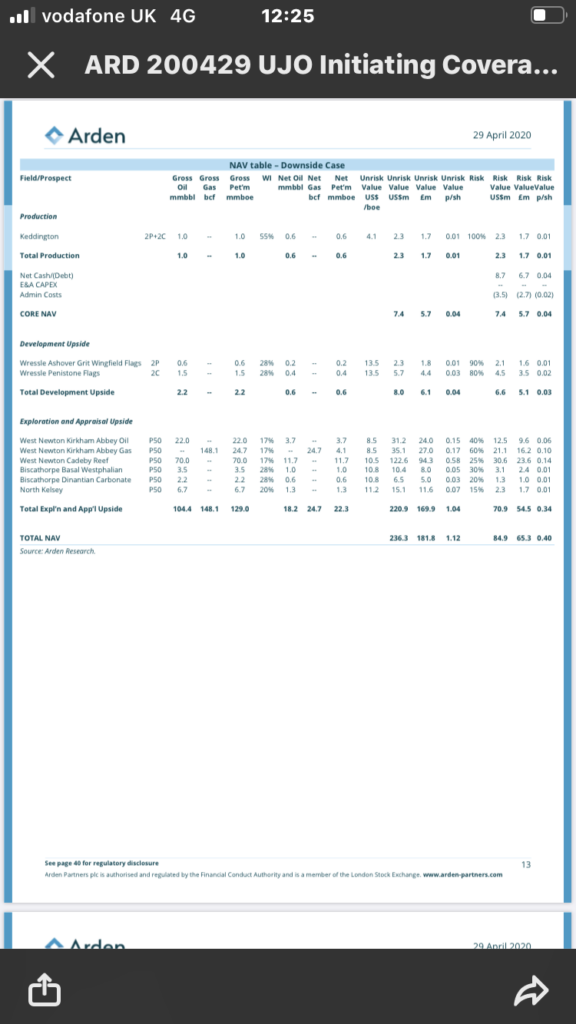
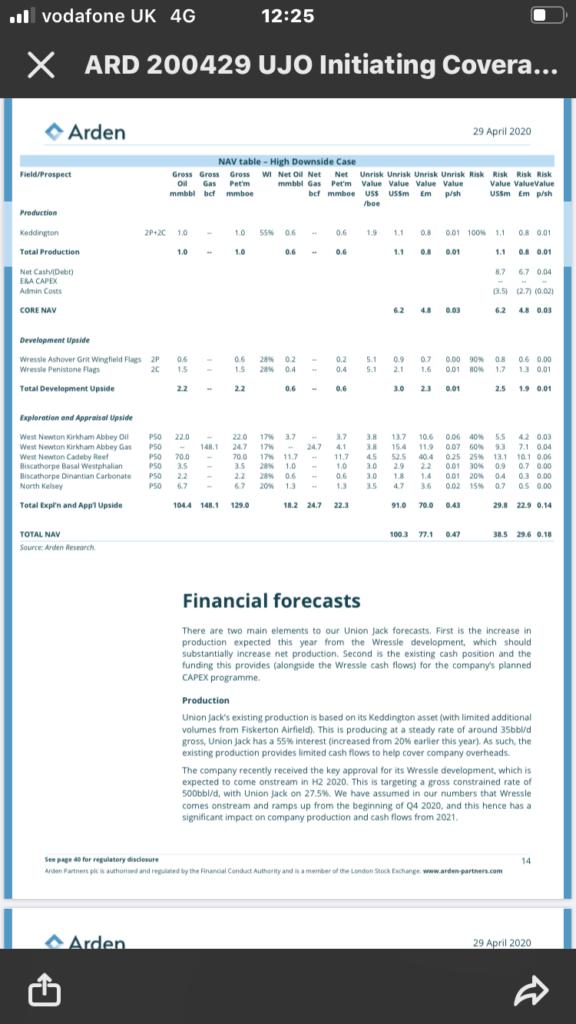
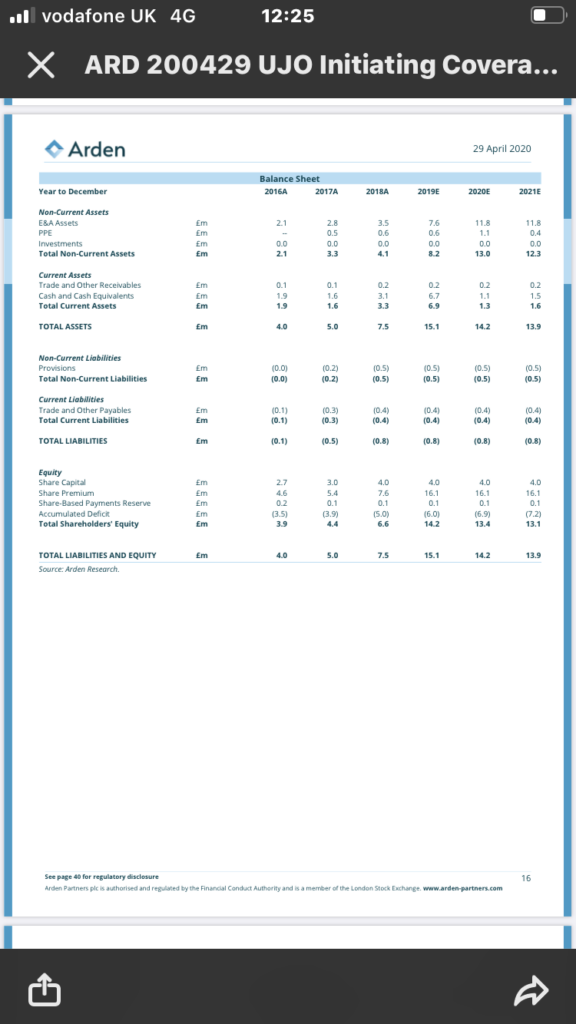
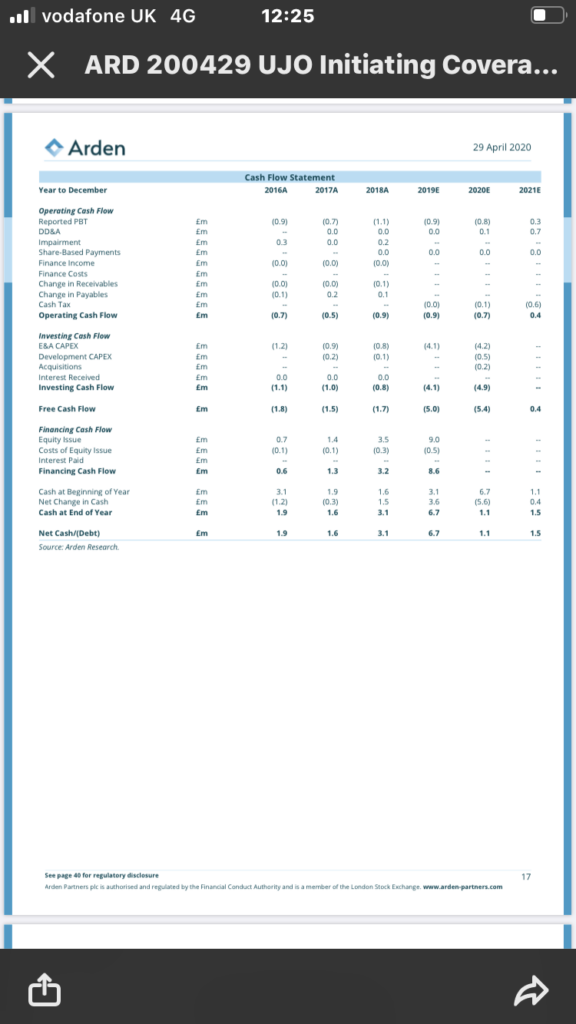
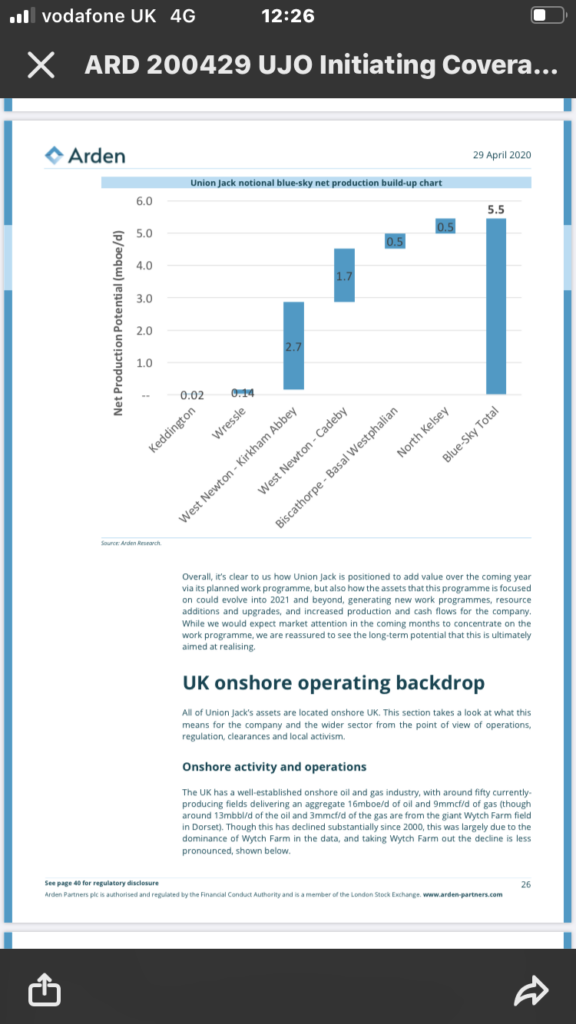
Suffice to say it’s a buy rec’ with an unrisked NAV of 1.53p and a risked NAV of 0.55p which equates to a 450% gain from yesterdays SP of 0.10p.
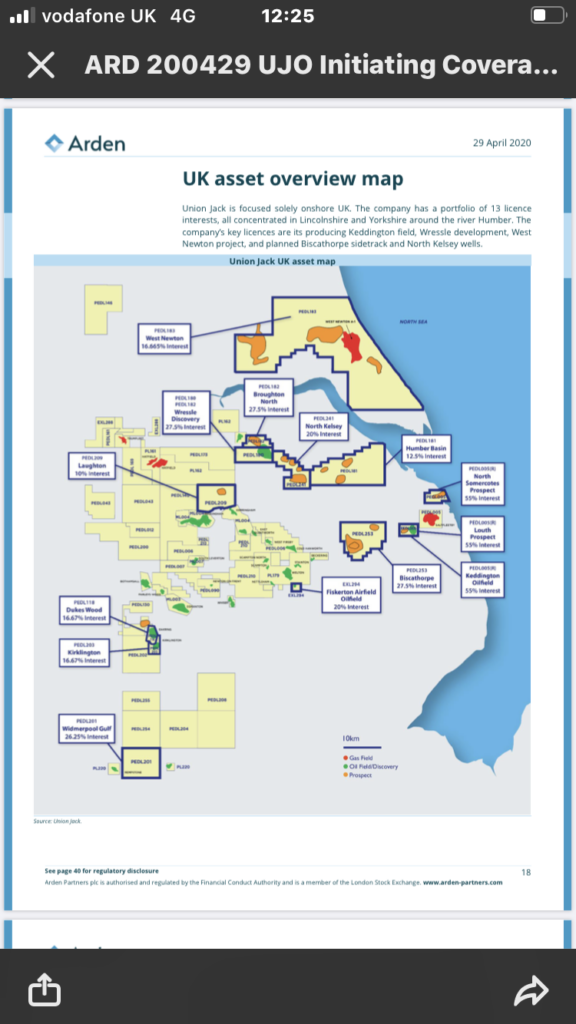
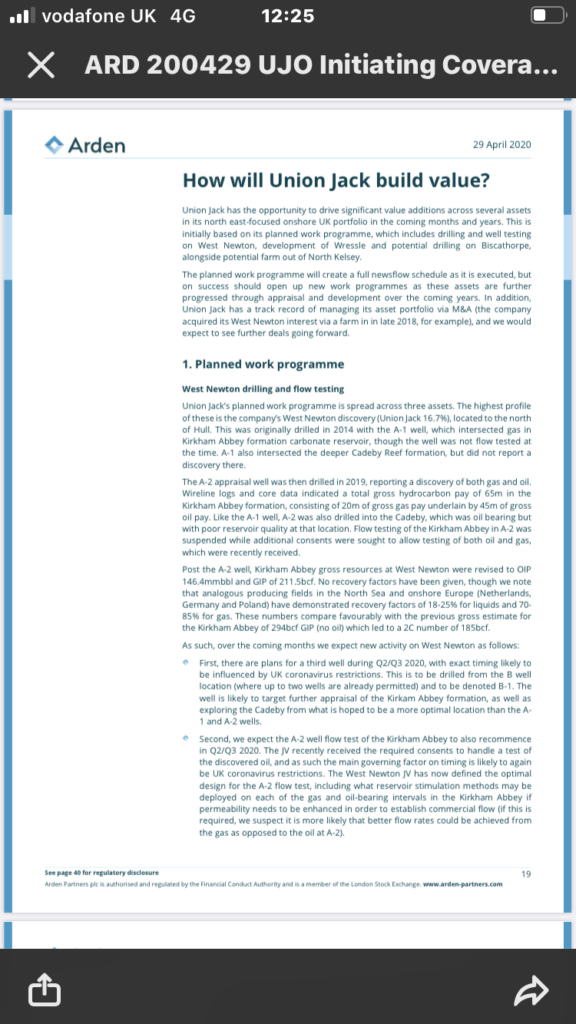
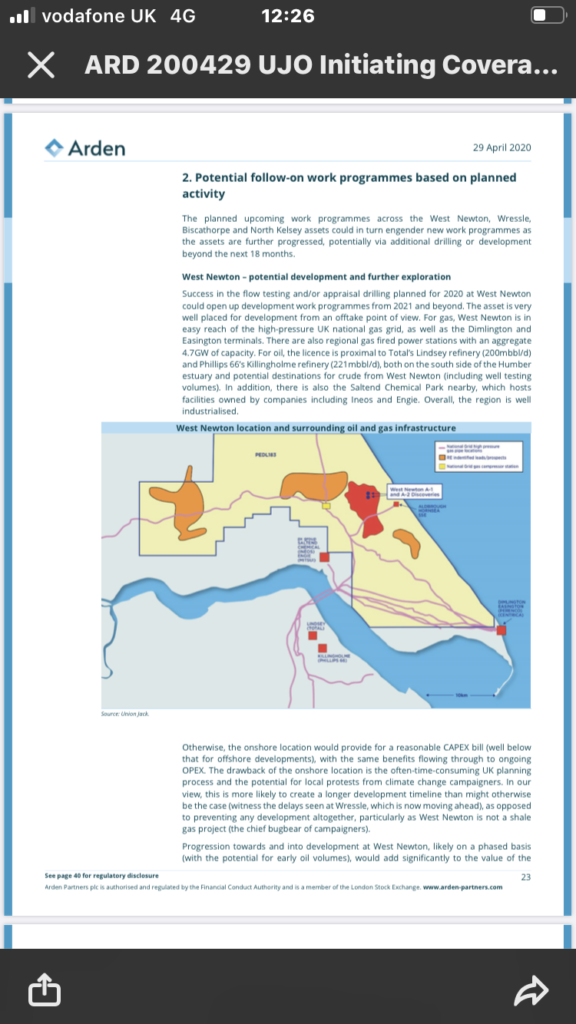
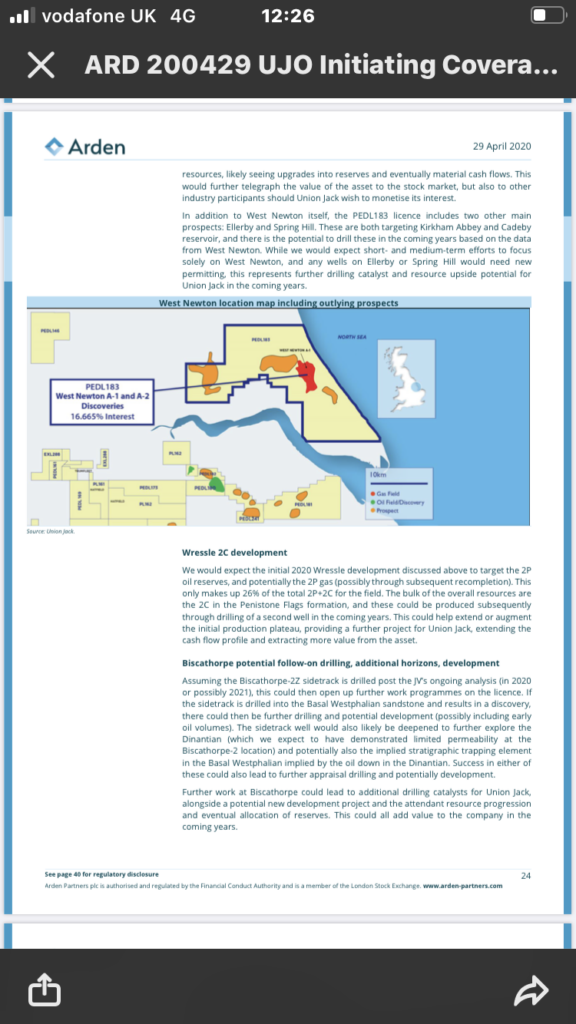
By now most of you should be up to speed on all things West Newton, Biscathorpe, Wressle, Keddington and North Kelsey. Success at the fast approaching West Newton discovery via flow test will launch the SP upwards.
Happy reading and good luck.
Viva
Dan




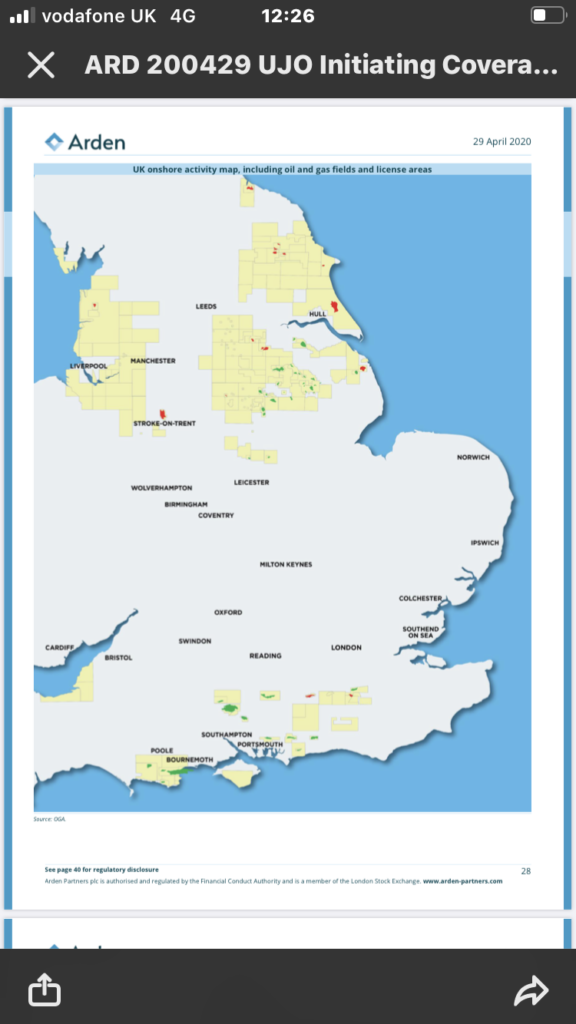


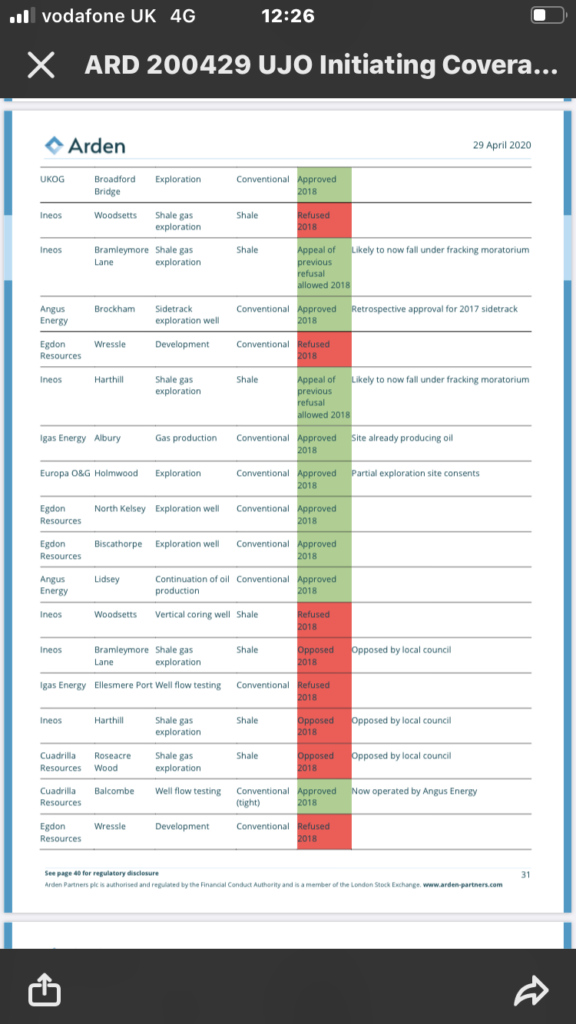
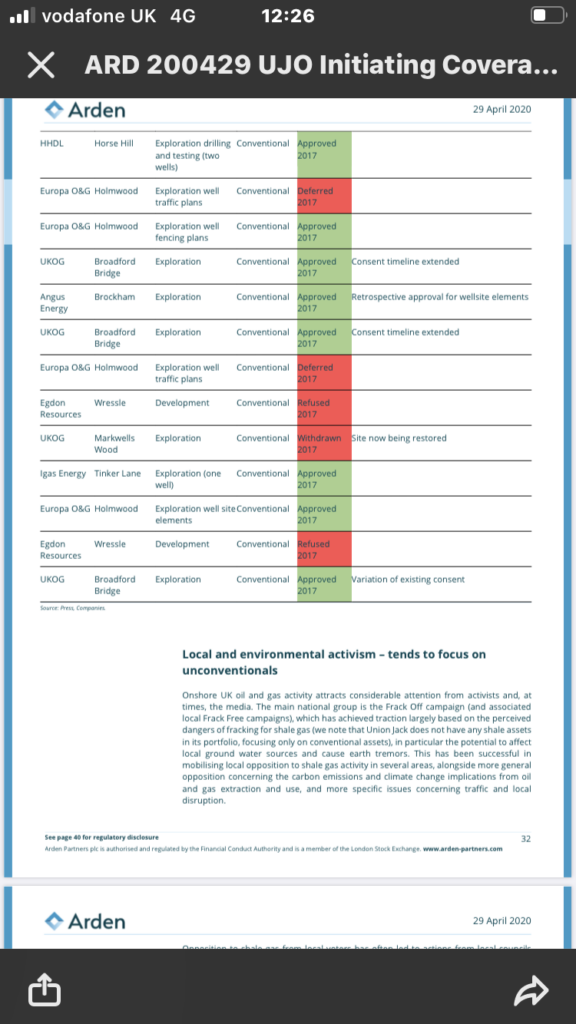
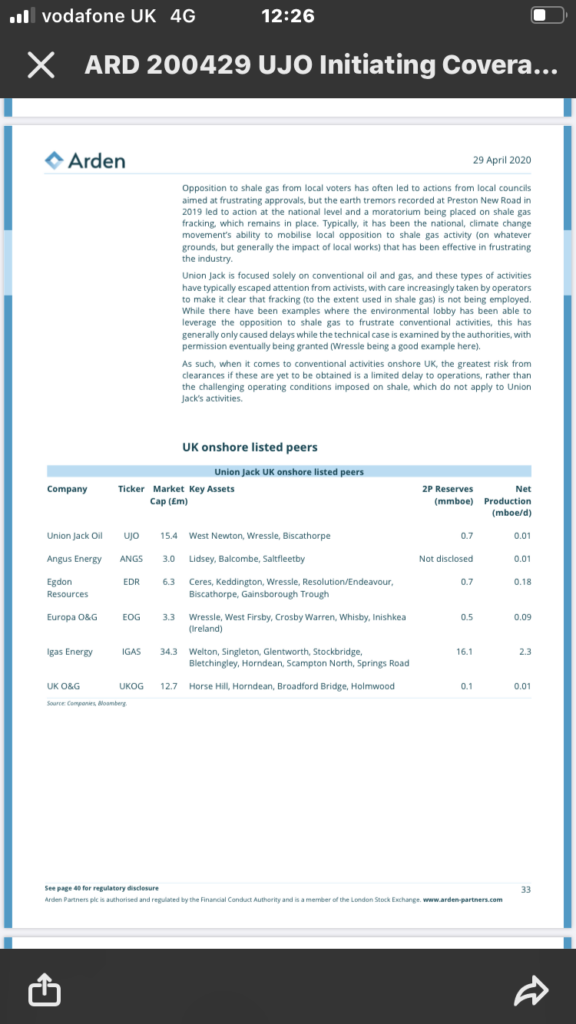

To hold or not to hold? That’s the question being asked by share-holders of Union Jack Oil (LON: UJO) & Reabold Resources (LON: RBD).
There’s been a lot of piss & wind posted recently on the, Rathlin operated, West Newton major oil & gas discovery. The key to investing and even trading is to pick your entry and your exit, based on what you know as opposed to what’s being eternally spouted on social media. There’s one twitter lunatic who seems to think (Wrongly) that UJOs’ head honcho is responsible for putting in the HSE, O&G paperwork as well as ordering all the capital equipment for the imminent drill/s and any delay is their fault.
Oil & gas drilling by its very nature is bureaucratic. It’s the Operator Rathlin who lodge ALL West Newton applications. Partners have a non operated interest. If you have any doubts on your trade/investment in any company or in any sector then sell up and move on. It’s as easy as that. Get out, there’s no shame in selling.
Yesterdays Rathlin update was forced due to the amount of erroneous speculation circulating on social media.
“Rathlin Energy (UK) Limited, as operator of the West Newton A-2 well, is providing the following update regarding the Extended Well Test.
Preparations for the retesting of the well are progressing both from an operational and a regulatory standpoint.
Coordinating the availability and timing of services, equipment, personnel and other aspects of operations with the requirements of our regulators is imperative.
These activities and approvals are often dependent upon one another.
Rathlin Energy (UK) Limited will provide operational updates via this website when appropriate.
Kind regards
THE RATHLIN ENERGY (UK) LIMITED TEAM”
So with the above in mind, here’s exactly what’s going on. The Extended Well Test and site mobilisation are a matter of days away. All equipment has been sourced with a date pencilled in for the EWT, and the drilling by Rathlin of West Newton 2B could happen in concert or be very close behind the EWT. One rubber stamp is awaited from the EA. That application, according to my sources, went in last week. The usual turnaround from the HSE/EA is 14 days. So my ‘back of the fag packet calculations‘ are end of this week beginning of next. Site mobilisation and EWT are imminent. Don’t be fooled or get caught out. When the news drops the SPs are only going one way.
Reabold and Union Jack are fully funded for at least 18months, both have paid up in advance. There should be no placings in 2020. Especially UJO whose asset/production base are all UK onshore. Onshore drilling, compared to offshore, is way, way less expensive.
There are at least 2 oil predators awaiting the EWT oil flow results. That means that if it flows, as expected, from the 60,000,000+ boe then there’s a real possibility, depending upon how far West Newton 2B has progressed, that the asset will be bought out by either one or both Majors in partnership, circling.
Share-holders of both listed companies need to remember that West Newton is a billion dollar oil play: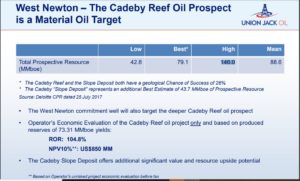
A major UK onshore Oil & Gas discovery has already been called by the companies. It’s of National importance and as such oil minnows or their interests get swallowed up. That’s how it works in the oil sector.
Any investor thinking that Rathlin will remain the operator of a Major UK O&G discovery are in ‘la’ la’ land’. An offer or offers will come. That’s a given. Of course oil has to flow. There are only 2 companies i’m invested in: Reabold & UJO. That’s because both have exposure to West Newton. I’m not looking at any of their other assets regardless of how good they maybe. It’s all about West Newton for me. All the companies involved are convinced that (barring a major onsite explosion or a military takeover of the UK) oil will flow. It doesn’t get any better than that…..
Viva
Dan
Tip: I often see and hear this: "Know The Game". Let me tell you something, anyone who consistently espouses this shite is 'at the bollox'. Investing/trading at any level isn't a 'game'. It's deadly serious. Those that tweet, podcast or write such shite are in the main Pump & Dumpers, who'll say and do anything to manipulate small cap' micro stocks. Using a whole host of anonymous twitter, BB accounts, DMs, Private chat, phone calls and email groups. It's easy to ramp telling 'porky pies' about crap companies you're taking kickbacks from or dumping shares into the ramp. Silence is better than bullshit.

What isn't easy is getting your hands on quality information. Base your strategy on well sourced information. Remember losing several thousand pounds for most of us has financial consequences. Rather than know the 'game' 'Know Their Game'. Here endeth the lesson...
There’s no a hard & fast rule, in the not so glittery world of financial commentary, but occasionally one has to make a ‘judgement call’ in the interests of transparency for shareholders, traders and investors who’re all too often kept in the dark, when really companies should be reaching out to their shareholder base and the wider market, instead of skulking around behind the ‘corporate curtain’, raising cash.
Some financial placings actually have merit and one, if given the chance, can see the raison d’être or not. Which brings me on nicely to “Project Wallace”. Documents now in my possession confirm that Reabold Resources (LON: RBD) basically think that they’ve hit the ‘Oil Jackpot’ at the West Newton drill site.
Project Wallace is the corporate (Stifel) Institutional overview/pitch of all licences held by Reabold, with summary’s pertaining to each of their licence holdings: Reabold California (USA), Rathlin/West Newton (UK), Danube Romania, Corallian (UK)
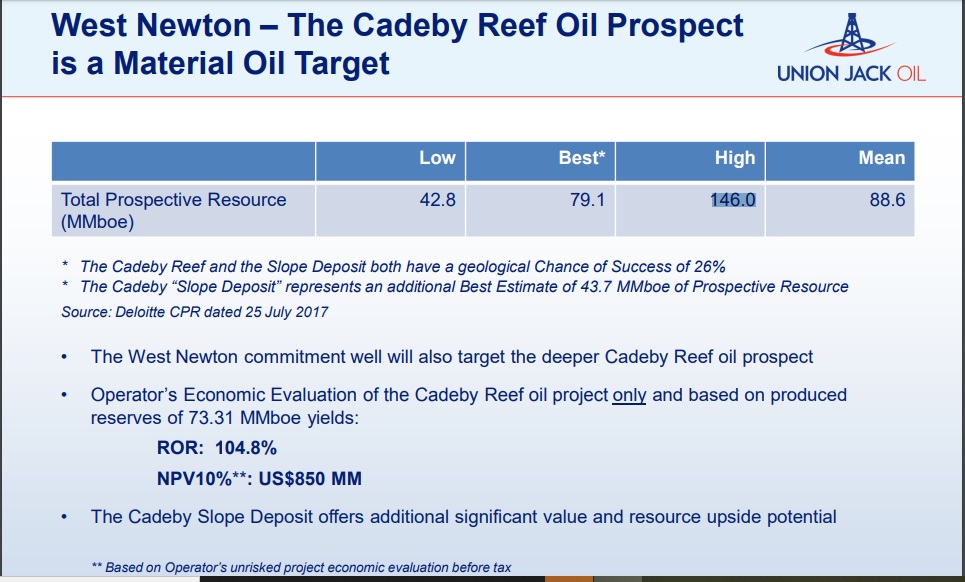
For the purposes of this blog post I’m specifically concentrating on the West Newton/Rathlin transaction that can be summed up as thus: “$29m investment for $274.4m of additional value” which doesn’t take into account the potential value/oil from the Cadeby oil play which has a further value of $850m NPV (gross). The proposed placing price was 1.2p. That may have changed post the ShareProphets scoop and RNS confirmation. We’ll know soon enough. For those of you who wish to read the complete unabridged Stifel overview there’s a ‘Click Me’ button at the bottom of this post.
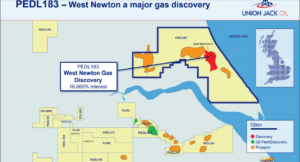 It’s glaringly apparent that RBD and their partners believe that West Newton is a major onshore oil/gas discovery that will flow oil & gas and could net well in excess of $1,000,000,000 at $11.50c net
 back based upon as yet the unpublished CPR and the volume-metrics that will soon be released. The Extended Well Test is due Q4 2019, which means West Newton is gearing up, news should start to drop next few weeks or so….
To me it looks to be the ‘real deal’ based upon what’s been going on behind closed doors however ‘Caveat Emptor’ always applies. It’s not in the bag until it’s in the bag. RBD will be fully funded with an increase in West Newton which is basically their crown jewels. UJO are already fully paid up for the EWT and have £2,600,000 cash at hand, they’ll probably sell out after the oil/gas flows. It’s known that Bramhill (CEO UJO) has consistently rebuffed offers of financial backing from several institutions.
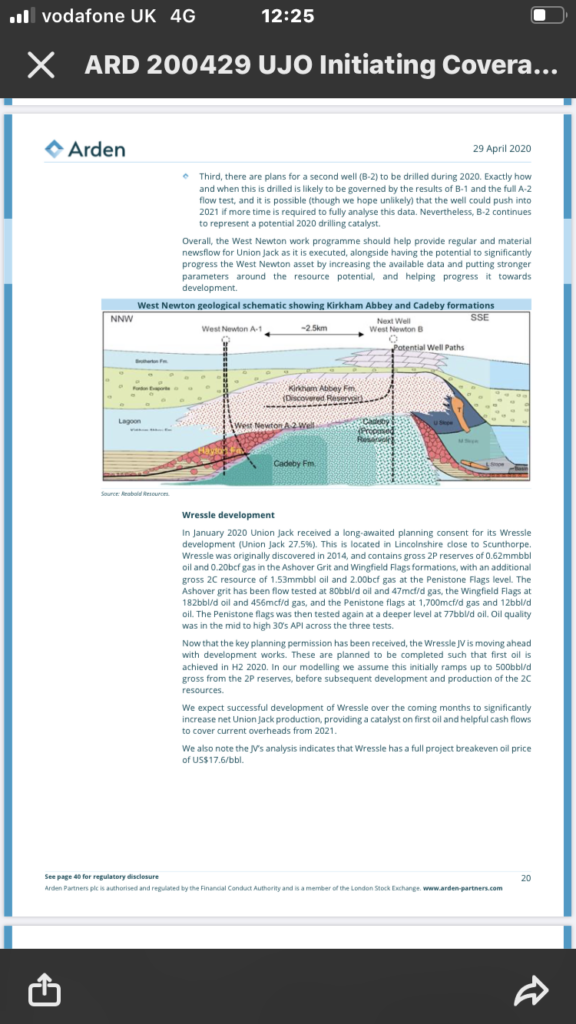
So, how much O&G is there? We’ll get an idea once the CPR/Volume metrics are released which should come pre EWT. A 65 metre hydrocarbon column in the Kirkham Abbey is in itself a company maker. Add in the Cadeby and it’s probably the best O&G play on the London Stock Exchange. Especially since all the Major holders have all basically ‘sold off’. That brake has gone. Expect TR1s with the inevitable deceitful ones double speaking trying to talk both companies down. Par for the course, i’m afraid.
Once oil/gas flows at West Newton then RBD could hit in excess of 5p and UJO anything up too 2p. Of course it’ll be a bumpy ride with many peaks and troughs but that’s again ‘par for the course’ in the Oil Sector. So, now we ALL know the facts on West Newton and the proverbial playing field has been levelled. Courtesy of Dan! The Man! Whose got no hair but doesn’t care LOL!
Good Luck
Viva! 
Dan
*Take Note! Before I start some wise words to those who read & follow: Lot of interest in emails/texts and private DMs over the last few months on why I’m not as prolethic writing/tweeting/tipping stocks every day on companies. There’s a good reason: The simple truth is this: Most of the time investing/trading is about not getting suckered into the horse-shit. It’s about protecting capital while biding ones time until a real opportunity comes along, then getting your research done. Usually it’s a company that I’ve been tracking on the watch-list for months if not years. If that company gets to a point in time where it’s a crock of shit then I write it up negatively, if there’s a real opportunity then I write it up positively. Hence UJO which I’ve been following since the Wressle discovery. The way to keep some semblance of integrity/credibility is to resist running with the known rampers/mug punters. Plough your own farrow and always remember that it’s not as these fookers say a ‘Game’ it’s deadly serious peoples liveleyhoods are at stake.
The majority of companies never get there. Because they’re life-style companies. The AIM is awash with them. If, like me, you’ve been around for an age and a day, you know that most companies burn up. Any blogger/market commentator or financial platform that consistently writes, posts, podcasts/tweets on a daily basis nothing but ‘positivity’ on super dooper oil, tech, mining stock plays etc. Is a ‘scatter-gun cowboy’. And should be treated with the utmost caution. No one can call 40/50 stocks in a year positively. That is a fact! If you can get 5/6 right then you’re doing extremely well.
Occasionally, along comes a company that manages to get to a point in its business cycle of ticking all the right boxes. It doesn’t happen often but when it does there’s potential for huge financial gains. Such is the time for Union Jack Oil (LON: UJO). It’s a small micro-cap oiler that’s mainly under the radar, trading at one tenth of a penny (0.10p). What marks them out, as of now, is that their asset base, which is onshore UK, has the potential in the coming months of transforming them into a genuine UK oil producing company. Not many of those around these days…..
UJO have an interest in a whole host of UK onshore licenses, but for the purposes of this blog I’m concentrating on three of the licenses that will cause a re-rate should they do what most expect them to do, strike oil and gas or be allowed to get the production going (Wressle).
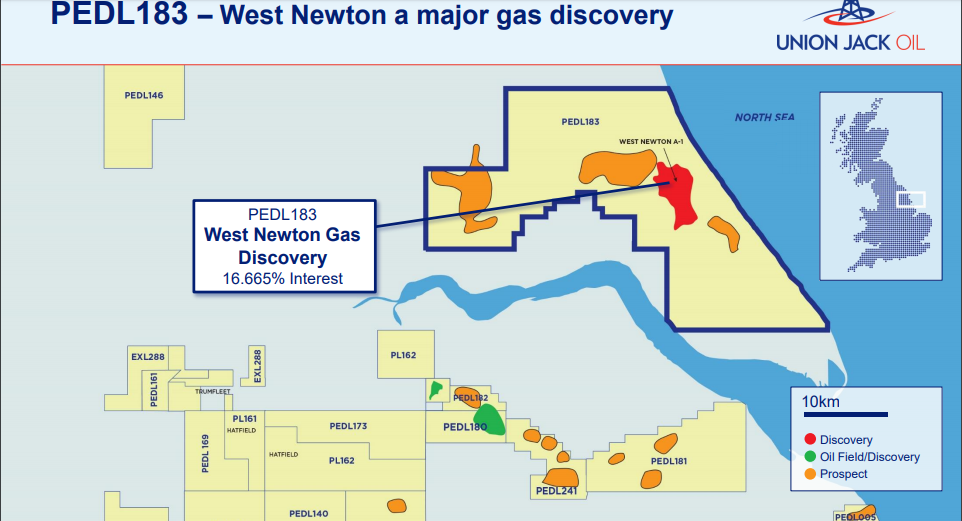
1/West Newton Gas Discovery: (16.6%) West Newton A-1 gas discovery (Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross), the West Newton conventional appraisal well is planned to be drilled in Q1 2019.
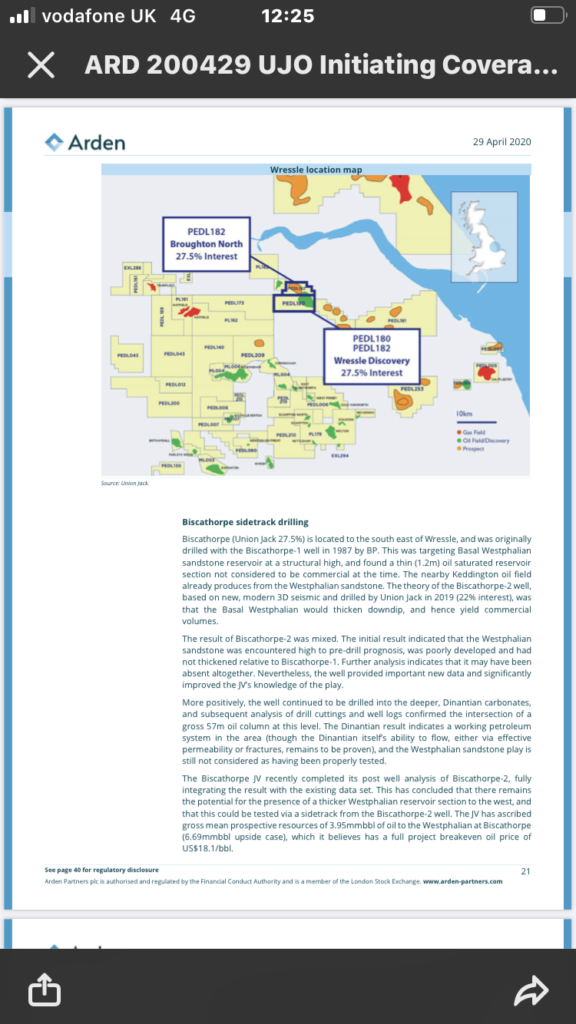
2/Wressle: (27.5% ) Is an oil discovery that’s mired in ‘legals’. It’s a bread and butter asset that has flowed oil and gas. The estimates of oil are circa 2.1 million barrels. Wressle is expected to flow at 500bopd minimum but could hit 1,000 bopd that’s somewhere between 137-264bopd net to UJO. All going well this should be resolved in late 2019/20.
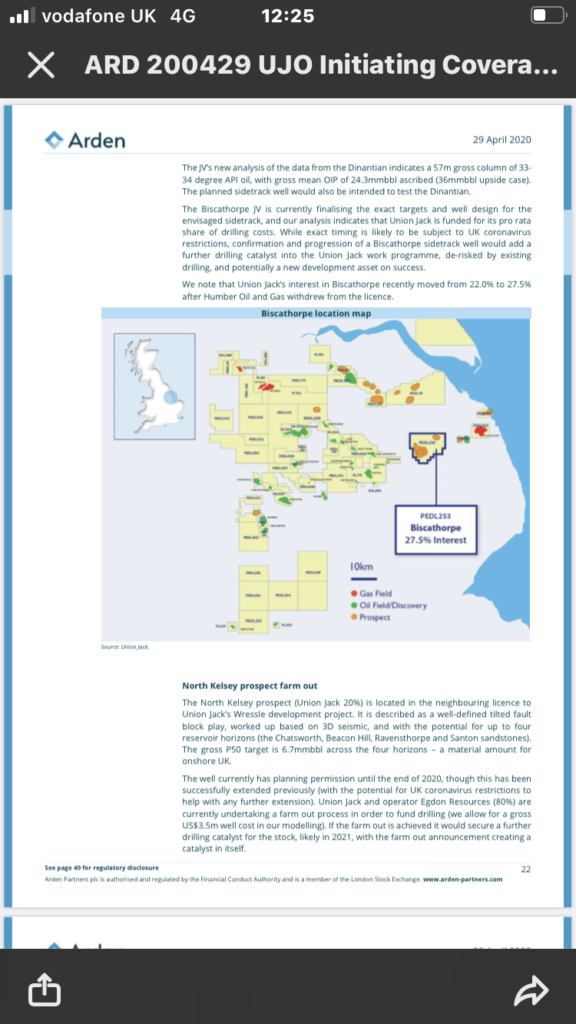
3/Biscathorpe: The mean Prospective Resource volume for the main reservoir objective, as calculated by Egdon Resources (35.8%) is circa 14 million barrels of oil. Additionally, there’s a potential for stratigraphic trapping at Biscathorpe, which, if present, could increase the expected gross Prospective Resources to 41 million barrels of oil. UJO Own 22%. Drilling late 2018.
Now here’s the nub. 22% of 14m barrels of oil is circa 3m barrels net to UJO. If it’s 41M barrels then it’s circa 9m barrels of oil net to the company, on The West Newton A-1 gas discovery the Best Estimate Contingent Resource 189 Bcfe or 31.5 MMboe gross, the West Newton conventional appraisal well is planned to be drilled in Q1 2019. That’s circa 5MMboe net to UJO. On Wressle which is a discovery and has already flowed there’s 2.1m barrels of oil, 27.5% net to UJO that’s 550,000 barrels.
In total (not including their small producing assets), over the next few months, at the top end of the numbers Union Jack Oil are involved in three licences in play for circa 75,000,000m – 47,500,000m barrels of oil or equivalent. That’s more oil and gas than any UK onshore company currently listed on the London Alternative Investment Market (AIM). There is NO company that comes close to them.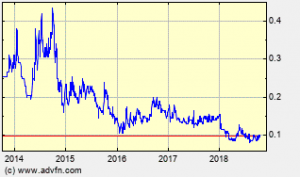
Their share of the oil and gas is bigger than two of the biggest over-hyped POS’s currently deluding investors with fantasy claims of billions of barrels of oil in the Weald. While producing zippo! (UKOG and Angus Energy).
The difference in the SP and the market capitalisation is astounding. As is the quality of the UJO licences which by far out-strips UKOG & Angus Energy’s. It is only a question of time before they come on the radar and out-perform, SP and oil production wise, the Liargas plays and what’s more UJO are a conventional oiler. No fracking, all environmental regulations are adhered too.
UJO have quietly manoeuvred themselves into a potential winning hand. What’s more their recent placing takes out the spectre of imminent dilution. They’re fully funded going forward. Debt free. It doesn’t get any better than this for a micro-cap play.
How high can they go? That’s the million-dollar question. On the run up to the Biscathorpe spud if investors get behind it they could double or triple in value. If they strike oil at Biscathorpe and bring in the West Newton discovery revenue will start to flood in, then 0.50p-1p isn’t hard to see. Could hit 2p we just don’t know.
One thing is certain the SP will rise the closer the drills get and interest starts to pick up. Get a slice of the pie while it’s cheap, because ‘campers’ when it’s 0.30p you’ll be cursing!
Viva!
Dan
Nota Bene: I hold stock in UJO. Not that it’s any of your business!!!
