google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: pump & dump

  • ‘Seeking Alpha’ (Growth) I Accuse!

    ‘Seeking Alpha’ (Growth) I Accuse!

    Image result for alpha growth logo

    “Oh, what a tangled web we weave… when first we practice to deceive” That pithy saying could almost have been exclusively written for the Alpha Growth Chief Operating Officer (COO) Mr Daniel R Swick.

    I was an investor in Alpha Growth (LON: ALGW) on their IPO. I liked the company it had a good business plan, a Board of Directors that passed muster and a very capable investor relations team who got their message across. If it could do what it set out to do, then the SP would rise and rise it did. Hitting over 5p in 2018 from its IPO price of 1.2p. Indeed, their SP is still trading over 70% up from the IPO price, that is good news. I sold out way back last year when it became apparent to me that they were in contractual difficulties signing up on the major contracts that were being promised, taking a modest profit of circa 40%. I needed cash for a property investment renovation. But I never stopped following or researching them as they could always be a contender for a blog post etc.

    Broken Promises

    Alpha Growth came to the market promising great things in the Longevity sector, a fancy word for buying peoples pensions/life insurance policies at a discount. Trumpets were heralding major company making deals just around the corner, unfortunately one can only blow one’s trumpet for so long before lips blister and you run out of ‘puff’ and after 14months of ‘blowing investors trumpets’ the clarion calls have faded to a weak squeak. Credibility is now on the line for the company. And it is credibility that I draw investors/trader’s attention too.

    Now, this is an important point to understand, which becomes self-explanatory further down this article, Alpha’s business is all about ‘Contracts’ and their ability to not only sign contracts to close deals, but to stick to the terms of a contract. Contractual breaches are not good business when you’re in the Longevity sector. Doesn’t matter what the contract pertains to or who it’s with. You breach & it gets out then you’re in difficulty and your ‘Longevity’ as a company comes into question.

    Placing

    My sources and research indicated that the Company were running up debts, having contractual difficulties, failing to close deals and needed to raise cash in the not too ‘distant’. In short potential Contract Failures/Breaches of some kind or another etc. Recently having spoken to probably one of the most diligent FCA regulated broker/nomad outfits to clear up the ALGW placing rules I can confirm thus: The amount they can raise (being a standard listed entity) is a percentage (20%) of their shares in issue in any one 12-month period.

    “Companies quoted on the Standard List have greater restrictions on the issue of new shares than those on the AIM (cess-pit).  Once a company is listed, it can only increase the number of shares that are admitted to trading through either a placing or from the conversion of convertible debt or exercise of warrants (unless issued prior to June 2017 in both cases) is limited to 20% of the shares already admitted to trading on a rolling 12-month basis.  The only way around this is to issue a new prospectus.”

    There is a temporary work around in that for shares quoted on the Standard List, a company can issue the shares (or shares that may result from a convertible) and not admit the shares for up to one year.  This means that the shares cannot be traded, but only a fool or someone confident of a huge rise in value would agree to this.

    Material Uncertainty

    With a declared cash balance of £237K, as of last year Dec’ 2018 they can only issue 20% of 126,335,000 shares in issue. That equates to a total placing of shares of 25,267,000 in their next 12-month window. Being an extremely generous type let’s say they raise cash with a small 20% discount at 1.6p. That’s circa £400k in cash over the next 12 months bearing in mind that they burnt through close to £500,000 up to August 2018 (8 Months) and generated zero cash then they have for the next 12 months a miserly £600,000. Which is why their Auditor issued a “Material Uncertainty” as a going concern. Alpha Growth must raise cash.

    Contractual Breach

    Now that brings me on nicely to one of the known on-going legal disputes regarding a breach of contract to a ‘service provider’ that’s snowballing into a full-blown court case. How do I know this? Why it came directly from Mr Danny Swick who passed confidential information, in breach of contract, to one of Alphas ‘Cornerstone Investors’ on 23rd/24th December 2018. (It also embroils the Cornerstone Investor into a legal dispute) So, my source, on the now known legal dispute, is ‘Swick the Dick’ who made wholly unsubstantiated, malicious claims that the service provider briefed me, thus breaching the contract. Laughable, as it is deceitful, to try to deflect away from their parlous, pecuniary position and their failure to ‘pony up’ and pay their debts, ‘Swicky’ has told a pack of lies to the service providers solicitors! Ho! ho! ho! Talk about digging a hole……

    Of course, I’ve provided the solicitor (who contacted me directly) with the name of the Cornerstone ‘geezer’ and a full verified transcript of the twitter conversation, that is as you say “f**king damning” while completely exonerating myself and the service provider from ‘Swicky Dicks’ lies.  One thing it does, is prove 100% that the leaker of confidential information is Mr Daniel R Swick.

    Caveat Emptor

    Image result for pump & dumpWhat’s going on here is simple: The feeding of ‘green bananas’ (Promises of contracts/deals worth £100Ms) to the BB ‘Howler monkies’ in order to artificially manipulate their share-price so that they can raise cash at higher levels. Then dump a placing on the mugs who buy in at the higher SP. By way of example: This is the dichotomy: “Alpha Growth plc is a financial advisory business providing specialist consultancy, advisory and supplementary services to institutional and qualified investors globally in the multi-billion dollar market of longevity assets”. Says the blurb on their website. This is their financial position: Just over £200K, No revenue, No big contracts signed, Contract Breach, Legal Jeopardy, with qualified accounts containing their Auditors ‘Material Uncertainty’.

    Big Red Flags

    Alpha are a company that deal/trade in contracts. A contract is a legally binding agreement based on honesty and integrity. Breaching a contract simply because you do not have the cash to pay is bad business practise but breaking the confidentiality of that contract then lying to a solicitor is about as big a red flag as an investor can get. If a COO of a company is prepared to cheat another company out of their fees, tell a pack of lies to a solicitor while giving out confidential information to ‘privileged’ investors then one has to ask what else has this company lied and cheated about?

    Questions

    1/Who else hasn’t been paid? 2/Why haven’t the so called ‘big deals’ been concluded? 3/How many others has Swick been passing confidential information too? 4/What are the implications of cornerstone investors being given sensitive information before the bread & butter investors? 5/Is this endemic of their business? And 6/What will happen when their potential business partners learn that the company, they’re looking to sign a contract with breaks confidentiality, lies to solicitors, doesn’t pay up and ‘could’ be on the hook for literally £100,000s in legal costs if it ever gets to the High Court? It’s a fooking minefield! I could go on and on with the legality and drag in The FCA rules on disclosure and market manipulation, and why Swick needs to ramp up the Alpha SP etc. But I fear information overload for the reader…. Swick has been heavily involved in the formation of Alpha Growth and the IPO from day one. He wasn’t plucked out of the ether or head hunted. Swick was running around London in 2017 engaging with brokers and corporates pre IPO on ALGW business.

    Suffice it to say that I’m now all over this lot speaking to journalistic sources in the USA and their potential business partners.

    I promise you this ‘Dear Swicky’ should you or any of your team appear at any investor presentation in the United Kingdom then ‘Yours Truly’ will be attending to rip you and your company a new arse hole in public and in front of your investors (Mugs)

    Blow My Own Trumpet

    And that Ladies & Gents is why I’m the 2016, 2017 and fingers crossed (Vote for me), the 2019 ADVFN International Financial Blogger par excellence…….


    Image result for advfn 2017 international financial blogger photoViva!

    Dan

    X


  • Nostra Terra The ‘Circus’ of Lies. Back in Town. Clown Players Exposed!

    Nostra Terra The ‘Circus’ of Lies. Back in Town. Clown Players Exposed!

    Image result for PUMP AND DUMPI’ve been sat on some of this information for quite some time, as a matter of fact since 21st April 2018. Now remember that date, (which I’ll explain later down the thread). I’ve been waiting for a big enough example of the disgraceful, wholesale lies and fraud perpetuated by the main ‘players’ to appear and yesterday’s Nostra Terra Oil & Gas (LON: NTOG) so called ‘MM short’ that has been pumped out over the twitter and BB sphere now gives me the easiest example of the many failed Pump & Dump attempts this lot have perpetuated (not only on NTOG) on the gullible investors/traders, that can be duped into swallowing the utter ‘horsepox’ the band of not so ‘Merry Men’ perpetually scream online.

    Yesterday and no doubt today, which isn’t the first and won’t be the last, there were five accounts on twitter and various accounts on London South East & ADVFN, pushing yet another Nostra Terra Oil & Gas SP manipulation. Come on down the ex-Vox booted director David (pay me, I’ll Ramp 4U) Burton, ably assisted by his ‘Clowns’ Ben Turney, Alex McKinley & Mikey Whitlow and last, but not least the NTOG shorting CEO, proven Liar and bullshitter Matt ‘scumbag’ Lofgran. All five are on twitter and four of the named individuals have separate platforms that blast out utter spurious guff, masquerading, as financial AIM market commentary 24 seven.

    Apparently, according to ALL of the above, including the CEO of Nostra there’s a Market Maker (MM) short of stock in NTOG, inferring a ‘short squeeze’. One may ask how all 5 of these chaps came to that CONclusion? Bearing in mind that there’s absolutely no truth whatsoever to this unsubstantiated claim. Just quite what a CEO is doing on twitter stating such nonsense breaks every AIM rule in the book on sensitive financial disclosures…

    Well let me tell you. On the 21st April 2018 the day of the UK Investor Show, four of the above met in a public house (Mr Burton, Mr McKinley, Mr Whitlow & Mr Turney) where they agreed, among other things, to form a ‘mutual self-help society‘ i.e. they made a pact and conspired to ‘Promote’ each other’s tweets and blogs/articles/podcasts. Sources who witnessed it also tell me that they believed they could become a force greater than ShareProphets. The deluded ‘Wannabees‘ thought they were going to take over the world of micro-‘crap’ info…… 
    The terms of said ‘Clown Pact’ were/are to retweet and back up each other’s tweets/blogs/news/articles/podcasts. If you check all four twit timelines, (Deletions galore post this blog)  you’ll notice an unhealthy correlation between ALL four accounts when it comes to certain stocks. Take for instance Nostra Terra Oil & Gas the piss poor microcap that cannot self-sustain without continually raising cash. It has to duck & dive via placings, warrant sales, it’s in debt up to its eyeballs, mired in legal disputes ad infinitum and has piss poor stripper well fields, which are touted as ‘company makers’. (Stripper well fields contain wells deemed economically at the end of their productive life and require constant cash burning workovers to slurp up the remaining dregs of oil left. Such wells produce a few barrels of oil per day, at best, then require shut-in for workovers etc.).

    The economics of stripper well production when combined with the cash burn of an AIM listed company to flesh out the ‘Jackanory’ has one purpose and that is to fool the mugs into trading the stock to increase the liquidity so that the company can place and keep the balls in the air. ‘Balls’ being the fat fees those running the show take! Those that assist with the bogus promotion often trade into the rises and some like Turney & Burton and no doubt the others get paid or have been paid by the CONpanys. It’s nothing short of a scam.

    The history of Lofgran is one of total failure and scurrilous lies. There is no short squeeze here. No Market Maker desperate for stock to close a short. It is sheer fantasy to enable, nay manipulate, the SP upwards for the yet again Placing that is inevitable. The shorting Shyster has been running around the City gauging the appetite for a Placing. Hence the continual ramptastic horseshit of the Band of not so ‘Merry Men’.

    The Gang of four will no doubt deny it, however using NTOG as the example just check how many tweets, blogs, articles and podcasts there’s been on this POS from the ‘Merry’ men that’s been cross pollinated between themselves. Of course it could all be just a coincidence….. Sadly, the form book on other stocks they’ve all been cross-pollinating and ramping kills that Trumpian defence stone dead. As does their ‘Meeting’ in the boozer at the UK Investor Show on the 21st April 2018. Witnessed and 100% correct!


    The ringmaster of this ‘circus of lies?’ David Burton of Tell Mugs Shite (TMS). The sad clowns perform for a few shekels……  Oh, what a wicked web we weave when we practice to…… Tell Mugs Shite! 


    Now not a lot of people knew this, but they do now!


    Viva


    Dan


  • Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

    Andalas Energy Investors Face Wipe-Out Via CONsolidation & Another Placing…

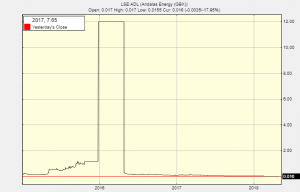
    Today yet again we have ‘yet again’ another scandalous placing & acquisition RNS and a Board change RNS from the corporate crooks who run Andalas Energy & Power (LON: ADL). Make no mistake these fookers are running true to form. The RNS’s contain blatant lies. Which I will expose further down in this ‘Epistle to the Morons’.

    Mug Retail Punters woke up this morning to yet more horse-shit via the bush-tucker system. I say ‘Bush-Tucker‘ for good reason as my sources, who are 100%, have kept me informed on #ADL at every twist & turn. More of why I’m using an Aussie term further down in the blog…

    What is happening at Andalas Energy? Well I’ll expose it and expose it in full! Today’s Placing/Acquisition wasn’t news to me as I already knew months ago about the new asset and knew on Thursday/Friday that the joint cunts, Novum & Optiva were lining up a placing. Sadly I only had 2 sources. (The BMD rule on solid info is that I have to get at least 3 separate sources unconnected with each other before I run an article.)

    RNS LIES

    Investors who are currently holding ADL stock are in for a wipe-out via a massive share consolidation and another placing. Todays RNS’s contain blatant lies. Gorringe has stated; “Indonesia offers significant potential and we remain committed to our existing projects and strategy there”.  This is a blatant lie.

    As is this; “On behalf of the board, I would like to extend our thanks to David (Whitby) for his service to the Company, he brought passion for Indonesia to Andalas and we wish him well in his future endeavours.” 

    New Name. New Asset. New BOD. Consolidation & Wipe-Out. Rinse Repeat!

    David Whitby, outgoing Chairman, said “I am proud of what the team has achieved in Indonesia, whilst the Company has not done enough to show the market that the foundations built over the past few years will generate shareholder value, I am confident that I leave the Company full of opportunity. I wish the team and shareholders all the best as Andalas executes its new focused strategy, which has the potential to make 2018 a significant and exciting year for all involved.”

    For a company to opine such blatant shite in an RNS is testament to how detached from reality they have become from their share-holders. There is no shareholder out there who, hand on heart, would agree with the utter shite above! Whitby and Gorringe have decimated ADL and raped it since day one with a series of worthless paper deals. Not one therm of gas or drop of oil has been produced, yet tens of millions of pounds have been fleeced out of UK investors. They’re now being paid off to fuck off. For Whitby or indeed any of the sad sack of shit that run this company, to state such utter bolloxs gives away exactly how they see shareholders. Gullible fools bent over & willing to be repeatedly financially sodomised, with the help of the likes of BigGob, Bellcunti & the Gunslinger a.k.a Doc Holiday etc. You’ll all remember them with their incessant ‘Share of The Year’ shysterism…

    SHADOW DIRECTING

    Those who are basically shadow directing ADL have no intention whatsoever of progressing Indonesian assets because they know they’re paper assets and worthless. The plan which is being shadow directed by Paul Hayward (Block Energy) Novum brokers Colin Rowbury, James Sheehan & Optivas Christian Dennis, (you may recall some of those names as these were the people who installed the crooked Whitby crew (and kept it going) at the beginning of this long, sad, tortuous tale and what a tale it has turned into) is to reinvent ADL and slowly flip out the majority of the board quietly over a period of months, bring in new blood, while at the same time changing the company’s name, employing professional PR/IR and changing the emphasis/direction of the company. Hence the new asset…. It is a reinvention of the wheel, a passing on of the ‘cash cow’ that allows those at the pigs trough to keep feeding and filling their pockets.

    And pray tell just where in the name of God are ADL going to get their 14.75% share of an offshore drill in the North-Sea for the Licence P2112 ? The cost of which is up to circa £50,000,000 sterling…. It cannot be done unless they jettison the entire Board of ADL and run away from Indonesia and wipe out existing shareholders via a massive Consolidation and placing and that folks is exactly what those shadow directing this POS are about to do!

    As for the rest of  Licence P2112 who is going to come in? My sources are telling me that, that other super sodomiser of UK Retail Mug Punters, Solo Oil & Gas (LON: SOLO) are also in discussions with Eagle Gas LTD. And we all know who really has their fat sticky ‘didgeridoos’ in SOLO. Come on down the fat Aussie Liar and corporate conman His Excellency ‘LordLieAlot’ take a bow David Lenigas!


    Wipe-Out on the way ADL!


    Have a Good Day Cobbers!


    Viva!


    Dan

  • Mayan Energy An Absolute F**king AIM Swindle & Scandal!!!

    Mayan Energy An Absolute F**king AIM Swindle & Scandal!!!

    Some deluded, befuddled investors and traders are currently full of ‘Great Expectations’ on Mayan Energy (AIM: MYN) well let me educate those out there who are running with the hounds on this one, particularly my friend Richard Jennings, a good guy is Ritchie, whose company Align Research have over the last year or so really made a name for themselves as purveyors of honest opinion based on facts. That’s because Align try to ‘Align’ their interests with that of share-holders and usually, in the past have covered some decent listed companies.

    I’ve used their research to great effect but sadly I believe their standards are now being lowered by covering companies of let’s say ‘dubious’ history. If you roll around with dogs then you get fleas and I’d urge Align Research to cease coverage on companies that have a history of telling ‘Tom Peppers’.  Now I know why the Dogs of AIM are all rushing to Align Research. It’s because they have a good name as responsible analysts. Ergo the Dogs want their blessing to give them the semblance of respectability and professionalism. Basically so they can shaft investors. Fortunately I can write it as it is and am not enslaved by the corporate world. So you get it as it is. The truth no matter how unpalatable gets told by ‘Yours Truly’.

    Lifestyle companies now being covered by Align Research, such as Red Rock Resources (AIM: RRR) run by that well-known Charlatan Andrew ‘Calamity’ Bell, the Dud, PowerHouse Resources (AIM: PHE) and the one I’m currently going to chronologically dissect, Mayan Energy, formerly trading as Northcote Energy and also Everest Energy, are beginning to surface. I changed my name once these fookers have had three….

    Now I won’t go into Everest Energy. Other than to say Charlie Woods has been at it from the beginning. I’ll go straight from the Northcote 1st day of dealings run through their ‘Jackanory’ of company changing assets that always end up in the shitter and point out the increase in shares and the many placings. Then we’ll get to grips with the ‘Mayan’ assets, massive share dilution, placings, assets and CONsolidation and the new improved ‘assets’ while stating the fundamental cash position of thrice named Mayan….

    DAY ONE NORTHCOTE

    Northcote was launched with a $10,000,000 share purchase agreement (SPA) and a £1,000,000 placing. Their asset was The Horizon Project which produced 26.4 boe/d. Northcote had 866,904,578 shares in issue. Within 12 weeks they had placed yet again for £1,500,000, shares now in issue 991,412,716 assets coming in were the OKE Acquisition, the Eagle Option and the Bird Creek Project oil production was circa 48boepd. Yet again within 3-4 weeks they placed again £663,922, shares in issue 1,066,627,375 another asset Matthis. Oil production circa 100boepd. 5 Months down the line they place again £1,750,000, shares in issue 1,150,503,626, another asset South Weslaco.

    By the time we get to Feb’ 2014 there’s now 1,238,066,657 shares in issue via options/assets paid for in stock and the initial issue of £1,200,000 zero coupon secured loan notes from vulture financiers Darwin Strategic, the Cleveland asset is renamed Zinc Ranch. 97.6 BOPD and 560.2 MCF/D net to Northcote. We get to 7am on the 12th Feb’ 2015 a loan note conversion is announced £50,000 total loan notes so far £250,000 push the shares in issue to 1,412,731,660, Shoats Creek, MXO deal etc. We then fast forward 1 minute, yes 60 seconds and Northcote RNS a placing for £1,558,000 further ballooning shares in issue to 3,380,021,399. In comes the acquisition of NAP USA. Then the fire sale of assets begins. Now are you getting the picture here? By the 20th of April 2015 the shares in issue stand at 4,748,137,883.

    Now again I could go on and on but I suspect I’ll have to fast forward before I kill you with the litany of bullshit placings, stripper well assets and tie ups with such ‘illustrious’ partners as Andalas Energy, MXO, Red Rock Resources and further asset sales, decreasing oil production, placings and cash rinsing that ended up with over ten billion FOOKING shares in issue (10,098,253,604) just before they changed the name to Mayan and started a rinse repeat operation.

    FAST EDDIE ‘PARACHUTES’ IN

    The 1st ‘Fast Eddie’ placing and a 400-1 consolidation!!! After fleecing tens of millions of pounds from UK Investors! Losses of circa $20,000,000, liabilities of approx. $3,500,000 with a ‘thumping’ $91k in cash! Doesn’t exactly instil confidence does it guys? ‘Fast Eddie’ parachutes in……

    Nevertheless, let’s carry on because believe me it’s a right ‘Carry on’ and it only gets worse! The parachuting in of Eddie Gonzalez or as I call him ‘Fast Eddie!’ on 1st Sept’ 2016. ‘Fast Eddie’, didn’t waste any time getting to grips with the newly named Mayan Energy he quickly placed £550,000 and the shares in issue skied to (I kid you not) 13, 898,253,603 (Thirteen Billion, Eight Hundred and Ninety Eight Million, Two Hundred and Fifty Three Thousand, Six Hundred and Three). Of course, ‘Fast Eddie’ did exactly what the previous failed shysters did and issued himself a shitload of options: 780,000,000 (5.7% of the new improved rinse repeat Mayan) at 0.015 of a new shiny penny.

    Within weeks ‘Fast Eddie’ was at the placing bolloxs yet again. This time a placing for £1,250,000. Shares now in issue a staggering 21,144,630,415 (Twenty One Billion, One Hundred and Forty Four Million, Six Hundred and Thirty Thousand, Four Hundred and Fifteen shares…..) I wont bother going into the warrant packages for the other corporate shysters.

    But wait I’m not done yet!

    ‘Fast Eddie’ Not as ‘Fast’ as BMD I see right through you!!!

    In March 2017 some 7 months since the new improved CEO took the helm, ‘Fast Eddie’ is at the Placing bollox yet again! This time it’s a 12,000,000,000 (Twelve Billion) £600,000 placing. Shares now in issue 33,144,630,415, (Thirty-Three Billion, One Hundred and Forty Four Million, Six Hundred and Thirty Thousand, Four Hundred and Fifteen). Oil production 20bopd!

    CONsolidation

    30 Days later we get a 400-1 share CONsolidation. The stock clock is reset and ‘Fast Eddie’ is rinse repeat raring to go… 82,861,576 shares now in issue. Read on it’s hilarious. 8 Weeks later ‘Fast Eddie’ places yet again! This time it’s 255,833,333 raising £587,500 shares now in issue 338,694,909 or to put that into old shares 135,477,963,600 (One Hundred and Thirty-Five Billion, Four Hundred and Seventy-Seven Million, Nine Hundred and Sixty Three Thousand, Six Hundred) and again I want bore you with the usual corporate shyster warrant packages or the bullshit nonsense about super dooper assets bought for peanuts….

    This just gets better, 10 weeks after the above ‘Fast Eddie’ (I shit you not) places again! This time it’s another 287,000,000 shares raising £861,000 taking the shares in issue to… Wait for it … Wait for it… 604,156,447 or to give you the figure pre-CONsolidation 241,662,578,800 (Two Hundred and Forty-One Billion, Six Hundred and Sixty Two Million, Five Hundred and Seventy Eight Thousand, Eight Hundred) Usual corporate warrants for the corporate rats.

    Now the absolute killer here if the above wasn’t enough to scare the living daylights out of you, is this!!! On the 17th November 2017 ‘Fast Eddie’ is at it yet a fooking gain. He raises £2,000,000 via the issue of 432,692,304 Placing, Settlement and Adviser and Deloro Investment Shares with the usual corporate shyster warrants. Mayan’s issued share capital is now back over 1 Billion!!! It’s 1,166,335,931 to put that into the old shares 466,534,372,400 (Four Hundred and Sixty-Six Billion, Five Hundred and Thirty-Four Million, Three Hundred and Seventy Two Thousand, Four Hundred). Give or take the odd share….

    So, Dear Align Research you’ll have to forgive me for not being a believer in this POS, your research And ‘Fast Eddie….’ Who as you know, has been covertly operating on twitter via a private twitter group ramping and briefing well-known pump and dumpers in that group, exhorting them to buy/hold the stock while hinting of fantastic news and getting said P&Ders to retweet his tweets and sing the Mayan song to all and sundry.

    ASPHALT RIDGE The Latest ‘JACKANORY’

    So, I ask again just where is the cash coming from to progress Asphalt Ridge? Bearing in mind that $1,005,000 has already gone from the November 2017 £2 million placing while Mayans PLC costs and capex for their ‘other’ shite onshore USA assets, such as Zinc Ranch, which the company are actively trying to flog as I type, for a few hundred thousand dollars. Pray do tell me? Let me answer that Vulture Finance/Placing.

    I’ll remind investors of the hastily formed Deloro company deal that gives Mayan and ‘Fast Eddie’ access to 8.3% of a potential 49% of Petroteqs’ Ashphalt Ridge, which would be owned by Deloro, not Mayan Energy! Mayans’ 8.3% is subject to the investment of $10,000,000 in staged payments by Deloro to Petroteq. Money Deloro and Mayan simply do not have, that is a fact.

    The Asphalt Ridge project is being paid in the form of convertible loan notes, payable as follows: As announced months ago 16th November 2017.

    Tranche 1 of US$2.5million due immediately to fund completion of plant upgrades and start-up of initial production;
    Tranche 2 of US$3.5million due once plant for more than 30 days is operating at greater than 1,000 bopd, and
    Tranche 3 of US$3.95million due on or before by 1 June 2018.

    We know that Tranche 1 was paid in November 2017. Deloro, by their own hand, admit that they had $2.900,000 in cash and Mayan shares. $2,500,000 of that cash has gone. It went last year in November. $3,500,000 is now outstanding for Tranche 2. Where is that money coming from? Then there’s Tranche 3 $3,950,000 where is that money coming from? Mayans’ investment if they actually achieve 1,000 bopd and providing they pay all the $10,000,000 is 83 bopd? No it’s 8.3% of Deloros’ 49% which is circa 40bopd. Laughable!

    RAMPING

    Let me tell you why ‘Fast Eddie’ is ramping to fook on twitter and in private twitter chat groups. He’s trying to keep the Mayan SP up so that Deloro can dump (sell) the stock HE gave them as part of the Asphalt Ridge deal! 64,102,564 shares and to get yet another Placing away in the not too distant future. It’s an orchestrated, corporate, shyster, deliberate case of wholesale market manipulation.

    The Mayan CEO Eddie Gonzalez ‘Fast Eddie’ has issued in old shares after only 16 months in the job and countless asset twists and turns Four Hundred and Fifty Five BILLION shares! Placings aplenty and there’s another one being lined up.

    Now hopefully you will all understand my rather cynical view of ‘Fast Eddie’ and his Board, who’ve tried to use the good reputation of Align Research to HOODWINK the market! I respect Richard Jennings he’s one of a few good guys out there, but on this take heed: get yourself and your company as far away from this POS as is humanly possible. Otherwise your reputation and credibility will be damaged.

    As for ‘Fast Eddie’ and Charlie woods, you’ll remember him he’s been ‘at it’ since day one, I’d expect that the thousands of UK Investors who’ve been rinsed out of tens of millions of pounds would like to ‘metaphorically’ take out, shoot and chop the Mayan board of shysters into Four Hundred and Sixty-Six Billion, Five Hundred and Thirty-Four Million, Three Hundred and Seventy Two Thousand and Four Hundred pieces of the rotten meat they are, then feed them to the fishes……

    Viva!

    Daniel

  • Nostra Terra Fantasy RNS RAMP! 100 YEARS TO GET OUT THE ‘POSSIBLE’ OIL! PRE-PLACING RAMP! SHOCKER

    Nostra Terra Fantasy RNS RAMP! 100 YEARS TO GET OUT THE ‘POSSIBLE’ OIL! PRE-PLACING RAMP! SHOCKER

    Here we go yet again Nostra Terra Oil & Gas (LON: NTOG) CEO the lying deceiving scumbag Matt Lofgran, the man who shorts his own company and pays a self-confessed drug dealer to write his RNS’s has released another ‘corker’ today!  The druggie boy is now and has been ramping to fook on twitter and his no google ranking ‘valuethemarkets’ website, bought from that other ‘credible market coNmentator Mikey the strangler, shouting from the rooftops what is quite frankly wholesale lies and fraud to pump up NTOG pre placing.

    Apparently there’s been an increase in the oil reserves at one of his Stripper Well assets. Pine Mills. You’ll recall what stripper wells are? Wells at the end of their economic life.

    The scam being perpetrated here has been going on for so long it’s now an open, running, pus filled sore on the AIM market.

    Future potential upside in the Woodbine-Wagoner;
    The Tom Pepper of Tom Peppers is that there’s  “1.39 million barrels gross recoverable “Possible” reserves, “Internal assessment” based on an existing independent study” At 3.5 barrels of oil a day because that’s what is being produced per stripper well at Pine Mills, it would take 100yrs to extract the fantasy figures ‘Heralded ‘ today. It’s a big fat pre-placing whopper!!

    I draw your attention to the three words. One is ‘possible’ the other two are ‘Internal Assessment’  The translation is thus ‘possible’ because we can’t say definitely because we have no data whatsoever to prove it. ‘Internal Assessment’ This is what WE are saying IN-ORDER TO RAMP THE SP. Wholesale bullshit.

    Of course what they’re not saying is that there’s no cash and the company is in debt to their own Directors who now basically have to fund the business because no sensible investor would touch it with a bargepole. The only people in this travesty of a ‘Tale Tale’ are the Pump & Dumpers, who basically dictate the SP etc.

    Now we can all see the P&D going on here. For instance the 53% Permian play $40,000 field ‘Twin Well’ drill. Being spun as a major oil find. This is a ‘Stripper Well’ that will produce circa 35bopd at best!!! 53% of that is about 18 barrels of oil. Of course the delay in the official numbers is caused because yet again this is a stripper well and needs critical care to get it producing.

    When the ‘scores on the doors ‘ are released there’s going to be an almighty crash back to reality here.


    You have all been warned….


    Viva


    Daniel

  • Nostra Terra Oil & Gas TwinWell Gusher? My Arse!!!!

    Nostra Terra Oil & Gas TwinWell Gusher? My Arse!!!!

    Today is a wake up call for all the Mug punters who are currently ramping that well-known POS Nostra Terra Oil & Gas (LON: NTOG). Run by that well-known shyster the shorting CEO and proven scumbag Matt Lofgran. Who by the way pays the likes of Druggie boy Mr Matty Ben(t) Turney share-holder cash to write their RNS’s etc. Apparently they’ve struck oil at their Permian basin twin well drill……. Turney and his CONpadres have been bigging up the oil deliberately mis-leading the gullible and naive.

    Now a word of caution to those who’re running with this ‘Jackanory’.  Here’s a question that some seem to avoid answering. Just what do you get for $40,000 in the US onshore oil and gas market? Well here’s the answer. Stripper wells. Yes you get 53% of a stripper well field.

    Now anyone who thinks that a well that has basically already been drilled by previous operators who decided to offload 53% of their field for $40K is a life changing gusher is in for a big kick in the teeth.

    Ramping Bullshitter Lofgran!

    The rule of thumb in the O&G space is thus; when a company hits a gusher they get the news out immediately. Because it is deemed by their Nomad, to be material and market sensitive. When as we’ve seen many times over many years, Such as #Angus Energy, #Range Resources, #UKOG #Mosman etc. A company doesn’t release the ‘Scores on the doors’ they prevaricate then that’s because the delay is caused ‘because’ the numbers are ‘Piss Poor’. When you’re involved with ‘PissPoor’ delays are caused by ‘artificial lift’ processes, pump jacks (Nodding Donkey) having to slurp up as much of the stripper well dregs as possible.

    The numbers on previous production are circa 3.5bopd yes an earth shattering three and a half barrels of oil per day from the whole of the lease. So let’s just forward think this even at 100bopd #Shyster Lofgran get’s 53bopd which sharply declines. But in reality the company are telling people 25-35 bopd so 53% of 25-35bopd is what? Yes exactly not very much. Which is exactly what one gets for $40K in the good old USA!


    You have all been warned.


    Viva!


    Dan

  • Nostra Terra Oil & Gas. 25,872,746 MAGP Have Vanished! Explanation Now!

    Nostra Terra Oil & Gas. 25,872,746 MAGP Have Vanished! Explanation Now!

    It’s groundhog day every day at the piss poor Nostra Terra Oil & Gas (LON: NTOG). Todays expose is like all the rest a real shocker. So much so that I have emailed my research to their Nomad and the AIM Regulation team.

    Quite simply where has 25,872,746 Magnolia Petroleum shares vanished too? MAGP shares are currently missing. Where are they? You can do the maths below. The simple fact is that there are MAGP shares unaccounted for. Maybe the shyster and shorting CEO and ex estate agent has forgot. It could be an ‘honest mistake guv’ or has he trousered them for himself or used them to pay off debts or maybe in the end of the long convoluted and disastrous deal that culminated in an embarrassing withdrawal of the Lofgran requisition letter, his shyster lying brain has imploded under the weight of telling so many lies? Who writes the RNS’s? Oh yes it’s Mr Ben drug dealing Turney! Not getting value for money there Matty! Some one has got some serious questions to answer. A full and frank clarification is needed here ASAP! We don’t want to hear that ‘David Blaine’ popped in to show you a few magic tricks either!

    Missing MAGP shares. Where have they gone? Speak Up Scumbag!

    Come on Lofgran speak up! Get out an RNS on what’s happened to 25,872,746 Magnolia Petroleum shares that you have failed to account for. How has your Nomad, Strand Hanson failed to pick up on this? Why was it signed off? I’m sure there’s a logical explanation. Pray do tell us all…..

    Time line. On the 26th May 2017 NTOG supposedly bought 204,226,748 MAGP shares

    On September 4th 2017 NTOG announced they’d sold 26,354,002. This left NTOG holding 177,872,747 MAGP shares
    On October 17 2017 an RNS Completion of Disposal of 152,000,000 dropped. Now you can all see the problem. There are 25,872,746 MAGP UNACCOUNTED for. The RNS makes it crystal clear NTOG has sold all it’s MAGP shares. But the numbers do not stack up. They are 25,872,747 shares light. Where have they gone?
                204226748      Bought
                26354002        Sold
                177872746      Left Holding
                152000000     Disposed
                 25872746      Vanishing Shares!
    Now I expect we’ll get some weasley worded clarification RNS spinning a tale etc. But I for one predict an NTOG Clarification RNS!
    Viva
    Dan
  • Nostra Terra A Dose of Reality BMD Style! £90 Grand Left! Where Have The 10s of Millions Gone Lofgran?

    Nostra Terra A Dose of Reality BMD Style! £90 Grand Left! Where Have The 10s of Millions Gone Lofgran?

    Before I start the next ‘Rip’ of the shyster that runs Nostra Terra Oil & Gas (LON: NTOG), I’m going to tell you a real life short story. So bear with me as it’s indicative of the dirty deceits perpetrated by the shyster Matt Lofgran, on UK Retail Investors.

    The story of Gesseppe ‘Ges’ was a small time investor in Nostra who believed and invested. Ges was and is an Old Age Pensioner. Ges put, (to him) a hefty sum of his life savings into NTOG, Ges was wiped out. Ges began to investigate in-depth and posted his findings online. Ges recently got a solicitor’s letter from NTOG threatening him trying to force him to ‘shut up’. I know Ges and have spoken to him. He manages to survive on his state pension and what little he can earn via ‘odd jobs’ life is hard for him but he is an intelligent proud man in the twilight of his years who has suffered horrendously at the hands of what is little better than a Fraud. There are many Ges’s out there which is why I take it upon myself to expose people like Matthew Lofgran and his band of Merry Pump & Dumpers. So when you’re reading the next Ramptastic Horse Shit of an RNS. Remember Ges….

    It was with a wry smile that I read last weeks ramptastic NTOG RNS on a hedging facility. The  pump & dump crew employed and associated with Nostra Terra Oil & Gas was out in force. The SP rose to way over 3p from 1.25p. Suckers were suckered in, greed often gets the better of the human spirit, common sense goes out the back-door, but as sure as night follows day the truth always wins. That truth landed a day or so later when the Nostra interims were announced. Losses of £16,000,000. Liabilities of  £1,092,000 and CASH in hand of £94K. Of course that was the financial position of this POS on 30th June 2017. A full three months have elapsed since then. Now I’m going to take you all on a journey and tell you all the story of Nostra Terra Oil & Gas since Day1. The day that this God awful shite company was taken over by Lofgran the shorting CEO and proven liar. It’s a forensic analysis that all should read.

    The convoluted story here started on June 30th 2009. Since that day eight years ago the ‘Jackanory’ has had many changes, nomads, brokers, assets, wells, promises, false dawns, directors, advisers, geological plays, countries, US states of operation, debt providers etc. The story-teller in chief and the only fixed point of reference is the man running the scam/lifestyle company; Matt Lofgran. Who uses any and every platform known to man to ramp, lie & deceive, to get placing cash in. Twitter, Presentaions, Vox pumpcast, online shyster bloggers, podcasts, etc.

    Since day one Lofgran has raised over £11,000,000 pounds via approx’ fourteen placings which doesn’t include their debt facility finance such as the $25m Texas Bank RBL facility, the $3M and $5M YA Global Master SPV Ltd Loan/SEDA facility, not to mention the £235,000 loan provided by Devon Energy Ltd. None of this includes the millions of dollars of oil revenue also skanked away lining the pockets of the corporates, Lofgran and paying debt fees and borrowings just to tread water backwards!

    The shares in issue from IPO AND pre consolidation went from 301M to a thumping 4,110,347,691 Yes over four Billion shares! The dilution and value destruction here is incredible. But it gets even worse. Post the CONsolidation Lofgran has issued 38,359,817 shares. To put that into perspective pre the 50-1 CONsolidation that is another 1.9 Billion shares or circa another 50% dilution post CONsolidation! And in-order to keep lining his pockets there will be more placings and ‘Jackanory’.  It’s keep the lights on at all costs to financially rape UK Investors.

    If you had invested £500,000 in the 1p Placing on the 3 December 2009 your 50,000,000 shares would now be 1,000,000  shares with a value of £1800 quid!! with an sp of 1.8p. The value destruction of the Lofgran stewardship is one of gargantuan proportions! The example above can be extrapolated from any ‘Placing Point’ in time. Take any placing pre or post CONsolidation and each and every one is massively underwater! The company had £94 grand left 3 months ago! Where has all the tens of millions of pounds gone? They have £90 fooking grand left!!! with liabilities running at eleven pounds to every £1 held!!! This company isn’t an investment. It is a vampire blood sucking entity run by corporate leeches slurping the life blood of UK Retail Investors. It needs a ‘Regulatory’ Stake through the heart! It’s insolvent without placings.

    Lofgran has got away with monumental corporate shysterism by constantly flipping the story and leaking information to his Pump & Dump supporters. You can see this every time there’s a rise in the SP. An RNS lands, it’s as regular as clockwork. It’s been eight years of bullshit. Bullshit specifically designed to keep the body politic alive so that Lofgran and his corporate chums can feed off the body! He’s trousered millions of dollars! At the expense of gullible UK retail investors. Even now the Poltroons and Melts are still in ramptastic mode posting utter drivel trying to sucker in so they can exit. By the way.if you’re looking for cash spent on offices you’ll be hard pressed to find it. There are no offices, Nostra Terra is run out of a rucksack. From the home of Lofgran. No secretary, no fax machine, no company telephone number, no coffee machine. Zippo…

    Look at how the story keeps being changed. We’ve had the Hoffman Field, Bloom Field, Koelsch Field, Boxberger Field, Oktyabrskoe field, Trapp  field, Liberty Well Utah Overthrust Paxton thrust field, Giddings Field, Woodlawn field, Manderson Field, Cottonwood Creek Field, Pine Mills Field, about the only field we’ve not had is Anfield!

    As for the geological formations and basins and prospects trumpeted out they beggar belief. I can’t list them as I’d be here for days!!! Take a look at the wells which are by no means an exhausted list but should give you a flavour of the constant ever-changing ‘Jackanory’

    We’ve gone from Austin Chalk, Liberty , Vintage Hills, Nesbitt, Agnello #1 Bale Creek, Verde1, Warrior Prospect, East Ghazalat, Chisholm Trail, High Plains Prospect, High Plains Prospect – Additional Interest Acquired, Verde3, Verde 2 Chisholm Trail 1, Chisholm Trail 2, Chisholm Trail 3, Chisholm Trail 4 5 6 7 etc…… The  Jones 1-5H well, The Holt Well, The Gant Well, The Tharp 2-26H Well, The LSEPMU 7-3H Well, The Mel B 1-33H Well, The  Katy 21-1H Well, The Bugg 1-25H Well, The Oswald 1-27H Well, The Foster 31-1H Well,  The Gant 1-22H Well, The Curly 1-26H Well, The Wilson 3-8-5H well, The Jones CT8 Well, White Buffalo Prospect, the Big Horn Basin, Bollenbach 1-33H Well, San Miguel Prospect, Don Pedro Prospect, Paw Paw Prospect, North Dabaa 1X Well, North Dabaa 2X  Well etc. ect. etc….. The list is endless and it goes on and on. I could list each and every one of the piss poor stripper wells and marginal plays such as the twenty Pine Mills Stripper wells. But I’d be here till Xmas.

    As for the US states and countries of operation that’s another ‘Jackanory’ in itself: Texas, Kansas, Utah, Oklahoma, Egypt, Ukraine, Colorado, Tunisia, Oklahoma ‘In House’ play, South Eastern Colorado, Wyoming, South Texas, North Africa, New Mexico. The constant twisting and turning of the ‘Jackanory’ is indicative of total failure and of a man who will do and say anything to keep the lights on so he can keep the lifestyle he’s become accustomed to. The ex estate agent is’nt an oil and gas man. The eight years of total failure proves it. Beyond any doubt whatsoever. He’s a charlatan!

    Of course there’s going to be yet another Placing and another Placing. NTOG Can’t self sustain and never will because it’s a sham company run for the benefit of Lofgran. Not the share-holders who’ve been wiped out more times than I’ve had hot dinners! The history here ramp, promote, lie, leak, short, pump and dump rinse repeat… The controversy, lies, shorting of his own stock, secret payments and the deceits has made this company toxic. I assign no value whatsoever to their ‘Assets’ as the capex needed to keep them going by far out-stretches the return. Which is why they have £16,000,000+ of losses, your losses. The only value here is listing value. Nostra Terra are worth about £400,000 on a good day lock stock and barrel. That’s sub half a penny. 0.30p a share and that is generous, very generous.

    If this POS was a race-horse it’d been taken out and shot to save on Veterinary fees years ago….

    Bear in mind when you hold this stock you will lose your cash. History lesson and life lesson… The plain fact, if you hold this POS at any time the SP is rising you’re in danger of a Placing wipe-out. Suffered by everyone and anyone daft enough to hold. Remember ‘The Story of’Ges’….’

    Bargepole.


    Viva


    Daniel

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights