Oh what a difference a day makes… Yesterday the lying CEO of Nostra Terra Oil & Gas (LON: NTOG), Matt Lofgran the ex estate agent released an RNS. In yet another attempt to ramp the company share-price in-order to get the NDOG SP to a place that could allow him to pass the begging bowl around yet again. Make no mistake NTOG are desperate for cash and running on vapours. They will place as soon as they can get one away.
Liar! Liar! Shorts his own company! Secret Payments to Ben(T) Turney
The history here is one of total pump & dump, lies, ramp, secret payments to twitter supporters, shorting their own stock, placing upon placing, dilution upon dilution, consolidation upon consolidation, debt upon debt, flogging off assets to keep the lights on as well as failing to report the 50%/60% decline in East Ghazalat oil production, we’ve had the utter fantasy that is Pine Mills, a clutch of Stripper Wells onshore USA marketed as the next best thing since sliced bread. Stripper Wells are marginal wells deemed at the end of their economic life. Each well at Pine Mills is producing a few barrels of oil a day. They need constant workovers which again is capital intensive. The CAPEX spent by far out strips the return. They will never be in profit in the near, not so near or even the foreseeable future. Then there’s the ‘Eye of Sauron’, yes the AIM Regulation Team who’ve been inundated over the last 2 years with complaints regarding the Shysterism perpetrated by Lofgran. The exposes on shorting his own company, making secret payments to the self confessed drug dealer Ben(T) Turney. Jesus the list is endless.
The usual paid for mouthpieces were out in force tweeting and podcasting hammering the BB boards with the usual utter shite. The SP had a spike to way over 3p. Today the sp is in freefall as the reality of exactly what a hedging facility is and why they have to have it sinks in. They are taking on more Debt because they have no cash and production is down to slurping out a few barrels of oil out of 20/30 stripper wells. No revenues from East Ghazalat which is mired in legals, debt and accusations of fraud with a declining production of over 50%.
Nostra Terra Oil & Gas haven’t got a pot to piss in and on top of the massive Debt that they already have, they’re taking on more Debt.Their liabilities and historical losses are in the tens of millions of dollars. That is a fact. So the hullabaloo about a hedging facility can be summed up in a Nutshell. One of the terms and conditions to taking on yet ever more Debt is having the facility that helps to protect the Lender not the Company! A hedging facility works thus: NTOG pay fees to the provider of the hedging facility to insure that if the oil price drops below lets say $50 per barrel to $45 then the provider of the hedging facility makes up the difference i.e. They pay the shortfall which would be $5 per barrel. NTOG have to pay all oil revenues to their new Lender to not breach the new Debt Agreement and pay their hedging fees regardless of where the oil price is. Not exactly a game changer is it? Back to where you came will go the SP. Below 1.5p. Worth about 0.50p listing value only. Beware of the ever present danger here. They’ll Place as soon as they can get one away.#POS
It is yet another ruse to sucker in the BB poltroons and Melts. There’s ‘nowt’ quite like a BB Loon they’ll believe any old shite and pile in like the uneducated lemmings they are. Just another pump and dump. The dose of reality, although hard to swallow, usually takes a few days to be digested.
Which in turn helps to flush out the stomach and we all know what comes out the other end….
“It takes all the running you can do to keep in the same place. If you want to get somewhere else, you must run at least twice as fast,” the Red Queen told Alice in Lewis Carrolls novel ‘Through the Looking-Glass’.
Which brings me on nicely to the nonsensical ramptastic horse-shit that is currently being shouted, screamed, tweeted, whispered and posted by that well-known Aussie’ bullshitter extraordinaire, ‘Captain Ramptastic’ Mr David Lenigas and his twitter morons about Angus Energy (LON: ANGUS) which now has an £85M market capital valuation based on bread and butter assets currently being portrayed as the best thing since sliced bread.
Angus Energy
Angus Energy are a tiny micro-cap UK onshore oil & gas play they have two licenses in the Weald basin. Brockham and Lidsey. I’ve met their Chairman and Founder, Jonathan Tidswell. Had a few chats with him over the years. He’s a good guy. I like him. An able oil & gas man. The real deal. But even JT will be gobsmacked at the grossly ridiculous valuation of the company. Not to mention the massively over inflated promotion that has seen the SP rise to nearly 40p! Sadly, it looks to me like JT has fallen under the ‘Svengali’ influence of the purveyor of Australian bullshit ‘Captain Ramptastic’. And, why wouldnt he? JT’s stake is currently 16%, valued at a cool £13,500,000 a lot of Wonga…….
There are so many red flags it’s hard to list them all as I’d be here for two days writing them up. It’s that bad. I’ll stick to the main ones. Just to give investors the true flavour and a dose of reality, maybe even a dose of Epsom salts wouldn’t be remiss.
Red Flags
There are NO billions of barrels of oil coming onstream here at Lidsey/Brockham. (Just as there are NO billions of barrels of oil coming onstream at Horse Hill). Regardless of the ramping and gross massive over promotion, indeed there are no hundreds of millions of barrels and again indeed there are no tens of millions of barrels of oil coming on stream here. Now readers may rightly ask, how I can make those statements. Well it’s easy when you know how to research and fundamentally read a balance sheet.
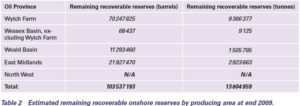
Starting with: The World Leading GeoScience Centre, The 2009 British Geological Survey results which ‘Objectively’ state; “The remaining recoverable oil reserves in the ‘whole’ of the Weald Basin were estimated at one and a half million tonnes. The conversion of that is 11,293,430 barrels, (Eleven million, Two Hundred & Ninety Three, thousand barrels of oil). Yes, folks that’s it 11.29M barrels of oil recoverable in the WHOLE of the Weald Basin! Investors and purveyors of ‘Subjective’ ramptastic shysterism alike should take note of what The British Geological Survey are saying. My money is on them.
Now if you read through the NEX Bond £3,500,000 Memorandum, all 97 pages of it you’ll find so many red flags that one would be hard pressed to build sand-castles to stick them atop. I suggest each & every one of you read it otherwise each & every one of you will continue to be ‘Blinded’ by the shysterism being used to create the liquidity for the corporate hyenas to sell their stock and exercise their warrants. (More of which later in this epistle to the morons). The Truth will set you free and more than likely save you from the massive fall in SP that will hit once the ‘scores on the doors’ land vis-Ã -vis bopd. Not to mention the highly dilutive Placing that is currently being lined up. Read HERE.
Brockham & Lidsey Production
The truth of previous oil production is Lidsey 25bopd; (12 bopd net to Angus). Brockham 35 bopd (21 barrels net to Angus). After the drills/workovers production according to the Xodus CPR, could be; Lidsey 279 bopd (167bopd net to Angus) Brockham 93bopd (55bopd net to Angus) The best-case scenario and I’m being really generous here, not including the decline rates which are over 50%, is 223bopd net to Angus. The on-going OPEX & CAPEX needed to keep production at this level would in all probability render them close to un-economic. These are facts that have been deliberately obfuscated by ‘Captain Ramptastic’.Jonathan Tideswell himself has stated “Following the conversion of the Brockham well and drilling of the Lidsey-2 horizontal producer the Group expects to have a net production by the end of the next reporting financial year of approximately 150bopd, in line with the P50 production guidance as given by Xodus in their CPR”. Now that’s an awful big change from the over promoted IPO presentations and the ramptastic shite of Mr David Lenigas, is it not? Not exactly earth shattering, is it?
Angus Fundamentals
Angus Energy is grotesquely overvalued. A market cap’ of £85,000,000 for a company that may produce 150 barrels of oil from piss poor Bread & Butter UK onshore assets is Alice through the Looking Glass, madness.
The fundamentals here are thus; Angus had on Initial Public Offering (IPO) £3,050,000 (net) in cash. They then raised a further £2,000,000 (gross). As at 31 March 2017 the Company had cash of £2.3M. Again, being generous, ’cause I’m a generous type, I won’t take out the fees of at least £100K from the gross £2,000,000 raised in February 2017. The six-month cash-burn up to March 31 2017 is £2,750,000, which equates to a staggering £458,000 per month spent up to March 2017. Cash was £2,300,000 as of March 2017, 6 months have now passed. So how much of the £2,300,000 is left? Answer Zippo!
Even if you put their cash burn down to £350,000 per month for the period up to Sept’ 2017 this would leave the company with net cash of circa £200K. Are you all getting the picture now? Do you smell the placing?
I won’t put in any liabilities etc. Let’s make it really simple. Asset Value booked in at £2,300,000, cash in hand circa £200,000. Total £2,500,000. Production zippo. The ramped up ‘Hope Value’ is a jaw-dropping £82,500,000. Let’s put some common-sense on the ‘Hope Value’ and assign it a ‘generous’ £5,000,000. That would give a Market Cap’ of £7,500,000 extrapolated into a share value of 3.10p. Let’s double the ‘Hope Value’ to £10,000,000 for fun, 6.2p gives a £12,500,000 Market Cap’. The disparity between the current reality of the Net Asset Value for a micro-cap that may produce 150-223bopd that will decline substantially is humongous! Angus Energy isn’t worth 35p/36p a share! It’s a ramped up uber non-producing micro. With a potential 150-223 bopd. That’s it folks! The value of their shares is 3p at best!
“Hang on you shorter Levi, What about the £3.5M NEX Bonds?”
Firstly, I do not short. That is a fact. I report it as I see it. Anyone with half a brain who takes the time to read the NEX Bond Memorandum will learn that the Bonds can only be issued in tranches and those tranches cannot be issued until, I repeat ‘until’ production starts! Which is why there’s been 7 RNSs, each one announcing to the ‘lumpenproletariat’ (Google it) that the date of issue has been put back. Those Bonds are secured against ALL the companys’ assets, production and SHARES. No production No Bond issue. Can you smell the Horse-shit now?
There will be no Bond issue until production starts. Tranches will be issued in respect of how much free cash is generated which is minimal on 150-223bopd. The AIM Cesspit professionals know there’s a Placing about to drop. It’s the great unwashed, who are being spoon fed Kimmeridge Black gold fairy tales, that don’t!
Now I’m hearing whispers & rumours that investors are being soothed with sweettalk from people who may be from the company or not, or involved in some way with the company, or not, intimating through ‘back-channels’ that they won’t Place. This is ‘porkypies’. I hope that those who may be getting told there’s no Placing, fully funded etc. Upon getting shafted immediately report ‘those’ who may have told them such utter lies. You wont have long to wait. A Placing is imminent.
Kimmeridge Fairy Tales
The share-price is 35.75p it has been ramped up to high heaven. This is a deliberate ploy by the Lenigas ‘Kimmeridge Fairy Tale Gang’ operating out of the corporate Boiler Room that is Jermyn Street London. The mutterings, allusions & twittering’s of untold Kimmeridge clay/shales black gold, billions upon billions just around the corner Tweets, BB posts, CPR and RNS teasers of Kimmeridge tests, allusions to UKOG etc. Nudge! Nudge! Wink! Winks… This has been done by the promoters to deflect away from the cold hard financial reality that is Brockham & Lidsey. These are ‘bread & butter’ onshore assets and they will never ever produce anything other than piss poor, OPEX & CAPEX expensive, oil that declines very rapidly and needs cash thrown at them to maintain production.
‘Captain Ramptastic’ David Lenigas ‘Modus Operandi’
Ramptastic Bullshitter X 140+ Companies
Now I don’t propose to go in-depth into the Modus Operandi in this piece, that will be dealt with in greater detail over the coming months. Brief over view is all that’s needed here. ‘Captain Ramptastic’ has been involved with over 140+ companies in various roles, that figure is probably much higher.
Each and every one of those companies has been massively over-promoted whether that be the greatest gold mine in Wales: Stellar Resources. The world changing eco Boiler: Inspirit Energy. A super dooper airline: Fastjet. Feeding the African continent: Afriag. Cuban Oil & gas oops tourism, oops again, now medicinal cannabis: Leni Gas Cuba. Untold Mexican lithium riches of the battery world, and the Internet of Things: Rare Earth Minerals. Trinidadian black gold riches: Leni Gas & Oil. Tanzanian, Spanish & global portfolio of oil & gas and now helium (Laughing Gas): Solo Oil. The greatest African conglomerate of hotels, ports and agricultural businesses: Lonrho. Onshore UK billions I tell ya billions of barrels of oil in the Weald: UKOG. Diamonds are forever: River Diamonds. That metamorphosed into a Bonanza gold mine: Vatukoula Gold Mines. Fly me to the moon crash and burn: Norse Air Limited. More rare earths. So rare I’ve got two companies: Bacanora Mineral Ltd.Rub in my magic face cream it works wonders for anti-aging: Evocutis. That didn’t work let’s change it to investing in resources: Gunsynd. Now I could go on and on with this list but as I said that’s for another major expose on David Lenigas. But I think that gives you a taster of what this fooker is all about. Ramp, Pump, Dump, Place, Rinse, Repeat.
Each and every company that this man is involved with is ramped to death and each and every company ultimately bombs. Peppercorn stock and warrants are sold into the liquidity that the ‘Over Promote’ causes. How many Angus CONsultants warrants does he have? How many shares has he sold into the pump? David has said he doesn’t have any. Is this the truth? Bearing in mind Doriemus and his recent UKOG warrants forced admission. Placings are used to refill company coffers to pay ‘Captain Ramptastic’ and his cohorts’ Executive Remuneration and to keep the story going of untold riches for investors. Dilutions, placings and consolidations. The people involved with the ownership of the companies, such as the 4% of the UK Energy needs for the next 30yrs ‘Captain Ramptastics’ BB/HH UKOG fantasy, are a complex web of companies/shareholders, a trademark of Lenigas’s affairs. The dreams of UK Investors are always left shattered to smithereens. The transference of wealth from the naive investor to the Corporates complete. Job done Mr. Lenigas quietly exits and leaves the company mouthing some bullshit. Not one of the companies has ever made it to the Big Time.Angus Energy are but one of the many ramps.
David Lenigas has made tens if not hundreds of millions of pounds massively over promoting piss-poor AIM penny stocks. He’s good at what he does. A truly gifted Promoter but that is all he is a Shyster Promoter. The life style is large, Yacht in Monaco, Offices in St James City of Westminster, property in Monaco, properties in London, Australia, 1st Class flights, hotels, bulging bank accounts etc. Tis a champagne lifestyle. He uses the same people over and over again. The cross pollination of companies and directors is well known in the City of London. The usual suspects take their cut and get ready for the next one.
Now if the Fat Promoter would like to challenge that in the High Courts of London then go for it David. I will gladly oblige you and expose you for exactly what you are: A corporate Aussie’ bullshitter, a scammer taking advantage of gullible naive UK Investors, citizens of my country. Bring it on Mr Lenigas.
Angus Energy. Without a ‘G’ is Anus.
Compare An(g)us Energy to let’s say mmmm…… Zenith Energy (LON: ZEN). They’re a producer churning out 350bopd, their Azerbaijan field is way bigger than both of Angus’s and they have half the shares in issue than Angus. The current share price is 7.25p. The Market Cap’ is circa £9M. The difference is that Angus have no production, yet, Zenith have. Zenith doesn’t have the sustained massive ramp/promote. Angus does. By the way Angus only just scrapped onto AIM as a marginal company based upon their IPO and what Xodus says in the NEX Bond Memorandum.
That’s not all Xodus say, in their Executive Summary, page 29, “Xodus has read the Nutech report. Although it presents an interesting comparison with the Horse Hill-1 potential, Xodus’s view is that there is insufficient information available to provide a credible assessment of the petroleum volumes in place and/or recoverable from the deeper reservoirs that is in accordance with the PRMS standards and AIM guidelines”they have put clear water between the wild speculation and manipulation that is being orchestrated on the ‘Billions I Tell Ya’ of Barrels Kimmeridge ‘Hail Mary’ play. Furthermore, they conclude Page 31, that the economics are thus: “An economic analysis was carried out on the Reserves on the Brockham and Lidsey fields. The results are provided in Table 1.4. The Reserves have a small positive Net Present Value (NPV).Now that’s not exactly a ringing endorsement is it folks?
Apart from the fundamentals, which are desperate, Angus have also got to pay their share of Holmwood Licence. Part of the agreement to acquire 12.5% of the Holmwood Licence, the Group agreed to pay certain historic costs incurred by Europa since 1 February 2016 (representing £26,563 of net cost to the Group) and 25% of the costs of the Holmwood-1 exploration well up to a gross well cost of £3,200,000 (representing a potential net cost of £800,000 to the Group) along with certain further costs the details of which are set out in the Xodus Memorandum. Placing? No of course they won’t they’ve got a ‘Money Tree’ from Teresa May! You’re having a laugh aren’t you? “It is therefore difficult for prospective investors accurately to evaluate the Company’s business and future prospects. There can be no assurance that losses will not occur in the short term or that the Company will be profitable in the future“
It gets worse does Xodus Page 45 Contractual documentation: “The Angus Group does not have in its possession executed counterparts of certain of the contractual documents relating to the acquisition and disposal of interests in, and the operations of, its oil and gas assets (including the Licences), the terms of which are referred to in paragraphs 2, 3 and 4 of Part I and 13.3 and 13.7 of Part VI of this document”.On page 51, this is a real killer and an eye opener “Exploration, development and production activities are capital intensive and inherently uncertain in their outcome. As a result, the Company may not generate a return on its investments or recover its costs and it may not be able to generate cash flows or secure adequate financing for its discretionary capital expenditure plans”
I could talk till the cows come home extrapolating literally dozens if not hundreds of caveats that ‘Captain Ramptastic’ doesn’t want you to read. What we have is a massive, orchestrated pump and dump of a bread and butter asset/s using smoke and mirrors while intimating Kimmeridge black gold, cherry picking a hypothesis. The Xodus report makes it crystal clear. There will be no Kimmeridge shale black gold. What the Angus Rampers are doing is constantly ‘alluding’ to Horse Hill & Broadford Bridge which is in itself a crock of shit.
If I was in profit here now knowing what I do I’d get the hell out and sell. That’s what ‘Captain Ramptastic’ and the Horse Hillsters are all doing. Theres a Placing coming and make no mistake about it. It is Imminent!
Massively over hyped, worth about 3p on a drug fuelled drunken day!
Remember what the Police always tell people to avoid being a victim of scams. “If it sounds too good to be true it probably is” On that cautionary saying I shall leave you all to ponder this; The David Lenigas track record V The British Geological Survey. Place your bets..
Just when you think life at the disgraceful Nostra Terra Oil & Gas (LON: NTOG) couldn’t get any worse yesterday they announced a keep the lights on placing for £500,000 part of that embarrassing ‘barrel scrap’ is being raised through the Teathers crAp oops sorry the Teathers App. What that should tell investors is that Nostra Terra is ‘out of control’. The current Board of directors are a joke. Where is the independent oversight from the Board? Having to go cap in hand to a busted Company for a bail out placing!
Placing
I’ve consistently warned people that they were after a placing. Indeed it was this site that exposed their last cack handed placing that cratered Read HERE. You know the one where Lofgran said; “A placing of new stock was in contemplation on 17 February 2017 but that the board of Nostra Terra has decided now not to proceed with the placing” the truth of that was this. They couldn’t raise the cash because there was no appetite and the share price had gone below the placing price. It blew up!
Leaking of Inside Information
It’s blatantly apparent from yesterdays drop in the SP prior to the after market close RNS that NTOG is being influenced by well known Pumpers & Dumpers. Matt Lofgran, a man who has deceived investors for years and even loaned HIS stock to YA Global to short his own Company to the detriment of his own share-holders, has lost control of the Company. That drop in SP was a leaking of inside information on the placing. It should be investigated.
When a CEO, who is mired in controversy, has to rely on such desperate measures as using an online App to raise cash, at a discount and throw warrants in to pull them out of the financial cess-pit to keep the lights on for another 3 months then the end is nigh folks…. 12 people used the App! Who were those people? P&Ders! It is bankrupt morally and even more importantly close to financial ruin. There is very little left in the kitty. It is close to Bankruptcy. Where has all the money gone? £500K will get them another 3/4 months before they have to raise capital yet again at a discount. Investors have lost count of the amount of placings this POS has done. The figure in pounds sterling must be in the tens of millions. The erosion of value here is running close to 90% post consolidation which doesn’t take into account the previous dilution over 7 years. It is horrendous. It is a scandal. The regulators should step in and close it down.
The Egyptian Nightmare.
NTOG Investors Sucked Dry!
The failure of Lofgran to inform the market that production from Egypt has halved is yet another pointer as to the duplicity of this Company. That is market sensitive news that should have been released months ago. It is deliberately being with-held to keep their share-price up. Nostra’s 25% East Ghazalat production has more than halved from 220 bopd to approx. 100bopd. No revenue whatsoever has come from Egypt. The Chinese operators are claiming drilling costs that by far exceed any revenues owed. Nostra Terra are in Default.
Bomb Shell
However it’s only going to get much worse. News has reached me that shareholder cash has been used to pay online known internet Troll/s to deliberately attack their own share-holders who have a right to question the omnishambles that is Nostra Terra. This is absolutely disgusting! Share-holder money is being used to attack their own share-holders. I have contacted NTOG and the parties involved via email. Their failure to respond speaks volumes. I will give the Company and the parties involved till Monday 24th of April 2017 to clarify exactly what has happened. If no reply is received then I will drop the bomb and expose all.
Anyone holding stock in this POS should cut and run and get as far away as is humanly possible before the next P&D and the next placing. Protect your cash, take a loss now as it’s only going to get much harder to exit. I see no value whatsoever other than shell value. Their liabilities and historical losses by far out weigh the market cap’. 1p is generous.
It’s looking very bleak at Andalas Energy & Power (LON: ADL) and It’s only going to get worse. I can exclusively reveal that Aim Regulation and their Nomad are investigating the company. Complaints have been lodged and the AIM Regulator is “Taking note” of those complaints! You can read all about some of the fraud by clicking HERE
As I watch their sp tumble towards the yet to be approved placing price of 0.20p, I can’t but help wonder what will happen when/if it goes sub placing price? The news from the city of financial shame, London, is that they will try to readjust the placing price further down! Yes suckers who are provisionally pencilled in for their allotment of stock may get more shares at a marked down price. Rumour is that it could be 0.15p.
I spoke to several sources yesterday one said that phone calls, emails and text messages had been flying back and forth over the last few days between the company, nomad, brokers and the market makers in a desperate attempt to “Hold the line” keep the SP above the 0.20p placing price. Andalas are on “Life Support”. Another had taken calls from known pumpers and dumpers screaming “Blue murder” on how they’d been “Shafted” by the brokers. A completely utter crock of shit. Brokers are their to make money for their clients, whoever they are. If there’s no stomach for a placing at nonsensical prices then they, like every business have to knock the price down. Supply and demand chaps. It doesn’t matter if you think you’ve got gold and tell every mug punter and BBLoon, what counts is what they are prepared to pay. Quite obviously no one was prepared to pay the nonsensical amounts ramped out by the pump and dumpers on social media, ergo you get what you can. The people who “Shafted” retail investors are the Board of Andalas and their pump & dump cheerleaders. We all know who they are!
Under Pressure!
Back to Fraud.
Just quite what has been going on within the company at this present time, one can only hazard an educated guess. But the pressure is now on the bullshitter and fraudster CEO Whitby to explain away (Among other things) why loans of $500,000 he made to himself via the Corsair Singaporean shell were extinguished. Get out of that one Dave and you can take the name ‘Houdini’. With the weight of 2,448,138,803 billion shares around his neck, he is sinking. I don’t think investors in AndalARSE will be seeing Dave for quite some time. Nudge nudge, wink! Wink!
It’s a shocking tale of undeclared, unsecured loans made by Dave Whitby from the coffers of the then CEB AIM listed company, which recently rebranded to Andalas Energy & Power (LON: ADL). Whitby, who is the CEO of Corsair Petroleum, a private Singaporean company, took control of CEB/ADL on June 5th 2015, on that day he also took control of £1,500,000 of placing cash raised at 0.4p. Within days he had secretly signed off $475,000 in undeclared related party payments in unsecured loans. If you think that is shocking, read on and discover who the unsecured loans went to.
I call upon AIM Regulation to immediately investigate Andalas Energy & Power PLC and it’s disgraceful CEO, the $600,000,000 fantasyman Dave Whitby for accounting FRAUDS he should be suspended forthwith! Their Nomad, Cantor Fitzgerald, Miss Sarah Wharry, (Worry) has been informed, as have the AIM Regulation Team and the FCA Market Abuse bods.
This is how it went.
On 10 June 2015 Whitby CEB/ADL issued Whitby/Corsair (Yes himself & his Corsair mates) with an unsecured loan of $250,000. The loan was to bear interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest was to be made by 10 June 2016.
On 15 July 2015 Whitby CEB/ADL issued to Whitby/Corsair another unsecured loan of $225,000. That loan also carried interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest was to be made by 15 July 2016.
Those payments are related party transactions and were never disclosed to shareholders or the market at the time they were made. Just how much of the $475,000 Whitby and Simon Gorringe, who is also on the board of Corsair and the gravy train at Andalas, have taken in payments from Whitby/Corsair is not known. However any payments made by Whitby/Corsair using Whitby CEB/ADL unsecured loan cash must be yet more related party transactions and subject to full RNS disclosure. Nothing, zippo…
The reason Whitby/CEB/ADL gave Whitby/Corsair unsecured loans is quite simple. Corsair haven’t got a pot to piss in and haven’t got any asset/s of value to secure the loans. It is inconceivable that any financial institution or business would advance approx. $500,000 in unsecured loans at 5%.
The questions are many and myriad but will have to wait until later down in this article because folks it gets even worse!
On the 19 August 2015. Whitby/CEB/ADL incorporated a subsidiary of Andalas Energy & Power, another Singaporean company called Corvette Energy (Singapore) PTE. LTD Company registration number 201532252D. Now you would think that an AIM listed company operating on the London Stock Exchange would have RNS’d such. But nay, there’s no mention of the new Whitby/CEB/ADL/Corvette subsidiary. The first inkling of Corvettes existence is six months later, buried in their half yearly report released on 26/01/2016.
Here’s the killer, we learn that Whitby CEB/ADL and Whitby Corsair have now novated and ‘extinguished’ the Whitby CEB/ADL unsecured loans of $500,000 & the 5% interest made to Whitby Corsair. “On 26 January 2016, Andalas, Corsair and Corvette entered into a novation agreement pursuant to which the Loans were extinguished and the benefit of the loaned moneys was transferred to Corvette with effect from 30 October 2015”. So now the unsecured, undeclared loans have come full circle back to Whitby CEB/ADL/Corvette. The burning question shareholders should be asking is this; How much was returned?
Remember, that according to the 2015 annual report the unsecured loans were made with these contractual conditions “The loans bear interest of 5% per annum payable on repayment of the loan/s. Full repayment of the principal amount/s plus accrued interest of 5% will be made by 10 June 2016 and 15 July 2016. There was no mention whatsoever of the unsecured loans being made for Indonesian Due Diligence. It is only when their repayment looms large is it sneaked out that ‘really guys this was for DD’. That throws up a multipule choice of unanswered questions. How were Whitby Corsair ever going to repay? Maybe they were planning to flood the market with the next tranches of ADL shares, all 93,750,000 going to Whitby Corsair that were to be awarded to them on the signing of an Indo’ deal? Did this plan fall apart during suspension? It’s 8 months after the unsecured loans were made that the repayment goalposts are moved. It is s fraud, compounded by lies!
Canada Dry! Charlatan Exposed!
We learn on the 26 January 2016 that they now were given so that Whitby/Corsair could progress Indonesian due diligence. What a crock of shit. Let’s be generous and say Maybe some of the cash was used but I seriously doubt that all of it was! Are we to believe that Whitby CEB/ADL will force their own ANDALAS subsidiary Corvette, to repay back $550,000 to themselves? When did it change? It’s a sleight of hand.No fooker is paying the cash back because the majority of it has been rinsed out by Whitby/Corsair! What is left is probably a small rump of cash that they once again haven’t RNS’d. These are ALL material transactions that have to all intents and purposes been sneaked out via the back door. They have been deliberately withheld. They are in effect ‘Back door Director loans’ that will never be repaid. Whitby should resign immediately.
The elephant in the room is this? Where has $550,000 dollars gone? Of course we’ll get the usual spin from Whitby, does anyone now really doubt that what myself and Tom Winnifrith, have wrote on this chump isn’t, in light of yesterdays absolute disastrous placing and this article today, bang on? Whitby is a corporate crook, raping his own shareholders to line the pockets of himself and his fellow Aussie crims.
I contacted Sarah Wharry the company nomad, from Cantor Fitzgerald, Sarah hasn’t responded to my questions. I wonder why? It has to be noted that Cantor were not the Nomad at the time of the undeclared, unsecured related party loans. That mantel fell to Sanlam Securities who, intriguingly, no longer provide Nomad services! I personally spoke to several big private holders of ADL stock who were again, unaware. I spoke to two CEO’s. One stated that he “would never put that to my board because it was wrong”. The other said in answer to my question, are these in your opinion related party transactions? Reply; “Absolutely – is a related party transaction and needs independent written advice and an RNS”. Both of these men are respected CEO’s.
I urge shareholders to contact the relevant authorities with the questions below. Make a formal complaint. A full investigation is warranted. Get the $550,000 dollars back. A full forensic account is needed here!
Questions for AIM Regulation, Cantor Fitzgerald and the FCA Market Abuse Team.
1/ Can you please explain why $475,000 in related party payments i.e Unsecured loans, made by the CEO Whitby CEB/ADL to CEO Whitby/Corsair were not disclosed to shareholders and the market at the time they were signed off? (There was never any RNS’s)
2/ Can you please investigate how much of the unsecured loans made by Whitby/CEB/ADL to Whitby/Corsair were paid in fees/expenses to Whitby/Gorringe by Whitby/Corsair?
3/ I understand that these unsecured loans have now, as of January 2016, been novated and moved into a hastily incorporated subsidiary of ADL. (Corvette) why wasn’t this disclosed?
4/ How much money was transferred by Whitby/Corsair to the Whitby ADL subsidiary Corvette?
5/ How much cash did Whitby/Corsair burn through before the residual amount of the unsecured loan was transferred back to the Andalas subsidiary Corvette?
6/ What has happened to these loans now, will they ever be paid back in full as per Whitby stated in the 2015 annual accounts?
7/ The Company has lied to shareholders and the market, isn’t this sanctionable?
8/ Why was there no RNS on the formation of the ADL subsidiary, Corvette? Surly this is an RNSable event?
9/ Why was there no RNS on the transfer of the loans back from Whitby/Corsair to the Whitby Andalas subsidiary, Corvette?
10/ Why wasn’t the novation and extinguishing of the loans plus interest, disclosed to the market and shareholders?
11/ How much of the unsecured loan cash went into the pockets of Whitby/Gorringe/Corsair?
12/ Why was no information ever given to the market that unsecured loans with 5% interest, were part of a due diligence effort?
And last but not least,
13/ Who signed these unsecured loans off and where was the oversight with the written legal advice as to their legality?
It is only in January 2016 some 8 months later, that we are told that; Andalas and Corsair agreed to structure the funding of the due diligence expenditures as loans (“Loans”) to Corsair” This just isn’t credible let alone believable.
It seems to me that this is, to all intents and purposes a fleecing of CEB/ADL cash by the executive and should be immediately investigated.
I put it to shareholders that these unsecured undeclared loans were in effect ‘back door director loans’ which have now been rinsed through two corporate entities coming back to ADL’s Corvette subsidiary minus a large amount of cash originally given to Whitby/Corsair by Whitby CEB/ADL.
Basically chaps where has all the money gone?
Viva
Dan
NB. This is what they said in their annual accounts: Published 21 July 2015;
On 5 June 2015 David Whitby was appointed as Managing Director and Chief Executive Officer of the Company. David Whitby is a beneficial owner of Corsair. Through his beneficial ownership of Corsair David Whitby owns 7,812,500 shares in the Company which were issued on 4 June 2015. On 10 June 2015 the Company entered into a loan agreement with Corsair to provide Corsair with an unsecured loan of USD 250,000. The loan bears interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest will be made by 10 June 2016.
On 11 June 2015 370,000,000 ordinary shares were issued for trading at a price of 0.4 pence per share, raising gross proceeds of GBP 1,500,000. Of these 50,000,000 were subscribed to by Northcote.
On 15 July 2015 the Company entered into a loan agreement with Corsair to provide Corsair with an unsecured loan of USD 225,000. The loan bears interest of 5% per annum payable on repayment of the loan. Full repayment of the principal amount plus accrued interest will be made by 15 July 2016.
This is what they said in their 2016 half yearly report: Published 26 Jan 2016;
On 5 June 2015, Andalas and Corsair entered into an agreement (“Assignment”) pursuant to which Andalas agreed, amongst other things, to undertake and fund due diligence in respect of certain oil and gas concessions in Indonesia with a view to making an investment. Initially, for administrative convenience, Andalas and Corsair agreed to structure the funding of the due diligence expenditures as loans (“Loans”) to Corsair and, accordingly, advances pursuant to that arrangement were made on 8 May (US$25,000), 10 June (US$250,000) and 15 July 2015 (US$225,000). On 19 August 2015, Andalas incorporated a subsidiary, Corvette Energy (Singapore) Pte Ltd (“Corvette”). On 26 January 2016, Andalas, Corsair and Corvette entered into a novation agreement pursuant to which the Loans were extinguished and the benefit of the loaned moneys was transferred to Corvette with effect from 30 October 2015.
Corvette was incorporated on 19 August 2015. There was never any mention in the 2015 accounts of Corvette etc Or what these unsecured loans were made for?!?
Corvette only comes into the picture when the repayment of the loans with interest begins to loom large.
What an absolute disaster it’s going to be on Andalas Energy & Power (LON: ADL) or as I lovingly call them ‘AndalArse’.
World Famous ShareProphets.
It’s been reported by the ‘world famous shareProphets’ and the highly respected and feared financial journalist Tom Winnifrith that AndalArse are placing at 0.2p. If that’s confirmed later today then that is a Disaster with a capital ‘D’ for their much maligned shareholder base. You can read what TomWinnifrith has discovered HERE
Warning.
There is a stick of financial BMD dynamite that will blow this company and Whitby wide open. That article will only be triggered if/when they relist or we get clarification of a cancellation of trading. For the time being our investigation is still on-going. The smoking gun is ready. Here’s a hint. 1/ Where has all the money gone and who has profited from it?
It’s a shocking tale of Whitby corporate deceits and financial ‘miss-direction’
The Company are at present fighting amongst themselves on how to get their hands on a substantial amount of cash which will allow Andalas readmission to the AIM. There is a substantial shortfall in funding. Retail investor interest in taking part in the £2M placing has been cool. We the Board are not prepared, at present, to put our own cash into Andalas because we are here to take money from the company and it’s shareholders. If we put our money in we will be locked in and subject to Director Disclosure rules.
Shareholders are reminded that Pursuant to the RNS of 26, October, 2015 trading in the above named Company should have been Cancelled on 22nd April, 2016.
The Company failed to publish a readmission document before 22nd April 2016. Trading of its shares on AIM should have been cancelled pursuant to Rule 41 of the AIM Rules. However a ‘derogation’ has been sought from the Aim Regulation Team. We have three working days (72 hours) which started from Friday 22nd April 2016.
Should the Company fail on readmission, it is the intention of the Board to seek Relisting for Refleecing of our loyal numpties…. Blah! Blah! Blah!
End of Message….
Now here’s what’s been going on behind the scenes.
1/ The readmission document was not submitted BEFORE 22 April 2016.
2/ There’s been no RNS on any waiver/derogation from AIM.
3/ There’s an internal war going on between the Company and it’s advisors on who, what and where they can get the cash from.
4/ According to the 26 October 2015 RNS, THEIR LISTING WOULD BE CANCELLED if they failed to submit. They have failed to submit.
5/ There’s a big internecine fight going on over funding, fees, warrants, options ‘for the boys’ (Advisors, Brokers, Board etc. )
6/ Whitby & company have so far refused to put their hands in their pockets.
Ergo you can take it as read that Whitby/ADL are in deep shit. Hence why they’ve gone very quiet.
Regardless of the outcome, it’s grim. If they come back it will be at a massive dilution and discount as the hyenas rip out as much flesh (Shares/Fees) as they can. Sympathy to those daft enough to get involved with this POS, GOES WITHOUT SAYING. That sympathy isn’t extended to the BBMorons & pump & dump crew run by Whitby. If they have to relist it will be even worse. The link to the RNS that contains the telling information is below.
Sadly for the poor souls suckered into Andalas Energy (LON: ADL) by the $600,000,000 fantasyman, CEO Dave Whitby and his pump and dump gang, news on the current situation has and is being deliberately withheld. Andalas should have released an RNS on Friday 22 April 2016, explaining exactly what the situation was within their company. The readmission document should have been published BEFORE the 22 April 2016. The key word in the RNS of 26/10/2015 is ‘BEFORE’
If Sarah Wharry, the Nomad from Cantor Fitzgerald, and the Andalas Energy fantasyman Whitby, do not update the market by 4pm this afternoon, then this site will unofficially release the news. It is a disgraceful situation whereby their shareholders are being treated as nothing other than lemmings. Whitby, Brand UK their SPIN DOCTORS and Sarah Wharry have shown no regard whatsoever for their own shareholders. Tick! Tock!
 Oh what a difference a day makes… Yesterday the lying CEO of Nostra Terra Oil & Gas (LON: NTOG), Matt Lofgran the ex estate agent released an RNS. In yet another attempt to ramp the company share-price in-order to get the NDOG SP to a place that could allow him to pass the begging bowl around yet again. Make no mistake NTOG are desperate for cash and running on vapours. They will place as soon as they can get one away.

 Viva