The ‘Natives’ (Shareholders) of the much maligned ADVFN are getting restless. So restless that they reached out to me last Friday 22/11/2024. That approach resulted in several Telegram group chat’s and a video meeting.
The Tele’ group has over 40 members/shareholders who stated that they’re in contact with other small time holders and have got hold of damning information of malfeasance within ADVFN. Which I took with a pinch of salt.
One groups ‘damning information’ usually ends up being no more than wishful thinking, as in this case claimed exorbitant Director expenses. That’s not going to fly. It was a very interesting weekend, quite funny in many ways not least that they asked me to help, formalise and draft a Requisition, ‘You know the ropes Dan on how to get the job done’. Even offered a ‘fee’ and a position within the company ‘Head of RestructurIng’ LOL!
Their lead man/woman, whose identity and holding I have confirmed via the actual ShareHolder Register they provided, (No mean feat in itself to get hold of) came across as a decent individual. I did give them one tip. Don’t organise on ADVFN chat BBs and for fucks sake never name your source on the ‘inside’. Loose lips sink ships. Fortunately that dies with me. Lesson learnt.
Today’s 5% drop in the SP will no doubt add fuel and more members to the Action Groups cause. But is that ’cause’ a lost cause?
I can vouch that the Group certainly has enough stock to call a Requisition, but that’s far short of ADVFNS’ Executive, family & no doubt ‘friends’ holdings of at least 30%, so it’s an upward struggle, but there are, this is key, other ‘Malcontents’ and just over 28% of stock ‘not in public hands’. So theoretically there’s 6o% ish of votes out there. That would need a huge concerted push of a ‘clandestine nature’ to reach out and pitch your ‘Antidote’ to the current ‘Malaise’ engulfing the company and it’s share price. They certainly have the stomach for it. However traipsing round the City of London, and beyond, pressing the flesh campaigning for votes is time consuming.
I’ll be meeting them in person next week in the City of Mammon…
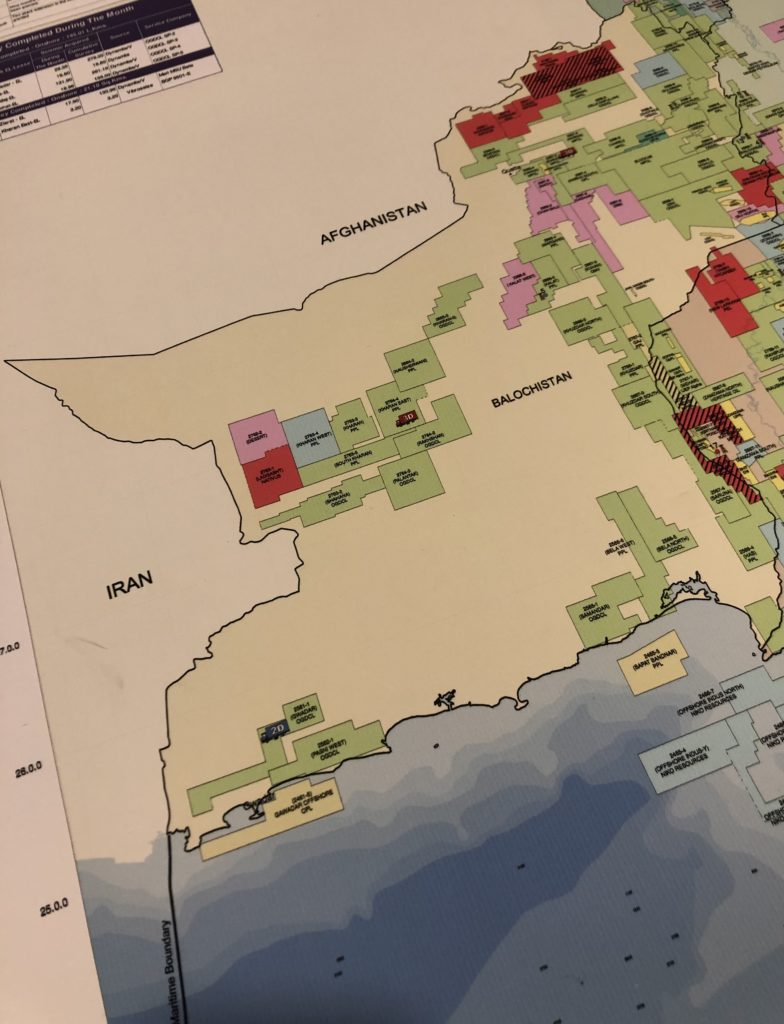
I guarantee 99% of UK O&G traders/investors have never heard of Balochistan. Indeed having just read some of the BB loons I’m changing that to 100%. That is about to change. Balochistāns’ capital is Quetta it is by land mass the largest province situated and the westernmost province of Pakistan, bordered by Iran to the west, Afghanistan on the northwest, Khyber Pakhtunkhwa and the Punjab provinces northeast and east, by Sindh province on the southeast and by the Arabian Sea on the south.
It’s the last great onshore oil, gas and mineral resource play left on the planet. That is a fact. The province POTENTIALLY contains huge Oil, Gas and Mineral Resources. Estimates vary from 6 billion barrels of oil to 75 billion with gas in the hundreds of TCF. It’s the main reason why the Chinese have spent $40 billion constructing the Chinese Pakistan Economic Corridor known as the CPEC, as well as financing and building the port of Gwadar taking a 99 year lease to operate it. Think about that…….. Or better still google the ever shifting sands of Geo Political Alliances currently slugging it out on the world stage, seeking control of the earths resources. Make no mistake Balochistan is now coming into play and that play is huge.
Now lets get down to the UK Privateer Coro Energy pantomime: “O yes they are. O no they’re not in negotiations”, currently doing the rounds on the BBs, Twitter, and Financial Forums. Are we to believe anonymous posters or do we believe sourced articles circulating in Pakistan/Balochistan as well as UK’s Upstream Online?
Occam’s Razor: If it walks like a duck, quacks like a duck, looks like a duck, it’s a duck. There is no doubt that Coro Energy are in negotiations re O&G licences in Balochistan. At what point those negotiations are at isn’t known. What is known is that Coro must have physically been in Balochistan/Pakistan and held high level ministerial meetings as well as meetings with virtually all the main Pakistani O&G companies, if it hadn’t have happened it wouldn’t be reported in over 10 different Pakistan Newspapers/Journals… Just because it’s written in Urdu doesn’t make it any less valid. It’s happening.
The article in Upstream writes that Coro are seeking Joint Ventures one of them is purported to be a 100Million barrel of oil with 850Bcf of gas ‘stranded asset’. If that is even half correct the financial implications of such a tie up would catapult the Coro SP into multiples of multiples. We’re talking literally billions of dollars in production. The kicker is, subject to Due Diligence, a stranded asset has already been discovered. There’s no uncertainty: the hydrocarbons have already been found
I’m thinking out loud here. Going back to the GKP days. Gulf Keystone managed to manoeuvre themselves into Iraq/Kurdistan a region beset by a full scale ‘Shock and Awe’ USA lead war. One of the main movers in GKP was Ewen Ainsworth. We all know the story and the meteoric rise in the SP of GKP. Ainsworth is a board member at Coro Energy. Balochistan doesn’t have the instability of full scale war, what it does have is internal disputes between State and Federal governments on the share of Mineral, Oil & Gas resources, with a very low level local insurgency that’s on its last legs. With the appointment of a new Balochistan Chief Minister who has made it clear that it’s time to develop the provinces mineral/hydrocarbon wealth, Ainsworth is probably worth his weight in gold.
There’s literally 1,000s of oil seeps all over the Baluchistan region. So much so the locals often come across them. This video is well worth a watch.
Current Balochistan Licences
There’s nothing on the AIM, and hasn’t been for several years, that has caught investors imagination, mainly bread and butter plays. Balochistan is totally different it is huge. Whatever the true state of play of these negotiations is, any deal or JV signed has the potential to be earth shattering especially if the oil is already there…
The driving force behind Coro is James Parsons and it is JP who has travelled, literally 100s of 1,000s of miles every year seeking deals trying to bring value back for share-holders. To go where no one else or any company would go is impressive. It takes guts. No CEO should get an easy ride but to search the globe year after year all the while being hounded by disgruntled BB howler monkies can’t be pleasant. The tenacity of JP should be applauded. This, if it comes to pass, is a company maker.
Coro may be on the verge of entering the last great Onshore Oil, Gas & Mineral Resource play on the planet. 10% 25% 30% of any deal OR JV, if struck, would be transformational. To put it into context 1TCF of gas is 166Million BOE. At a $76 a barrel that’s over $10 Billion dollars gross. 25% of that is what? The market cap of Coro is circa $8M.
This SP could motor upwards over the next few months especially if there’s a JV with a stranded asset. Currently trading at a third of a British penny. Short term 3p, 5p 10p isn’t out of the question. If there’s a deal on a multi billion dollar stranded oil/gas discovery we could see 50p on production. Remember GKP? Of course I’m now a shareholder.
As those that follow Guerrilla Investing will know, from my scribblings, in April and May of this year I predicted that a takeover of (LON: ADVFN AFN) was on the cards, being progressed behind the scenes and funded by an Israeli group of mega wealthy corporate elites, lead by the former ADVFN Director, Professor Yair Tauman, who increased his holding from 9.44% to 18.31%. Then enter the arena his ‘bestest’ business buddy, Israeli Mr Ron Izaki who owns and manages the IGI Group: Izaki Group Investments. IGI is one of Israel’s largest and longest-established private real estate development companies. IGI hold 4.31% of ADVFN
Unknown to most at the time was that those behind it had attempted to take control in 2015. That attempt was eventually fought off by the present board.
TAKEOVER
For those that don’t know the history, it went like this. In 2015 an attempted ‘putch’ was launched, the share price went through the roof breaching £1.50p, as the group, posing as Sweet Sky Ltd and Shellhouse Ltd ‘Officially’ declared 25%, which most believed was closer to 40% through the dark arts of undeclared ‘other’ parties holding stock. i.e. An undeclared Concert Party.
FAST FORWARD
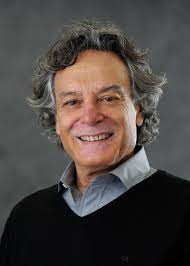
Fast forward today’s TR1 from ADVFN disclosing a further 9.66% holding from yet another Israeli‘Professor’ Dan Horsky. That brings their total declared holdings in ADVFN to 32.28% effectively swinging the Takeover Pendulum in their favour. Make no mistake: That’s ‘a Concert Party’ which has gone over 30%. Market Rules dictate that they have to make an offer for the Company!
In order to wrestle control away from the present board, to avoid a repetition of the costly legal dogfight that thwarted their 2015 ‘kick the doors in’ requisition the Israeli Group maybe ‘Knocking on the door‘ as you read this with an offer. That ‘offer’ will have to be at a substantial premium to the current SP of 73p. Sources indicate that £4ish per share gets them home and dry without the need for a Requisition, that would almost certainly end up in ‘legals’,. How high could the SP go over this week?£2/£3 anything is possible when you know the history….
HISTORY
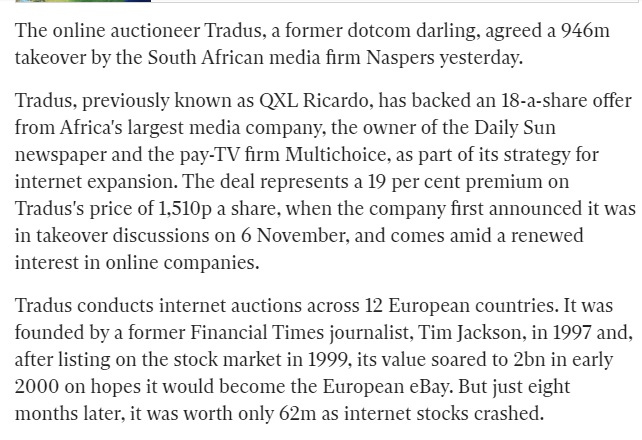
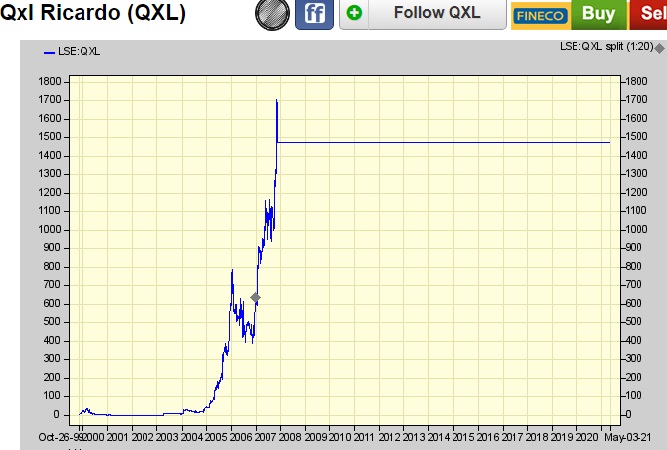
The Israeli’s, as we say, have, ‘Got Form’ having previously taken control of a little known company called QXL, which changed its name to Tradus, which then went on to massive value rises, ultimately QXL/Tradus, was sold for a whopping £946M to Nasper.
Horsky was born and lives in Israel. His worth is in the hundreds of millions of dollars. Collectively the group are probably worth billions Horskys’ career is a colourful one, to say the least, he’s taught and lectured the cream of Swiss banking talent, at among places, the prestigious University of Bern in Switzerland and has over 30 years as a professor of business administration, finance and banking..
If you don’t understand Blockchain, Defi, or Crypto Currency then stop reading, log off. This article is aimed at the global crypto community. Oil & Gas, Bio, Pharmaceutical & Mining Traders/Investors look away now. It’s not for you.
If you have an understanding (Even cursory) of Decentralized Finance and the huge potential the ever growing space is taking up in financial markets then carry on.
Online Blockchain (LON: OBC) are a UK listed company. At time of writing, they have a ‘measley’ market capitalisation (MC) of circa £5.5M. They are massively undervalued and I’ll explain why. Their MC should be at the very least £25M/£30M. OBC are debt free, cash in hand of £1.5M and currently hold circa £3,000,000 of their sister company’s (ADVFN) stock. For those that don’t know, ADVFN is one of the worlds largest financial & crypto data portals. The reason/s they’re flying under the DeFi radar is quite simple. The Board are ‘Camera Shy’ that is to say they don’t openly court attention via highly expensive marketing, possibly due to malicious actors/hackers that are notorious in the sector or fear of the ‘wrath’ from centralised financial institutions. Savvy crypto traders know all about the hackers out there and big corporations trying to keep the lid on DeFi.
Umbria Network
For those reading that don’t know what the Umbria Network is, the simplest description is thus. The Umbria Network is an open source Protocol offering DeFi products and services, one is a ‘crosschain bridge’ known as the ‘Narni Bridge’ that allows the transfer of tokens from one chain to another chain, for example from Ethereum to the Polygon chain. The Umbria Network bridge (named after a famous Italian bridge in Umbria) is the fastest and most price competitive in the market. Where the The Narni Bridge excels is speed and its ‘peppercorn cost‘. Instead of waiting hours for a transaction to be completed the Bridge takes 1 or 2 minutes at most, at a fraction of the cost. When crypto traders provide liquidity to the Narni Bridge they earn, on assets, very attractive APY, Annual Percentage Yields
Kickers
Now here’s one of the many potential ‘kickers’ for the OBC SP. Sources indicate that OBCs Umbria Narni Bridge will soon integrate with Binance smart chain. Binance are one of the global leading crypto exchanges. This is huge and will open up the Narni Bridge to millions of Crytpto traders. The footprint of the Binance smart chain and Binance itself is global. *To note Umbria is one of the many projects Online Blockchain are working on*. At present the Umbria Network has a fully diluted market capital of just over $14,000,000. (The OBC MC is £5.5M) there’s a big disconnect in the market none of the current value of Umbria is reflected in the OBC value and the value of Umbria will almost certainly continue to rise in excess of $50,000,000. What’s also not known in the Crypto community is that OBC are rumoured to be in talks with Coinbase.What those ‘talks’ are isn’t known. But talks they are in…..
The Defi market is currently valued at $80,000,000,000 and is projected to grow by 10 times next year to $800,000,000,000. Business Insider
Online Blockchain are quietly growing, they now have an office in Gibraltar, which is one of the global Crypto/DeFi hubs. They’re fully cashed up, debt free, very few shares in issue, trading well below intrinsic value and operate in a sector that is prone to huge rises. How high could they go? £1,50, £2, £3, £4? Who knows? The recipe for a monumental share price rise is there. It’s already happened once and it’ll happen again. It could easily fly up 300% 400% 200% once the news starts to drop and crypto traders zero in….
Don’t go mad keep it small well worth a couple of hundred quid punt.
In the wake of the ‘rumoured’, Israeli group front man, Ex ADVFN Director, Yair Taumans notification (TR1) that doubled the holding to 18.31%.
Can the present Board of ADVFN: (LON AFN) keep control of the company?
That’s the question doing the rounds in the City of London as you read this.
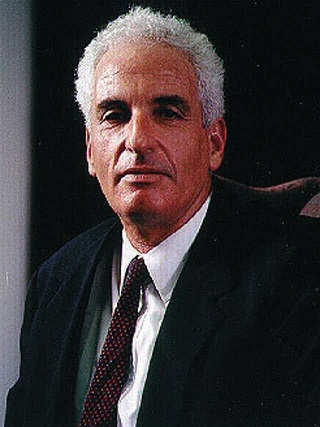
Looking at the QXL history and the ‘contentious’ 2015 attempt at wrestling control of ADVFN, it’s almost certain, there will be further increases in holdings from both combatants in the fight for what the takeover group probably see as a potential lucrative cash cow that’s under-performed. After taking control of QXL , the sp was sub 1p eventually rising to a staggering £17, before the company was bought out for close to £1B, at £14+, in 2007. I’m sure the Board of ADVFN are aware of exactly who’s involved, what they hold, both declared/undeclared and who is supporting them. These are mega wealthy people and know the market inside out; Yair Tauman, is a highly respected, Professor of Economics at State University of New York, Stony Brook and the Director of the Stony Brook Centre for Game Theory.
The conundrum is, will those currently trying to ‘kick in the front door’ cease and desist and knock on the front door? If so how will the present Board react? Rumours current are that there’s a shadowy concert party pulling the strings, through nominee accounts from as far away as USA, Israel, Cyprus, Switzerland and the Bahamas to name but 5 of the many locations I’m hearing.
Those running the Company are duty bound, if approached via a ‘polite knock’ on the front door, to enter into negotiations. ‘Thems’ are the rules corporate and regulatory. If you’re approached then you have a duty as well as a responsibility to sit down and listen to the proposal. It’s as simple as that. Hammer out a deal. In the real world of business everyone is up for a deal. ADVFN and the Professor are no different.
Prof’ Yair Tauman
As it stands, I can’t see these people making the same mistakes as 2015. Both parties are corporate, business, savvy, both know that the other will not blink in a hostile takeover situation. But is that really in the best interests of shareholders?
ADVFN could probably muster 25% to 30% of existing holders to keep control. But that would not be enough. If a requisition drops, which is by it’s very nature ‘Hostile’ then their only way of defeating the Israelis is via ‘legalese‘. As I read it, the interested party can call up or will soon be in a position to call up, over 40% of the votes…
So, the value drivers at the moment are increased holdings TR1s from the Tauman group, as well as Director buys and option, warrant exercises by the incumbent’s. That should or could catapult the SP to between £1/£2. Of course if an RNS drops announcing ADVFN are in official takeover talks or a Requisition is RNS’d and these two are highly likely given the history. Hindsight, with a look at the meteoric QXL rise, then £4+ isn’t out of the question from a current share price of 63p. If I was either of the combatants I’d reach out officially and get in too talks. That’s the key here to it all.
Make no mistake there’s a corporate battle being played out behind the scenes for control and the share price will rollercoaster higher.
Today’s TR1 from ADVFN ex Director Mr. Yair Tauman confirms that the Israeli group that tried to take control of ADVFN in 2015 are back with a vengeance. Yair Tauman has declared an increase in holdings from 9.44% to 18.31%
For those that don’t know the history, it went like this. In 2015 an attempted ‘putch’ was launched, the share price went through the roof, as the group, posing as Sweet Sky Ltd and Shellhouse Ltd ‘Officially’ declared 25%, which most believed was closer to 40% through the dark arts of undeclared ‘other’ parties holding stock.
At one point requistioners were contacting ADVFN private shareholders trying to buy their holdings, requisitions were launched, the FCA became embroiled and eventually the battle for the Company was quelled as the custodians acting for the group; Bank of New York (Nominees) and Bank of New York Mellon decided not to proceed with its requisition for a general meeting, they advised their clients that they had gone about the takeover the wrong way, breaching numerous FCA/SEC regs. Ergo the plug was pulled. Victory, Clem Chambers. The SP at the height of the requisition went over 150p.
What wasn’t known at the time was that this group had previously taken control of a little known company called QXL, which changed its name to Tradus, which then went on to massive value rises, ultimately QXL/Tradus, being sold for a whopping £946M to Nasper. https://www.independent.co.uk/news/business/news/naspers-946m-bid-agreed-by-tradus-765936.html
So the history here looks like a re-run of the 2015 takeover of ADVFN.
You can expect that todays news will be followed by more increases in SP and declared holdings with a requisition for a General Meeting. This could hit £2/£3 over the coming weeks/months as either party look to secure victory..
Just occasionally a company pops up that’s below the radar and My Health Checked (LON: MHC) are certainly not known in the general investor/trader space. They’ve no visibility or traction yet, but that looks set to change with their potential news flow over the coming months.
For those that don’t know the Company or the sector, I’ll lay out a brief outline.
Outline
The Bio/Pharms (Covid) sector is prone to huge rises/volatility, particularly since the onset of the Covid19 virus and ensuing pandemic, Vaccines, PPE, Testing & all things Covid critical can make the ‘canny’ huge returns. In March 2020 Omega Diagnostics (LON: ODX) was trading at 8p. It went over £1. Currently at 80p. Genedrive (LON: GDR) was 10p in March 2020 it hit £2.20p in May currently sits at £1.40p, same same Avacta (LON: AVCT) 15p hit £2.10p now sitting at £1.45p. There are plenty of other Covid mega rise story’s out there.
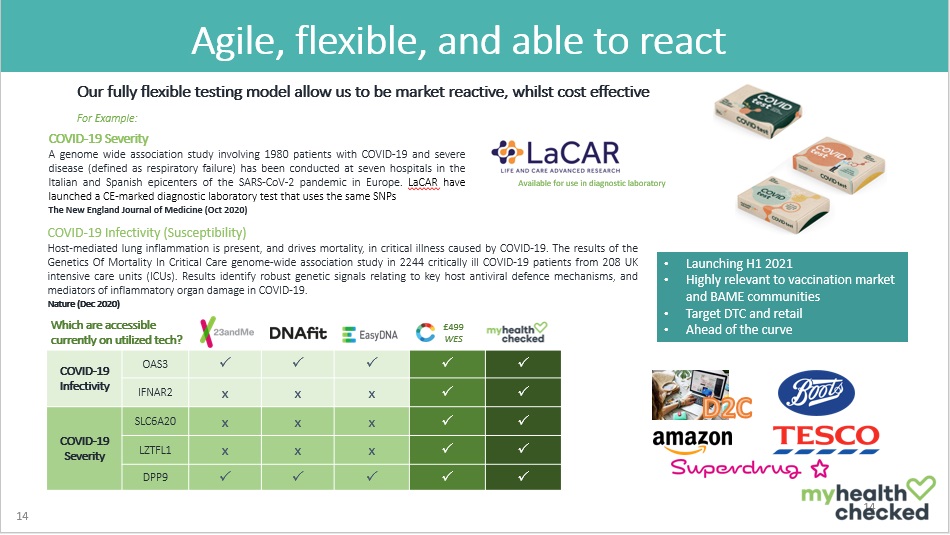
Concepta changed their name to My Health Checked. MHC are packed with experience in the home health care testing space, their product pipelines include, fertility, immune function, food intolerance & DNA testing to name but four. They know their sector and they are now in the Covid space, MHC are not a one trick pony and this Company will gain traction over the next 3 months or so. They maybe late to the party but they are here now….
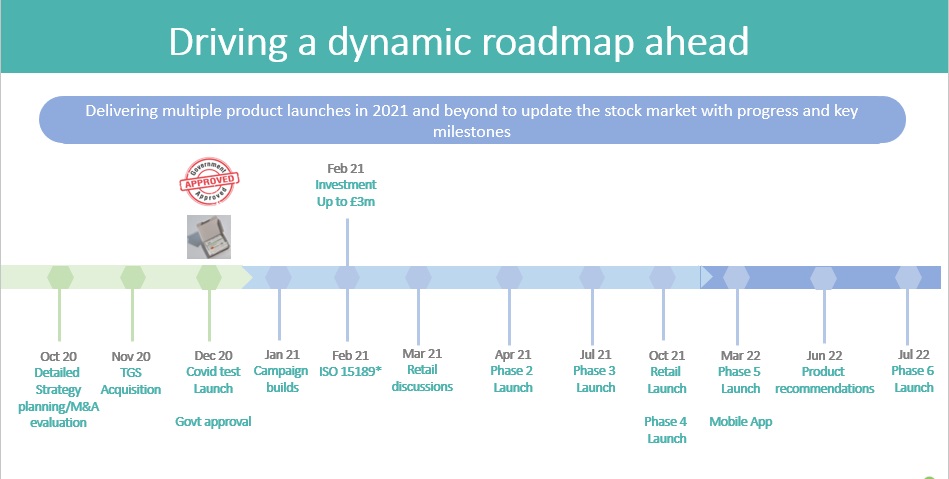
There’s been a board room clear out with a move into Covid testing, I tipped Concepta on my blog (pre their recent rise, raise & name change) at 0.9p after I discovered that the new management were entering the Covid19 testing space. Their Laboratory/s are based in the Manchester science park. The recent placing at 1.75p has been heavily backed by Venture Capital/Enterprise Investment Scheme, bods, these for tax reasons are ‘sticky’ investments which is why the bookbuild was closed within 10 hours of its announcement. The appetite with hindsight suggests that the raise should have been done at 2p+. There are very few retail punters in MHC. It’s a ‘tight ship’. The approval for the Placing & Firm Subscription Shares should come at the AGM ON 18th, admission to trading on AIM at 8.00 a.m. on or around 19 February 2021. That’s the date that MHC will start to slowly come into focus.
My Health Checked are now a Government approved provider of Test to Release and private COVID tests. Spring is approaching, the test to fly scheme will be on full steam here before we know it. The run up to that will see plenty of coverage in the National news as well as updates from the Company. If they, as a Government approved provider, land a Government or Corporate contract/s the SP will go mental. It’s rumoured that they are in discussions with several big retail/corporate outfits. They are fully funded, £3.4M raised, Directors took part, more to the point they are now operational in the Covid testing sphere. Now here is one of the many kickers, MHC COVID tests identify all presently known Covid mutations. The company’s rapid Covid testing service is value beating, it’s price competitive and is being rolled out. Which is why it has been added to the UK Government’s approved COVID-19 private testing providers list for General Test and the Test to Release for the recently introduced International Travel scheme. You cannot fly or return unless you are tested as ‘Covid negative’. As it stands now you cannot fly without such a test
Moon Shot
They’re sat at 2.2p as of writing. I can’t see them going down I can only see them rising. Anything under 5p in my opinion is a good price. They could hit 10p in the blink of an eye. 20p isn’t impossible, with a Government or Corporate contract a UK based Covid stock will become a ‘moon shot’, 25p, 50p, 100p, 30p, it’s that kind of space re the pandemic. They are not going down they are going up incrementally or exponentially.
The only thing that’s holding them back is piss poor PR/IR: take a bow Wallbrook and (There’s been no coverage) ratification of the recently heavily oversubscribed capital raise. MHC are below the radar. That will change.
As ever ‘don’t throw caution to the wind’. Get researching, get up to speed before you decide Yea or Nay. If you do take a punt, keep it small. Don’t throw in the kitchen sink. Greed is your enemy.
Commenting on stocks and shares can at times feel like a character from a Hans Christian Andersen tale, one in particular, “The Emperor’s New Clothes” springs to mind every time I read or see the utter shite constantly pumped on social media by various shysters on both sides of the fence, corporate and retail.
It doesn’t take a genius to see the metaphors from fairy tales played out on City of London listed companies by traders and corporates alike who rely on ‘greed’ to blind ‘common sense’. The target being lumpen-proletariat small time mug-investors or as I call them ‘the meat in the liquidity sandwich’. The goal is to push the ‘tall tale’ using various ‘ruses/ploys’; such as ‘behind the scenes briefings’ to certain well known P&D merchants who take a position as well as small fees with ‘warrant packages’ then go out heralding the news of riches beyond your wildest dreams….
Which brings me on nicely to Nu-Oil & Gas (AIM: NUOG) the current nudge, nudge, wink, wink is in full flow not least on the BBs and twitter sphere. NUOG are a shell they have absolutely no value whatsoever other than there listing value. The old Board of Directors are being paid out, then kicked out, with a new team set to come in post GM ratification. The ‘new deal’ is deliberately structured in such a way that a select group of Novum placees (no more than 4/5 individual connected investors) are taking 1,000,000,000 shares of stock at a 50% discount to today’s SP, while a newly formed corporate entity holds £2,500,000 of loan notes (again at a 50% discount) to flip out as and when you ‘the meat in the liquidity sandwich’ are buttered up into believing in ‘Fairy Tales’. Mugs buying in at 0.075p are paying a 50% premium to that placing and loan note package. £3,000,000 will be flipped out into the orchestrated rise. A rise that will be predicated on a ‘hope value’.
If by now you haven’t worked out the implications then let me spell it out. You’re starting a race with a handicap. You can never beat the corporate flippers because they have a 50% head start with access to the news flow. If today you were 20% down on your stake bought at 0.075p they would still be 30% up. It’s a race you can never win.
‘Weaver’ Fumagalli?
The company holding the £2,500,000 loan notes are C4 Energy Ltd. That paper company is the brain child of one Marco Fumagalli (Continental Investment Partners, Sound Energy, Coro, Echo) and Mr James Parsons (JP) (Sound Energy, Echo energy and Coro). Both are connected at the hip as is Mr Andy Dennan proposed director NUOG, (current CFO & Director CORO, Sound Energy Holdings Italy Ltd, Alpha Growth Plc, Baron Lux LLP). I know them all, have met them, broke bread with them and talked all things O&G with them. They’re decent people in their own way. But as corporates go I wouldn’t trust them with a ‘birds nest’. They are ‘corporate bastards’. NU-OIL, at this stage of its evolution, isn’t about finding oil or gas in Cuba, Mexico or some far field of a foreign land that’s forever England, it’s about corporates playing the system using a tried and tested method to make money regardless of finding oil or not.
….. ‘Weaver’ JP? …..
All of the above have made substantial sums of varying degrees, of a reputed £200,000,000 million generated from the Sound, Echo and CORO ventures. The largest slice of the pie going to the moneyman who finances the companies: Fumagali/Continental and their various offshore exotic mechanisms.
The ownership of C4 Energy wasn’t disclosed in the RNS of 2nd October 2019. That omission was deliberate. It was a calculated ploy to set the NUOG shareprice to spike in an attempt to replicate the fantastic gains of the early days of Echo Energy. Pump and Dumpers were briefed to scream it from the rafters. It ultimately failed.
Sadly all three companies Sound, Echo and Coro ‘ultimately’ bombed. Now that isn’t a critique of any wrong doing. Far from it. In the real world the best any investor can ask for is a company does what it says on the tin: i.e. They get their licence, and drill it. All 3 companies have done exactly what they said they would do. They have ran and continue to run within the rules and regulations. On the whole their biggest failure has been geological and it’s geology that determines financial success or failure for shareholders. However it’s not the geology that determines success or failure for corporates it’s selling heavily discounted stock into ascending share prices.
The whispered Cuban licences for NUOG are a fantasy. One only needs to do what Liargas did with his ‘Fairy Tale’ and speak to the British Ambassador to Cuba who explained that O&G exploration in Cuba was 15-20 years away due to the Geo-political situation vis-a-vis the USA. Exit stage left Liargas from Cuban oil into cannabis.
Based upon historical performance of those now taking control of NUOG if it runs true to form then it’s nothing more than a corporate carve-up pre change of control…….
So, the questions are many. Too many for this blog. But questions will be put to those running the show and answers sought next week. Such as: Since when did an Oil & Gas CEO (JP) decide that issuing vulture finance packages and organising a select placing at ‘mates rates’ to mates, become more productive than finding oil and gas?
Viva
Dan
N.B: Kejserens nye klæder) is a short tale written by Danish author Hans Christian Andersen, about two weavers who promise an emperor a new suit of clothes that they say is invisible to those who are unfit for their positions, stupid, or incompetent – while in reality, they make no clothes at all, making everyone believe the clothes are invisible to them. When the emperor parades before his subjects in his new “clothes”, no one dares to say that they do not see any suit of clothes on him for fear that they will be seen as stupid. Finally a child cries out, “But he isn’t wearing anything at all!” The tale has been translated into over 100 languages.
 oday’s 5% drop in the SP will no doubt add fuel and more members to the Action Groups cause. But is that ’cause’ a lost cause?
 ADVFNS’ Executive, family & no doubt ‘friends’ holdings of at least 30%, so it’s an upward struggle, but there are, this is key, other ‘Malcontents’ and just over 28% of stock ‘not in public hands’. So theoretically there’s 6o% ish of votes out there. That would need a huge concerted push of a ‘clandestine nature’ to reach out and pitch your ‘Antidote’ to the current ‘Malaise’ engulfing the company and it’s share price. They certainly have the stomach for it. However traipsing round the City of London, and beyond, pressing the flesh campaigning for votes is time consuming.