Jeyll & Hyde to UK list 260117Jeyll & Hyde to UK list 260117
|
Jeyll & Hyde to UK list 260117Jeyll & Hyde to UK list 260117
|
Today’s the launch of
Jekyll & Hyde.
 Yes it’s a paid Newsletter or as COMMONLY KNOWN A Tip Sheet…. What makes it different? This is what ADVFN say; “In this newsletter two well-known market players go head to head in what will be one hell of an investment/trading battle throughout 2017 as they write you their tips in a bi-monthly edition each using his own financial strategy to make money. Get both sides of the action at once with investment ideas from ADVFN’s own Clem Chambers as Dr Jekyll and investment Wildman Brokerman Dan (Daniel Levi) as Mr Hyde” You can sign up HERE
Well I actually say this. What makes Jekyll & Hyde truly unique and different is the dynamics, the dichotomy of the two individuals. Dr Jekyll (Clem) is the archetypical establishment man. He’s the chairman of the Conservative Carlton Cricket Club a wealthy individual from a some what privileged background, the CEO of the worlds biggest financial website, ADVFN, a dyed in the wool business dragon and acclaimed author who in his spare time collects Castles. He lives in one and owns three. A famous globally known Treasure Hunter. A connoisseur of fine art and an artist to boot… Jekyll is a member of the famous ‘around the world in eighty days’ Reform Club, while I was a member of a ‘Reform School’! He’s a value investor investing in accretive dividend paying under-valued main market stocks.
Jekyll and Hyde are two human beings thrown together by Karma, from completely different ends of society. About as far apart on the social spectrum as it is possible to get. Mr Hyde (Me) collects cigarette cards, Chinese snuff bottles & worthless tat! Brought up on the mean streets of the Manchester slums, most notably the notorious, riot torn Moss Side. The prodigy of social depravation and criminality. Jekyll in his business life has risen to the top, while I, forever to my shame, rose to the top of my ‘Profession’ which is well documented. Yes I was involved in crime and was on the radar of every police force in the United Kingdom, including Special Branch and Interpol. Such were the bad choices I made three decades ago. I learned, I educated myself, I am ‘reformed’ I am not a criminal. ‘Honestly Guv’. I paid in spades for my mistakes and paid a high price, nearly two decades behind bars. I deserved every day of it. My debt to society is paid in full. If you don’t like it then do not sign up for J&H.
There are many ‘Tip Sheets’ out there masquerading as shareholder friendly, most receive some form of remuneration from the companies they tip. They are ‘Tip Shits’.
Jekyll & Hyde isn’t there to make or take money from companies. It’s there to give informed opinion and reason as well as a walk on the wild side for share-holders and investors/traders alike. To buy or not to buy, to risk or not risk, to go for dividends or astronomical SP rises. There’s no format out there like it. It’s a head to head. Establishment V Anti-Establishment.
Viva
Hyde.


FinnAust Mining (LON: FAM) is a dual AIM and Frankfurt Stock Exchange listed resources exploration company which currently has a number of prospective licences in Greenland, Austria and Finland. The company came to the London market in December 2013 following the £7.7 million reverse takeover of Centurion Resources. This brought with it a major shareholder in the form of ASX-listed nickel producer Western Areas, who we will discuss in more detail later, and which put up £1.8 million into the £3.4 million IPO placing at a price of 5p per share.
Having an initial focus on a range of early stage copper assets, shares in FinnAust fell steadily over the two years following its IPO as a result of a 35% fall in the price of the metal. However, a move into titanium in December 2015, driven by new Managing Director Rod McIllree, caught the market’s attention and breathed a new lease of life into the shares, which are amongst the best performing on the whole of AIM in the year to date.
FinnAust’s current assets are as follows:
Finland – owns 100% of a portfolio of copper, zinc and nickel projects; the Hammaslahti CopperGold-Zinc Project, the Outokumpu Copper Project and the Kelkka Nickel Project. In January this year additional licences were granted over the project areas, increasing the land area by c.50%. While these are not the current area of focus FinnAust still sees value in the assets.
Austria – an 80% interest in the previously producing Mitterberg Copper Project in Salzburg. This is largely a legacy asset from the reverse takeover of Centurion Resources and FinnAust is currently looking at realising its value.
Greenland – the current focus of the company’s activities is the Pituffik Titanium Project in Greenland. FinnAust has an interest in the asset via its 60.37% stake in Bluejay Mining Limited, the 100% owner of the project, which was acquired in March this year.
The Greenland assets were added to in September this year when FinnAust agreed to acquire 100% of Avannaa Exploration from Capricorn Oil, a subsidiary of Cairn Energy, for £500,000 in new FinnAust shares. The two most noteworthy projects are the Disko-Nuussuaq nickel-copper-platinum project and the Kangerluarsuk SedEx lead-zinc-silver project. Located in the south-west of the country the assets had over $50 million spent on them prior to being bought by Cairn and are believed to have high-tonnage and high-grade base metal potential. The deal is conditional upon approval from the Greenland government and expected to be completed within the next few weeks.
Pituffik
Touted as a potentially world class asset, the Pituffik Titanium Project is located on the Steensby
Land peninsular in the north-west of Greenland, 83km south of the regional settlement Qaanaaq (pop. 656) and part of the Thule black sand province. Here, the coastline contains areas of high concentrations of the mineral ilmenite (the most commercially important source of titanium), on active and uplifted beach zones, which are the focus of Bluejay Mining. Bluejay holds exploration licences over 150km² of onshore ground and shallow marine environments at the project.
The acquisition price (for 60.37% of Bluejay remember) was a maximum of £905,607, paid for via the issue of 164,655,885 new shares in FinnAust at a price of 0.55p per share. Of these, 40,755,885 shares are deferred (see more below) and there is a four year option to acquire the remaining 39.63% stake (another point discussed in more detail later). The Bluejay vendors include, interestingly, FinnAust’s Managing Director Rod McIllree and Non-Executive Greg Kuenzel (of Noricum Gold fame). Along with the acquisition, a placing of 10 million new shares at a price of 2p each raised just £200,000 with major shareholder Western Areas putting in half of this.
As you can infer from the picture below, Pituffik is not somewhere you would want to go for your summer holidays, being located in the Arctic Circle and experiencing harsh climatic conditions. Despite the cold, Greenland has actually been warming up, with climatic changes causing its ice sheet to retreat and exposing new areas for minerals exploration 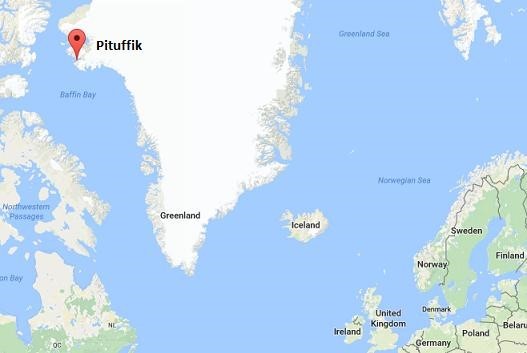 and exploitation.
While originally being discovered in 1915 Pituffik remains an early stage exploration asset.
It caught FinnAust’s attention due to having high grade material and exploitation potential. Historic fieldwork by Bluejay, the Geological Survey of Greenland & Denmark and others has highlighted the presence of a very large and, according to the company, “unusually pure” titanium deposit at Pituffik. Active beaches in the region have demonstrated grades of up to 68% ilmenite, averaging between 38-40%, with the more expansive uplifted beaches averaging around 17%. Upon acquisition FinnAust’s CEO McIIlree gushed that Pituffik has the potential to “become one of the highest grade in situ deposit of ilmenite anywhere in the world.”

There are two key areas which have been identified for further work at the project, Moriusaq and Interlak, located along an 80km coastline in environments including raised beaches, active beaches and drowned (underwater) beaches. Moriusaq is the most advanced area and has returned the highest ilmenite grades to date, with grades in some areas estimated to be in excess of 85% ilmenite. Interlak offers the largest volume of heavy mineral sands, with grade upside potential, with grades in some areas estimated to be in excess of 70% ilmenite. The plan is to advance Moriusaq first given that its marine environment could provide an opportunity to employ dredging (a simple and low cost method) to exploit the sands.
Latest developments
Following the initial agreement to buy the stake in Bluejay in December 2015 FinnAust quickly got its plans together for developing the asset, with the strategy being to capitalise on Pituffik’s near term production potential. In February, results from a bathymetry (underwater) and seismic profiling survey completed in 2015, along with a sea floor sampling programme, suggested that the shallow marine environment hosts very large volumes of potentially high grade titanium, with the results multiplying the amount of known titanium mineralisation significantly.
Subsequently, various technical consultants were hired in order to complete fieldwork over the course of 2016, including an initial resource calculation for the Moriusaq target and surrounds. With the nights (and days) getting colder, the work programme was finished in September, with more than 500 drill holes having been completed along with trenching and sampling across the project area. Results confirmed that the two target areas will remain the key focus. An Environmental Impact Assessment has been completed and a Social Impact Assessment is underway.
FinnAust is now in a position where it expects to publish a JORC compliant resource by the end of 2016, ahead of commencing an initial 30,000 tonne proof-of-concept bulk sampling programme in 2017, followed by the application for an exploitation licence in Q1 2017.
So far so good but valuation is materially out of kilter with the progression stage
To give FinnAust management credit the company has, over the past ten months or so, provided a text book example of how to promote s story, and they have done so with a relatively limited freefloat. A plethora of technically worded RNS’s with copious amounts of “pleasing” and “exciteds” peppered throughout these releases in relation to the Pituffik asset has pushed the stock price up nearly 15 fold since the beginning of the year. The shares have risen from 0.55p just prior to the Bluejay acquisition announcement to the current 7.5p, making FinnAust one of the best performing shares on the whole of the London markets in the year to date.
All well and good but we have a number of issues and questions.
Difficulties mining in Greenland
As a jurisdiction, Greenland has its attractions and is regularly ranked as one of the most attractive places for mining investment by various industry surveys, accepted. The government is becoming ever more mining friendly as it looks to take advantage of the island’s rich resources and, in contrast to the locations of many AIM listed junior miners, the country is politically stable. As mentioned above, climate change is causing ice sheets to retreat, creating the opportunity to study new potential resources.
But there are many challenges related to operating a mine in Greenland, mainly due to the harsh climatic conditions and remote location.
At Pituffik itself the average daily temperature in July barely reaches 8°C, with the winter months typically seeing temperatures of around -20°C. This creates a situation where certain activities can only be carried out at certain times of the year and makes for a more expensive operating environment. With pack ice forming in the early autumn the window for making shipments from Pituffik could be as low as five months.
Infrastructure in the country as a whole is limited, with there being no major road networks and most domestic transportation being conducted by air – Pituffik is located c.30km from the international airport and deep-water port of Thule Air Base which is operated by the US Air Force to the south-east and Qaanaaq domestic airport to the north.
Issue over deferred consideration and options shares
As part of the Bluejay Mining acquisition it was agreed that 40,755,885 deferred shares be paid to the vendors upon the grant of a mineral exploration permit over the offshore Pituffik project area. This was subsequently granted in July this year and satisfied one of two terms for the issuance of the deferred shares.
However, the second term requires that the issuance does not trigger a mandatory offer for the company by the Bluejay vendors under Rule 9 of the Takeover Code – ie. if their stake goes over 30% they will have to bid for the whole company. This situation would have occurred had the shares been issued given the Bluejay vendors’ current holding in FinnAust, so the company is waiting until any Rule 9 obligation ceases to exist before the deferred shares are issued. This can only come if the vendors sell some of their holding or, in the more likely case, their combined stake is diluted by further share issues.
There is also a four year option to acquire the remaining 39.63% of Bluejay for £594,393, to be satisfied by the issue of 108,071,388 new FinnAust shares to the Bluejay vendors. Again the situation is similar here in that the option will not be exercised if it were to trigger a mandatory offer or would trigger a reverse takeover under AIM rules. We note the RNS of 4th October in which Rod McIllree makes the statement “The Company now intends to review the mechanics of moving to 100% ownership of BlueJAy Mining Ltd (and hence Pituffik)…” and believe that this will be the “tell” that in fact unseats the stock price. The easiest avenue is simply to place the stake due to Blue Jay with a third party. As we point out below however, with a market cap approaching £50m without a JORC estimate at this point and no clear path to infrastructure build out, our bear case hinges almost entirely on this point – that is we doubt that a third party will pay anywhere near the current market cap in cold hard cash (the acid test for the industry’s perception of true value) for Blue Jay’s shares that are due from Finnaust and would thus absolve the takeover trigger. Of course they could apply for a “whitewash” if no third party steps up but all this does (assuming it was granted) is push out the date required for a liquidity event for the stockholders whilst not addressing the continuing cash needs of the company.
As we illustrate below in addressing our valuation concerns we suspect that any deal to place FAM shares for Blue Jay (if this route is taken) will be at a material discount to the current stock price if done in cash and still so if part of a strategic investor swap (which is what Western Areas is of course supposed to be…).
Director backgrounds
We note that certain Finniest directors have, shall we say “interesting” histories. Rod McIllree was the founder of ASX listed uranium explorer Greenland Minerals and Energy and its Managing Director up until August 2014. Australian newspaper The Sydney Morning Herald reported on several issues with the company including questions over its ownership structure (see here http://www.smh.com.au/business/unravelling–the–greenland–minerals–web–20091008–gp0w.html) and the rapid dilution of shareholders via the issuance and exercise of options. In addition, it would appear that McIllree and fellow director Simon Cato sold stock into the market immediately after exercising options – see here http://www.smh.com.au/business/a–cold–front–for–greenland
minerals–ceo–20110523–1f0px.html and note in particular:
“In mid-April (2011) those two (Cato and McIllree), and Why brow, each received 4.4 million newly vested options. Earlier this month (May 2011), Cato and McIllree both announced that they had exercised some of their options, 1.55 million and 250,000 respectively, but their filings suggested that they must have sold them immediately because their total shareholdings remained unchanged.”
The share price performance of Greenland Minerals has been “erratic” to be polite– see chart below. But What Greenland Minerals has in common with FAM is that there was a concerted news blitz that increased the stock price materially before the company was laid low in large part due to the debt that was taken on. The problem with a heavily promoted bull story is that at some point the major stakeholders have to get out and if there is  not a liquidity event to provide this gravity always kicks in.
We also point out that Greg Kuenzel, Non-Exec at Finniest, has a history of value destruction at AIM listed Noricum Gold where he is Managing Director. Since the company listed in December 2010 the shares have fallen from the IPO price of 4p to the current 0.12p after failing to prove a JORC resource at various projects.
We also add that we have posed a number of questions to Rod McIllree in relation to these points to which he has deigned to reply.
A mine of information from the 2016 results
While there was nothing really new in the company’s 2016 results regarding progress on the ground the P&L and balance sheet provided a wealth of information. It was revealed that cash as at 30th June stood at just £425,046, although this figure was boosted post period end by a £500,000 (preexpenses) placing. With monthly administrative costs being c.£52,500, and assuming placing fees of c.£25,000 we estimate that the current cash balance amounts to around £0.75 million. With this amounting to just over 1 year’s worth of admin costs there is clearly a placing ahead, we suspect in the first half of next year at the latest.
Non-participation of major shareholder in last 2 placings
Back to the placings… Finnaust has raised a total of £1.5 million since announcing the Bluejay acquisition – £1 million on 4th March at 2p per share and £0.5 million on 13th July at 5p per share. Our question is why has Western Areas, trumpeted as a cornerstone investor, not taken part in these placings? And why did it only put £100,000 into the original acquisition placing? While Takeover Code rules prevent Western Areas as a major shareholder (37.14%) from increasing its interest, we believe it could have at least maintained its holding noting that the Bluejay acquisition document states:
Following completion of the Placing and the Bluejay Acquisition, neither Western Areas nor the Bluejay Vendors will be able to increase their interests in the voting rights of the Company through or between a Rule 9 threshold without Panel consent.
Valuation
The main question here boils down to the valuation.
At the current share price of 7.5p the markets are valuing FinnAust equity at a shade over £37m million. But if we calculate the valuation using the fully diluted number of shares in issue (see table below) then we arrive at a figure of £49.6 million
| Current shares in issue | 494,400,804 |
| Options & warrants | 19,309,366 |
| Bluejay deferred consideration | 40,755,885 |
| Bluejay option | 108,071,388 |
| TOTAL | 662,537,443 |
While we do not deny that FinnAust’s assets have potential we firmly believe that a figure of approx £50 million is simply far too high given the company’s current stage of development.
Even a research note written by the company’s own broker, Optiva Securities, back in February admitted that valuing the company was “challenging” largely given the early stage nature of the operations. We quote:
“Given the early stage of the Pituffik project, limited exploration data and the fact that the deposit does not yet support a JORC-compliant mineral resource estimate, it is challenging to estimate a value for the project in its current stage, in our view.”
Here’s why we think the valuation is overheated.
We believe Finnaust has been a text book example in how to release news to the market in relation to a potentially positive mining opportunity whilst simultaneously keeping the free float tight. A classic squeeze if you wish.
But, once sell orders start coming through, which we suspect they may do as private investors look to take profits or, more likely, any strategic investor puts a very different valuation on the company’s assets given their current stage, the tumble downward could be rapid. While the deal in Greenland with Capricorn/Cairn is not yet complete when it is, we suspect there will be another £500,000 worth of shares in the market looking to be sold – we doubt Cairn will be looking to hold on to the stock given they wanted to be out of the assets at such a low price and they are after all much more financially resourced than FAM to develop them if they so wished.
The fact is that, while many have made large paper profits on FinnAust, liquidity remains low and a value event is needed for those gains to be realised. If the company itself needs an exit, if it is overvalued the industry simply will not pay up.
Viva
Dan
It’s a sad day today as I expose a man I personally had faith in as one of the ‘Good Guys’ who like many before him has now been pulled over to the Darkside of AIM. Matt Lofgran has been involved in what is little better than a Faustian Pact, helping to facilitate shorting his own company for personal financial gain while at the same time promoting it as a good investment to his shareholders and potential shareholders. That is a disgrace and his position is now untenable. He has to go.
Regardless of how he will try to spin it he has while facilitating shorts with Yorkville/YA Global made huge financial gains. Documents now in my possession and independently verified as genuine which have been cross referenced with historical company and FCA information show unequivocally that shareholders were being shafted by Lofgran. The facts are set out below.
On the 29-Jun-2012 Lofgrans’ warrant exercise of 217,842,506 shares at 0.10p of a penny was funded by a loan from Yorkville. The value of that loan was £217,843. The value of the stock on that day was £1,198,134. On the 23-October-2012 Lofrgran loaned to Yorkville (Notorious and well known stock shorters) 155,000,000 shares. The transfer of that stock was made at a circa 17% discount to market value on the day, shareprice 0.324, value £502,750. The actual market price on 23/October/2012 was, shareprice 0.39 value £604,500. In the RNS of the 23rd October 2012, we are told this; “The Loan Shares will be redelivered by Yorkville to Mr Lofgran at the end of the Lending Agreement arrangement”. That infers that the full 155,000,000 shares will be returned. Not so! This was a lie.
In the RNS of 7th October 2013 we are told this; “On 4 October 2013 Matt Lofgran, Chief Executive Officer, received from YA Global Master SPV Ltd 83,956,296 ordinary shares of 0.1p each in the Company. On 23 October Mr Lofgran loaned 155,000,000 Ordinary Shares to YA Global (“Loaned Shares”). Following the full repayment of the secured loan note between YA Global and Mr Lofgran, YA Global no longer has a fixed charge over any shares in the Company and no longer holds any Loaned Shares.” Lofgran never paid any money to Yorkville regarding the loan, as the above implies, Yorkville sold 83,956,296 shares to recoup the loan value and interest. Not one single penny came from Lofgran to fund the warrant exercise. It was a sleight of hand.
At the time of the above transactions Yorkville were actively using the Loaned Shares to short Nostra Terra Oil & Gas (LON: NTOG) as evidenced on the FCA website HERE They held 4 shorting positions. For a CEO of a London Listed Company to get into bed, for personal financial gain, with a fund that uses the CEO’s stock to destroy share-holder value is an act of betrayal.
Yorkville (after shorting the stock) returned a portion of the Loan Shares to ML (Settlement Shares). The portion of shares not returned but instead kept by Yorkville were then sold by them to recover the cost of funds loaned, plus interest charged at 24%.(Annualised at 19% per annum). For the avoidance of doubt: Yorkville charged 24% interest, made a gain on the stock which they shorted and recovered loaned funds in full. The shorting was value destructive to the shareholders and arose on the back of a personal loan made by Yorkville to ML. When you take the shorter’s shilling you sing the shorter’s tune.
And it get’s even worst. The value of the Loaned Shares were underwritten by a director’s loan of £503,000 from Nostra Terra so Lofgrans exposure was nil. From a cash and accounting perspective in the books of NTOG it is unclear how the settlement of funds was recorded, being either: – a cash paid settlement made to ML from a subsidiary of the Company (perhaps Horizon?); or more likely… – a non-cash settlement which would have given rise to an undisclosed gain of GBP 180k in the books, thereby understating the losses by more than 10%. It needs to be noted that Nostra then went on to issue yet more shares, 123,000,000 shares, to Yorkville via the re-jigged SEDAR. Value of those shares? £503,000
During the period of the transactions with Yorkville from the 29-Jun-2012 to 7 October 2013 the Oil price (WTI) ranged from $85.04 to $103. Yet the value of NTOG dropped by as much as 29%. That was a direct consequence of the Yorkville shorts. Despite the disingenuous and duplicitous cheer-leading and promoting. Shorting which Lofgran must have known about and was PARTY TO IT. It was value destructive for NTOG share-holders. The actual value erosion over the 15 month period was circa 53%. Lofgran sought to self enrich himself at the time of the warrant exercise to the tune of £980,291.
For the CEO of any company to enter, knowingly or unwittingly, into what can only be described as a shocking betrayal of his shareholders is testament to why Nostra Terra are where they are today, in the toilet.
Matt lofgran’s position is now as already stated in this article ‘untenable’ he has to resign. He can go quietly or kicking and screaming into the night protesting his innocence. For a CEO to become embroiled for personal financial gain with a fund that uses his shares to short his company while destroying value for his Shareholders is an act of betrayal that cannot be rectified other than by a resignation.
 Viva!
Dan
N.B Sources and References below.
Source / reference Stock shorting open “Short positions spreadsheet” link in the following:
https://www.the-fca.org.uk/markets/short-selling/restrictions-prohibitions
http://www.investegate.co.uk/nostra-terra-o-g-co/rns/exercise-of-directors-warrants-and-associated-loan/201206291252515096G/
Transfer of Loan Shares http://www.investegate.co.uk/nostra-terra-o-g-co/rns/operational-update/201210231130083219P/
Transfer of Settlement Shares http://www.investegate.co.uk/nostra-terra-o-g-co/rns/increase-in-director-shareholding/201310070700078438P/
2012 annual accounts http://www.ntog.co.uk/media/pdf/ar_2012.pdf
2013 annual accounts http://www.ntog.co.uk/media/pdf/ar_2013.pdf
 As most investors know I’m in a concert party that owns just over 3% of Antrim Energy (LON: AEY). We invested in AEY due to their strong balance sheet. Antrim have approx. $12 million dollars in cash and cash equivalents on their book. No debt and asset/licence interests in Ireland and the UK Offshore. There’s the Frontier Exploration Licence (“FEL”) 1/13. The Fyne Licence, P077 Block 21/28a and Erne Licence P1875 Block 21/29d. All three are 100% owned by the company. Within one of those licence areas there’s a highly prospective resource of 1.1 Billion barrels of oil. known as the Skellig Block, in the Porcupine Basin.
“The Company has identified two highly prospective Jurassic fault blocks and one Cretaceous submarine fan system in the FEL 1/13 Licence, as well as numerous other leads. FEL 1/13 has a 15 year term, with an initial three-year term followed by three four-year terms. The initial three-year term expires in early July 2016 and Antrim has submitted a request to extend the first exploration term by an additional two years and this request requires the approval of the Irish authorities. The Company is also currently seeking a new farm-in partner and operator to complete any additional technical work necessary during the period of any extension granted by the Irish authorities with the ultimate goal that a well commitment could be made at the end of the revised first exploration phase.”
Over recent months we have been in contact with the management and stakeholders. Notably Hedgehog Capital who it must be said have failed to add any thing constructive.
Now here’s the way forward for Antrim. As I see it there are three ways for the company to go. 1/ Get moving on progressing FEL 1/13. 2/. Resign and let new blood take over (You’ll remember that Sound Energy recently made a Takeover approach. I’m sure they would come back. 3/ (In my opinion the best way forward) Dissolve the company and return all cash and cash from asset/s sales back to their shareholders. This could return 4p-6p to their long suffering shareholders. I must point out that we have made our position very clear to the company.
So it’s over to 3 salaries Anthony Potter the Antrim Energy President, Chief Executive Officer and
Chief Financial Officer. Get the Antrim Energy House in order otherwise it’s a potential EGM situation looming large Mr Potter.
Viva!
Dan
 I can’t believe that some people are jabbering on about how great Wishbone Gold ((LON: WSBN) are! I totally disagree with the HotStockRockets team, (whoever they are). The company are all but running on fumes! It’s a ‘Hans Christian Andersen’ moment. The Emperor has no clothes. The last set of interims state that they had, as of June 30 2015, circa £108k in cash and cash equivalents. A perusal of the last known balance sheet exposes the preposterous ramping that’s going on. Wishbone are a precious metals trading business and a company that need cash and need it quickly.
The company’s’ run by a chap called Richard Poulden, who operates out of Dubai central. Richard has a beneficial interest in 417,226,971 shares. I don’t know Richard, he’s probably a nice chap, sadly the company he is running is massively over-valued. It’s a dog. The current SP is 0.5p. The market cap is £5,000,000, The question is on what? They’ve stated that they have total assets of £936,393. That figure is wholly miss-leading, and here’s why. The figure is made up of cash & cash equivalents (£108k). Trade/Receivables (£36,821). Investments held for resale (£384,537), which comes to circa £530k. The rest of the assets figure is made up of ‘hot air’ £406,000 of intangible assets. Remember this was as of 30 June 2015, so their cash position will be some what eroded as of 10 months further down the time-line. They are running on sentiment and close to bust.
The recent grandiose statement of the acquisition of Precious Metals International Ltd (“PMI”) and its wholly owned subsidiary, Black Sand FZE (“Black Sand”) in an all share transaction is yet another fantasy story being used to ramp up their share-price. Wishbone intend to give 480,000,000 shares for PMI at a price of 0.27p per share, ergo £648,000. A company that made a loss of £5,564 and has assets of £454 quid! Just slightly more than I currently have in my wallet! It’s a joke!
On a fundamental basis the actual value of Wishbone is listing value, £500k and assets £530k, ergo circa £1M. A shareprice of 0.10p. As for their Aussie assets, unless Richard and HotStockRockets, buy a pick and shovel and INVEST SOME MANUAL SWEAT, then you can right them off. Nil par, no value, zippo! Wishbone Gold are trading at 400% over true value. It should be noted that the last RNS from the company was yet another ‘brouhaha’ over getting into £2,000,000 of debt to keep the company afloat! Who is going to give Mr Poulden £2M? More importantly what is that £2M going to be secured against? The company do not have any thing to secure it! Unless you count the £454 quid in PMI assets….
Wake up. Sell and get out, take your profit and run. As sure as night follows day there’s a massive dilution on the cards here. Indeed, if they don’t place or suck in £2M in debt they will go bust.
With an insanely over-valued share-price it would be insanity for Wishbone to NOT take advantage and place immediately! That placing will be at a huge discount. Placing Ahoy!

Viva!
Dan
Dan
Sadly for the poor souls suckered into Andalas Energy (LON: ADL) by the $600,000,000 fantasyman, CEO Dave Whitby and his pump and dump gang, news on the current situation has and is being deliberately withheld. Andalas should have released an RNS on Friday 22 April 2016, explaining exactly what the situation was within their company. The readmission document should have been published BEFORE the 22 April 2016. The key word in the RNS of 26/10/2015 is ‘BEFORE’
If Sarah Wharry, the Nomad from Cantor Fitzgerald, and the Andalas Energy fantasyman Whitby, do not update the market by 4pm this afternoon, then this site will unofficially release the news. It is a disgraceful situation whereby their shareholders are being treated as nothing other than lemmings. Whitby, Brand UK their SPIN DOCTORS and Sarah Wharry have shown no regard whatsoever for their own shareholders. Tick! Tock!
Viva!
Dan