google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0

Tag: takeover

  • ‘The 3 Israeli’s.  The ADVFN Takeover Is On! £4?

    ‘The 3 Israeli’s. The ADVFN Takeover Is On! £4?

    As those that follow Guerrilla Investing will know, from my scribblings, in April and May of this year I predicted that a takeover of (LON: ADVFN AFN) was on the cards, being progressed behind the scenes and funded by an Israeli group of mega wealthy corporate elites, lead by the former ADVFN Director, Professor Yair Tauman, who increased his holding from 9.44% to 18.31%.  Then enter the arena his ‘bestest’ business buddy, Israeli Mr Ron Izaki who owns and manages the IGI Group: Izaki Group Investments. IGI is one of Israel’s largest and longest-established private real estate development companies. IGI hold 4.31% of ADVFN
    Unknown to most at the time was that those behind it had attempted to take control in 2015. That attempt was eventually fought off by the present board.

    TAKEOVER

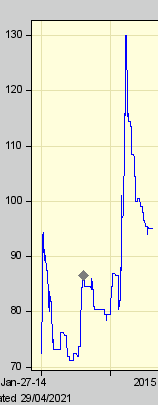
    For those that don’t know the history, it went like this. In 2015 an attempted ‘putch’ was launched, the share price went through the roof breaching £1.50p, as the group, posing as Sweet Sky Ltd and Shellhouse Ltd ‘Officially’ declared 25%, which most believed was closer to 40% through the dark arts of undeclared ‘other’ parties holding stock. i.e. An undeclared Concert Party. 
    FAST FORWARD

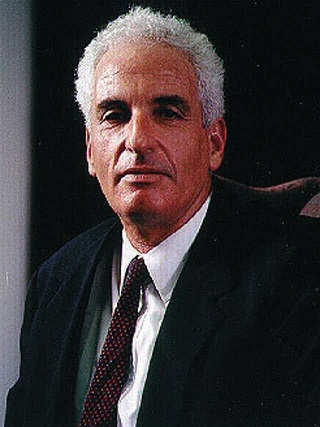
    Fast forward today’s TR1 from ADVFN disclosing a further 9.66% holding from yet another Israeli ‘Professor’ Dan Horsky. That brings their total declared holdings in ADVFN to 32.28% effectively swinging the Takeover Pendulum in their favour.  Make no mistake: That’s ‘a Concert Party’ which has gone over 30%. Market Rules dictate that they have to make an offer for the Company!
    In order to wrestle control away from the present board, to avoid a repetition of the costly legal dogfight that thwarted their 2015 ‘kick the doors in’ requisition the Israeli Group maybe ‘Knocking on the door‘ as you read this with an offer. That ‘offer’ will have to be at a substantial premium to the current SP of 73p. Sources indicate that £4ish per share gets them home and dry without the need for a Requisition, that would almost certainly end up in ‘legals’,. How high could the SP go over this week?£2/£3 anything is possible when you know the history….

    HISTORY

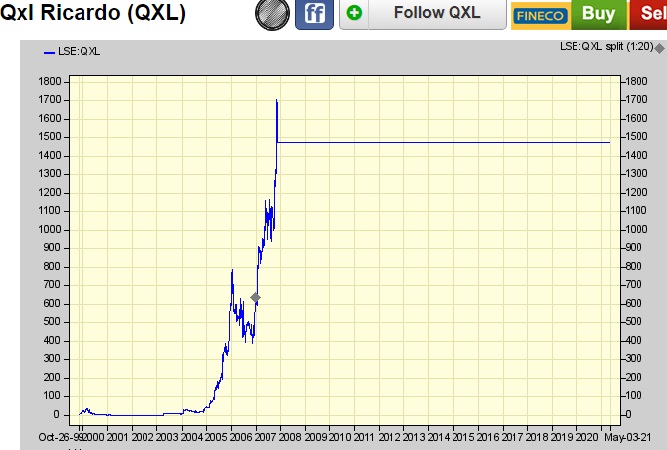
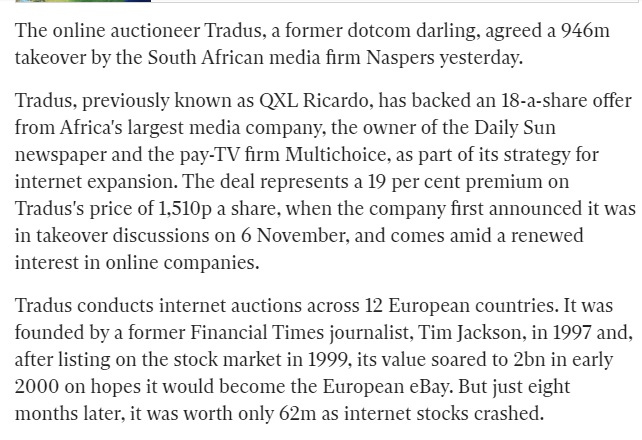
    The Israeli’s, as we say, have, ‘Got Form’ having previously taken control of a little known company called QXL, which changed its name to Tradus, which then went on to massive value rises, ultimately QXL/Tradus, was sold for a whopping £946M to Nasper.
    Horsky was born and lives in Israel. His worth is in the hundreds of millions of dollars. Collectively the group are probably worth billions Horskys’ career is a colourful one, to say the least, he’s taught and lectured the cream of Swiss banking talent, at among places, the prestigious University of Bern in Switzerland and has over 30 years as a professor of business administration, finance and banking..


    So there you go. It’s a takeover.


    Good Luck


    Viva


    Dan


  • ADVFN: Takeover Inevitable?

    ADVFN: Takeover Inevitable?

    In the wake of the ‘rumoured’, Israeli group front man, Ex ADVFN Director, Yair Taumans notification (TR1) that  doubled the holding to 18.31%.

    Can the present Board of ADVFN: (LON AFN) keep control of the company?

    That’s the question doing the rounds in the City of London as you read this. 

    Looking at the QXL history and the ‘contentious’ 2015 attempt at wrestling control of ADVFN, it’s almost certain, there will be further increases in holdings from both combatants in the fight for what the takeover group probably see as a potential lucrative cash cow that’s under-performed. After taking control of QXL , the sp was sub 1p eventually rising to a staggering £17, before the company was bought out for close to £1B, at £14+, in 2007. I’m sure the Board of ADVFN are aware of exactly who’s involved, what they hold, both declared/undeclared and who is supporting them. These are mega wealthy people and know the market inside out; Yair Tauman, is a highly respected, Professor of Economics at State University of New York, Stony Brook and the Director of the Stony Brook Centre for Game Theory.

    The conundrum is, will those currently trying to ‘kick in the front door’ cease and desist and knock on the front door? If so how will the present Board react? Rumours current are that there’s a shadowy concert party pulling the strings, through nominee accounts from as far away as USA, Israel, Cyprus, Switzerland and the Bahamas to name but 5 of the many locations I’m hearing.

    Those running the Company are duty bound, if approached via a ‘polite knock’ on the front door, to enter into negotiations. ‘Thems’ are the rules corporate and regulatory. If you’re approached then you have a duty as well as a responsibility to sit down and listen to the proposal. It’s as simple as that. Hammer out a deal. In the real world of business everyone is up for a deal. ADVFN and the Professor are no different.

    Prof’ Yair Tauman

    As it stands, I can’t see these people making the same mistakes as 2015. Both parties are corporate, business, savvy, both know that the other will not blink in a hostile takeover situation. But is that really in the best interests of shareholders?

    ADVFN could probably muster 25% to 30% of existing holders to keep control. But that would not be enough. If a requisition drops, which is by it’s very nature ‘Hostile’ then their only way of defeating the Israelis is via ‘legalese‘. As I read it, the interested party can call up or will soon be in a position to call up, over 40% of the votes…

    So, the value drivers at the moment are increased holdings TR1s from the Tauman group, as well as Director buys and option, warrant exercises by the incumbent’s. That should or could catapult the SP to between £1/£2. Of course if an RNS drops announcing ADVFN are in official takeover talks or a Requisition is RNS’d and these two are highly likely given the history. Hindsight, with a look at the meteoric QXL rise, then £4+ isn’t out of the question from a current share price of 63p. If I was either of the combatants I’d reach out officially and get in too talks. That’s the key here to it all.

    Make no mistake there’s a corporate battle being played out behind the scenes for control and the share price will rollercoaster higher.

    As always take care. Greed is the enemy.


    Viva

    Dan


  • ADVFN: The Battle For Control Has Begun! Takeover! The Israelis Are Back! £2/£3?

    ADVFN: The Battle For Control Has Begun! Takeover! The Israelis Are Back! £2/£3?

    Just a quick one:


    Get watching London Listed ADVFN , ticker AFN. 

    Today’s TR1 from ADVFN ex Director Mr. Yair Tauman confirms that the Israeli group that tried to take control of ADVFN in 2015 are back with a vengeance. Yair Tauman has declared an increase in holdings from 9.44% to 18.31%

    For those that don’t know the history, it went like this. In 2015 an attempted ‘putch’ was launched, the share price went through the roof, as the group, posing as Sweet Sky Ltd and Shellhouse Ltd ‘Officially’ declared 25%, which most believed was closer to 40% through the dark arts of undeclared ‘other’ parties holding stock.

    At one point requistioners were contacting ADVFN private shareholders trying to buy their holdings, requisitions were launched, the FCA became embroiled and eventually the battle for the Company was quelled as the custodians acting for the group; Bank of New York (Nominees) and Bank of New York Mellon decided not to proceed with its requisition for a general meeting, they advised their clients that they had gone about the takeover the wrong way, breaching numerous FCA/SEC regs. Ergo the plug was pulled. Victory, Clem Chambers. The SP at the height of the requisition went over 150p.

    What wasn’t known at the time was that this group had previously taken control of a little known company called QXL, which changed its name to Tradus, which then went on to massive value rises, ultimately QXL/Tradus, being sold for a whopping £946M to Nasper. https://www.independent.co.uk/news/business/news/naspers-946m-bid-agreed-by-tradus-765936.html

    So the history here looks like a re-run of the 2015 takeover of ADVFN.

    You can expect that todays news will be followed by more increases in SP and declared holdings with a requisition for a General Meeting. This could hit £2/£3 over the coming weeks/months as either party look to secure victory..

    The Battle has begun.


    Viva!

    Dan


  • Andalas Energy & Power. Take The Deal Mr Gorringe!

    Andalas Energy & Power. Take The Deal Mr Gorringe!

    Andalas Energy & Power (LON: ADL). What’s going on within and out-side of the company? It would seem that there’s a very slow tick up of the SP underfoot. News has been reaching ‘Yours Truly’ that Andalas are the target company of at least one and possibly ‘others’ who are sniffing around to take full Board control of the Company. I won’t go into each individual group as they may or may not be in direct talks with ADL. What I will do is disclose my take on one of the groups who HAVE made an approach (I believe pre or during Colter drill) and are in contact with some of the Major Share-holders.


    It could be about to hot up at Andalas Energy. Now the emphasis is on ‘could’. So I’d ask investors/traders to keep that word in mind. There’s reasons for that. The chief one being the corporate world of ‘wheels & deals’ doesn’t run to the time-line of you/me, it can get and does get snagged up in back-room compliance/negotiation. That is to say nothing is certain until it’s what’s known in corporate speak as ‘Inked. (Signed sealed & delivered).

    What I do know from my research is that a group have approached the ADL Board, seeking a corporate takeover via the introduction of $10M of assets/cash. It’s known as a ‘Plug & Play’ package, if that deal happened then ADL would have rocketed upwards, probably over 1p. For whatever reason/s those talks petered out but I can now exclusively reveal that those talks have been reignited with ADL Major Shareholders. Whispers are again surfacing that Major shareholders are now aware and have been approached for the 1st time by well-known successful corporates with a proven track record not only with the drill bit but with increasing SP value for their share-holders.

    Major shareholders were not informed by the Board of ADL on the first approach. I have an ‘idea’ of the names of those corporates having had many cagey conversations with various market sources. The asset/s from one of the groups are rumoured to be Cuban/Mexican. I can’t confirm that but what I can confirm is that predatory moves are almost certainly going on in the back-ground. At what stage they are and if they’ll ever come to fruition is as I said further up in this piece subject to ‘back-room compliance/negotiation’. Nothing is certain until it’s ‘Inked‘ .

    Target ADL?

    ‘Plug & Play as some will recall is what was used on a company called IRG which had a meteoric rise when the new board and initial investment/assets was announced. For a ‘plug and play’ to work any investment group have to find a relatively low value m/cap company £1-4M, to offer the financiers potential multiple returns on initial investment just as IRG did. ADL has a current m/cap of £1.5M , the listing on the exchange itself is worth £600/800K. Cash at hand is circa £500K. Ergo it doesn’t take much to realise why ADL are being targeted, either officially or unofficially. But ‘Target’ they are. Companies at shell value can, on a slither of good news spike, secondly there’s always predatory action in the back-ground that can also re-rate the shell. Hence why I took a ‘slug‘ of shares. Even on no news ADL will slowly tick up.

    So, bearing in mind how convoluted and difficult it is to predict with any degree of certainty the outcome of back channel discussions, I think it’s well worth a small punt.

    Take The Deal!

    As I see it the main sticking point to any deal getting Inked is the current Board who like all corporates don’t want to get off the gravy train unless their nest is feathered with downy £50 notes. I’ve tried to contact the CEO Simon Gorringe many, many times, he has thus failed/refused to make contact. Contact I might add with one of his small Major share-holders. That tells me that Simon is the sticking point to any deal. If you’re reading this Mr Gorringe, then do the right thing for share-holders. Get in-touch with the Cuban/Mexican Plug & Play group and take the deal!

    Worth a small punt!

    Viva!

    Dan

  • Exposed Optiva, Lenigas & Gunsynd.  Takeover Plot of Zenith Energy!

    Exposed Optiva, Lenigas & Gunsynd. Takeover Plot of Zenith Energy!

    ZenithLogoZenith Energy (LON: ZEN) are a cracking small oil and gas production company operating out of Azerbaijan, they have a main market listing, their CEO is a man called Andrea Cattaneo . They are currently producing 300bopd with cash revenues filling the company coffers on a daily basis. That production is set to triple in the coming months post work-overs. It could be over 1,000 bopd by the end of the year. They operate one of the largest onshore fields in Azerbaijan. What most investors/traders have missed is this; the ZEN asset base also holds an asset called Zardab. This asset was on it’s own producing 500bopd until the well collapsed. That well will be brought back onto production so in effect over the next 12 months ZEN could be producing close to 2,000 bopd, post successful work-overs and re-drilling of Zardab. This means that the share-price will undoubtedly have an astronomical rise and could hit the heady heights of 40p-50p. Why is this important? Read on….

    Many months ago I was offered to take part in the IPO listing in London. I declined. Why. I smelt a rat, the Optiva Securities/Lenigas rat to be precise. The Zenith broker. Today I put into the public domain exactly what Optiva have been up to and their attempt to orchestrate a ‘soft takeover’. Optiva are trying or where trying to assist David Lenigas and Donald Strang in taking over Zenith Energy. That is wholly unacceptable practice and flies against all corporate governance. They ‘advised’ that Lenigas be gifted a seat on the board of directors. This is an absolute disgrace. Brokers do not dictate who goes on the board of any company they broker for. Gunsynd (LON: GUN) ARE A MAJOR SHAREHOLDER in ZEN. Gunsynd is to all intents and purposes a Lenigas puppet company run by Donald Strang and Hamish Harris two of the Fatman’s Lieutenants. GUN have threatened a ‘corporate action’. I did email and try to speak to the Zenith head honcho Cattaneo many times pre & post IPO, I warned him of exactly what has now come to pass. Sadly he refused and ignored my advice. Not so much as a returned call just a few template email responses. Now that the sharks are circling and it’s out in the open. Maybe he’ll wise up.

    I have many sources in the city of London. Most are impeccable. One, who was in the Optiva camp, recently passed away. My sources on this are 100%. David Lenigas is after taking over Zenith Energy using Gunsynd and ‘other’ significant ZEN holders that he has influence over, as the vehicles to achieve  a board room putsch. Why is he after them? He knows the potential share-price upside is virtually nailed on by the increasing oil production. Optiva like all the Lenigas companies work out of Jermyn Street. They all piss in the same pot and cross pollinate information back and forth between themselves. The spy in the Zenith camp is a chap called Sasha, a nice kid actually, how do I know he’s a fifth columnist? It was Optiva that forced the Board of ZEN to employ him….

    The recent placing by ZEN was in my opinion an attempt to dilute the Jermyn St Mob. It was a smart move by the Board of Directors. However it may not be enough as the shysters see a 25p share-price as easy meat.  Andrea Cattaneo is no ones fool. You can’t do what he has done in Azerbaijan unless you are a smart cookie. He needs to grow some balls and take these shysters head on. First ZEN should give Christian Dennis (Optiva headman) his P45 and tell him to pick up Sasha on his way out of the company. Get another broker, one with integrity. It’s a dirty game Andrea, as I told you in my emails months ago where I warned you. But at least now you know exactly how dirty it can get and how right I was in those emails. If these fookers want Zenith then they should pay the going rate. 25p a share. Either put up or shut up.

    Zenith Energy are a super little oil production company. Lets hope they don’t fall into the hands of the Jermyn St Mob.

    25p target.


    Viva


    Dan


    N.B It’s with great delight that I give the Jermyn St Mob, Optiva Securities & the ‘Fat Aussie Share Ramper’ A.K.A David Lenigas and ALL his Lieutenant’s  a good solid kick up the arse. Once this is published they’ll be running amok phoning and emailing trying to plug the leaks. Stop getting pissed in Green Park and shooting your mouths off. These are the fookers who tried to fleece me of £52,500 in the disgraceful Lenigas Cuba fiasco. They told so many lies it made ‘Billy Liar’ look saintly… I got all my money back, but that’s another story once the NDA, Non Disclosure Agreement runs it’s course. And woe betide you Fatman when it does…. I bear grudges.

  • The Ascent Of Ascent. 2017 Will be Their Year.

    The Ascent Of Ascent. 2017 Will be Their Year.

    Ascent_LogoAscent Resources (LON: AST) as most genuine objective investors/traders know we here do not constantly pump out utter shite on an hourly basis. We watch, listen, research and get to know what is going on vis-à-vis the company’s we blog on or target. It can take weeks or months to form an opinion that’s because most genuine information isn’t in the retail domain, it’s hidden from view in the Corporate World. Not for the eyes of Retail Investors.

    (Hence why when we recently exposed Mkango Resources as a busted financial flush with a history of telling whoppers to our Canadian retail investor cousins, about their piss poor paper licences and their true dire financial postion, we were proved 100% correct. MKA and their shyster advisors ‘Dubious’ Dzubinski  told so many lies it was only a matter of time before financial gravity struck.  They placed after 6 months NOT 18 months which is what every man, jack and idiot were spoon fed and greedily swallowed said turd. The red faces are there for all to see and most objective investors know BMD was spot on. Mkango, Dawes, JubCapital and the hoards of P&ders  have been strung up for all to see as PROVEN LIARS. Which is why you should stay well away from company’s that lie to their shareholders. In another 12 weeks they’ll be after yet more cash).

    Not so Ascent Resources. I was negative on them for quite a long time particularly because of the legal shenanigans and the known market abuser, Christopher Potts, who had a position. Potts made a fortune from news of a proposed Cadogan takeover, one that never came to fruition.

    Not so know. Lot of rumours swirling around from my sources that their Slovenian gas asset/s could contain substantially more gas than first thought. The commercial supply of the gas to Croatia in early 2017 and rumours of yet several potential game changers coming to the fore in Q1 2017 finally convinced me that Ascent are  a turnaround play. I can’t report those rumours until they are firmed up’.  However I can confirm that my research/sources are more reliable than most. 99% that there’s truth to them.

    The present board are starting to get it right and are making all the right noises with the right moves. CEO Colin Hutchison has been in negotiations several times in 2016 on value accretive deals. That is 100% correct. Don’t be surprised if there’s some form of ‘input’ upon AST by Henderson Global. There’s major news in the proverbial pipeline for 2017.


    Eyes on. Hold for the news.


    Viva!


    loginDan

  • London Capital Group. Corporate Jackals. Vote NO at the EGM.

    revolutionI’ve never wrote a piece on spread betting tiddler London Capital Group (LON: LCG) before but feel it’s time investors became aware of the tricky situation they’ve now gotten themselves into. CEO, Charles Henri-Sabet (double barrelled surname to boot) and his backers at GLIO are between the proverbial rock and a hard place regarding convertible loan stock they used as they attempted to gain control of the Company in 2014. Sabet has been a disaster for shareholders. LCG have cratered by over 75%.

    LCG now propose raising approx £14m! See the RNS of the 21st July ( HERE) and don’t forget to have a good read of their last set of financials HERE An absolute litany of corporate greed.

     The trashing of the stock price to 5p set against the Convertible Unsecured Loan Stock (CULS) conversion price of 25p served to put GLIO Holdings Ltd and Sabet in a tricky spot re gaining control of the company (over and above the Board control). The proposal to issue new stock will result in circa 65% & 85% of the enlarged share capital at a price of 5p per share being in their hands. This is nothing but in effect a de facto takeover of the Company yet another cash and grab for the boyos. Screwing current shareholders. Recent results reveal net book value adjusted for intangibles was £8.2m – nearly 10p per share. It is an absolute shocking derogation of duty for non executive directors to wave through a Concert Party who are forking out a miserly 5p And how in the name of God has this got past the FCA? The deal also sees them issue a further potential 7.096m shares to GLIO for the “underwriting “ of the ‘takeover’ (depending on the amount not taken up in the open offer) as well as a further 18.65m “interest”” shares on the CLN redemption. What this proves is total disregard for all stakeholders ,other than themselves!! How has this got approved?

    There is no immediate need to raise capital and certainly not at such a piss poor price. The reasons (bullshit) being trotted out?  Growing revenues and a commensurate increased capital base requirement. WELL IF THE ‘REVENUES’ ARE INCREASING WHY THE HELL DO YOU NEED TO RAISE CASH?

    Against this background, the Company believes that its Tier 1 capital ratios should be strengthened so that it is able to take advantage of its restructured platform in order to grow and improve its trading results.”

    Running a business isn’t difficult, you don’t have to be a ‘Brain Surgeon’ to know that the best way would have been to wait until business has banked the ‘Growing Revenues’ ergo the share price rises and you can raise at a much higher price which is less dilutive. Common sense! The facts behind the capital raise just don’t stack stack up. It stinks. So what’s the reason/s? Maybe this?  “Trading in the second quarter, however, has been noticeably weaker due to a lack of volatility and concerns about Brexit, reducing clients’ propensity to trade”. Corporate codswallop! The NED’s should hang their heads in shame. Change is needed here.

    Sabet has no regard whatsoever for LGC SHAREHOLDERS the board is populated by yes men, lackeys! Genuine independent oversight does not exist. The board should resign. In the latter’s case, to simply put their name to what is a ‘take under’ at less than the current net book value is shameful. ‘Of course it’s par for the course’ with this board the recent admission that the LCG NED, Frank Chapman was UP TO HIS NECK in yet another ruinous company comes as no surprise. Mr Chapman was a non-executive director of ‘OF Holdings Limited’ (formerly Oxygen Finance Holdings Limited until 5 May 2016), when it was placed into administration on 25 February 2016. According to the joint adminstrator’s statement of affairs dated 11 March 2016, the company as at that date estimated a deficiency to creditors of approximately £342,000. The estimated total deficiency as regards members was approximately £352,000′ What a shambles but it is indicative of the wholesale disregard these fookers have for their own share-holders.

    VOTE NO TO ALL RESOLUTIONS ON THE 6TH JULY.

    Issuing stock below their nominal value requires court approval. The EGM is to be held on the 6th July 2015. The scumbags need 75% of the votes on the day in order for the resolutions to pass and the company to be gifted to Sabet and GLIO at a massive discount to book value.  If these guys want LCG then they should be willing to pay a premium over net book value of 10p. 12p at the very least! 

    It’s up to you to kill off this scandalous EGM.

    Vote ‘NO’ to all resolutions.


    Viva!n


    Dan


  • World Exclusive! shareProphets renamed shareProfits!

    World Exclusive! shareProphets renamed shareProfits!

    Freespeech!

    I’d like to take the weekend break to personally thank those who have emailed, phoned and left supportive comments on confronting the liars and bullshitters from shareProphets or as I now refer to them shareProfits. The crony capitalists masquerading behind the banner of freespeech and liberty just can’t help themselves. Another foot in the mouth of freespeech will be revealed further down in my article.

    Let’s have a big cheer for the witless Ben Turney & shareProfits who just can’t seem to understand that by publishing ramping NWOG shite on shareProfits that THEY are also culpable.  Tom Winnifrith, is spending some time with his father who isn’t in the best of health. I hope Winnifrith senior and TW have a great time as a father & son should have. I wish them all the very best. I am not here to destroy personal relationships or attack those that are in a weak, physical, emotional state. I would never kick a man when he is down. 7 Day respite for TW.

    The New World Oil & Gas (LON: NEW) Bear squeeze disaster that exploded in the faces of the BB lemmings, that poor out of his depth ‘Safehouse’ Turney, had lead them too on the 11th of May 2015, when the open offer RNS grenade blew up in the faces of the farcically named NWOG action, is entering a critical phase. Come the 19th May the egm vote will be held. No one knows how that vote will go. But I can assure you all of one thing our man Chris Oil and myself and the team helping/advising the Williams family will be on the winning side.

    Now let’s just get one thing straight, Turney has been lead by the nose by those who have been running the naked short. Those pulling the strings are perfectly entitled to do so. It is after all just business they know who they are and they know I know who they are. I wish them all the best. Our aims are not at odds etc.

    What I find reprehensible is that I have emails from the NWOG action group that specifically states that they ‘NWOG’ are in it for? ‘FINANCIAL GAIN’. Turney knows that the sword of Da(n)mocles  hovers above his witless head. Hence Turneys tweeting that he’s not selling any shares in NEW. Tweets that only started AFTER I made him aware of the damning emails in one of his pestering damage limitation phone calls/emails. I know that TW does not know of this emails existence. So TW is not on the hook for it. So much for the masquerade that operates behind the smoke-screen share-holder action group. It’s a get your greed in first play! Farcical.

    Now as mentioned earlier in this piece re ‘ the Freespeech & Li(e)bartarians operating out of shareProfits.  Recent emails from Mr Ben Turney asking for what? The removal of my articles exposing him for the LIAR that he is. With an inferred threat of?  Legal action! So much for freespeech! pmsl….

    “See you in court Bitchesz”


    Have a great weekend.


    Viva


    Dan

google.com, pub-7842875684800919, DIRECT, f08c47fec0942fa0
Verified by MonsterInsights