A major indication of just how Sound Oil (LON: SOU) see their future dropped today via an RNS. A predatory takeover paper offer for the distressed and shockingly managed (into the dirt) Antrim Energy (LON: AEY). You’ll all know that I am a big believer with a large personal stake in the Company. I have skin in the game. I keep telling investors that the SOU story is one of success upon success, since the boy Parsons, took the helm he and the team have turned them into one of the best AIM oiler plays of recent years. Cornerstone investors, producing assets, cash in the bank, big exploration play and a flagship gas discovery (Nervesa) about to come on stream. Not forgetting that they’ve admitted they are in talks with a Global International Oil & Gas Company regarding a Major farm-in which could lead to a creeping full blown takeover at many times their current SP.
You’ll all recall that Antrim were at one point capitalised at £250,000,000 with solid production from their Causeway asset. The board ran up huge debts on Causeway, broke all their banking covenants, Credit Suisse called in the debt and hey presto the Canadian based Board flogged Causeway in a forced firesale. To cut a long story short Antrim ended up losing Causeway for a pittance so that the Board could keep lining their own pockets. Antrim are now basically a one asset operation quasi shell valued at approx. £5 million. 90p to 3p what a ‘performance!’ If only the Sound Oil team had been in charge then I can guarantee that Antrim share-holders would be sitting pretty on a hefty value accretive investment many, many times its current value. Instead of holding crabs.
This is a great deal for Antrim shareholders as they get access to a balanced portfolio in Italy, production and exploration; Good management, cost synergies (Out goes the failed BOD Hooray!) and a credible growth story with a possible take out of many multiplies of the current SOU share-price; 10.75p. How does 60p ‘sound’ to Antrim energy share-holders? Because folks that’s what the potential gain is on Sound oil. The Offer for each Antrim share, 0.3198 new Sound Oil ordinary shares values each Antrim share at 3.44p. This values the entire issued share capital of Antrim at £6.35M.
+ Takeover of Antrim!
As for Sound they pick up a high potential exploration asset in Ireland (diversifies pre Badile outcome) and over £10M in cash, all for just over £6M worth of paper (about 13% of the enlarged company). It’s a win, win deal for ALL stakeholders.
Take a good look at Antrim’s management. Over the past 2 stretch, they’ve done nothing but destroy value for their shareholders through miss-management. When a Company are trading below cash value after running the sp into the dirt, then you know that it has failed miserably. President and Chief Executive Stephen Greer, ‘resigned’ his position then immediately ‘assumed’ the role of Chairman of the Board of Directors. (Stephen Greed!) Here’s a question for AEY shareholders. How much cash did Gree(r)d get from AEY upon his resignation? Was it 1 years’ salary? 2? 3? Because I can tell you this he got a hefty settlement! Now he gets another chunk of the Antrim cash as the Chairman! What an absolute disgrace.
The Antrim Corporate troughers whose egos destroyed Antrim, have failed to respond to the Sound Oil offer, are the very same who f**ked up the Company for their own shareholders. While raking in millions upon millions in fees for themselves. They live in Canada! They’re detached from their own share-holder base. Proven corporate failures only interested in lining their pockets with what little money is left.
The combination of Sound Oil and Antrim as an entity will have a nice balance of assets, be focused entirely on Europe while being well funded and should be interesting to institutions given the increased scale. It’s a win, win deal for all stake-holders. Consolidation is in the air I expect that Antrim are not the only company that Sound are targeting. There’s more to come. Watch this space.
As most know we do not give buy, sell or hold recommendations on Guerillainvesting, much preferring for people to research for themselves to make up their own minds. However rules are there to be broken. If confirmation was ever needed for a stock to be in your portfolio then todays RNS was it. Buy SOU up to 16p and hold.
Sound Oil (LON: SOU) have been quietly going about doing the business in Italy. The share price hasn’t really done any thing other than mainly stay static. 10.5/11p. It’s actually maintained a stable holding pattern considering the oil price has plummeted, while news has been sparse. The strength of the Company fundamentally and asset wise is reflected by the stability in the share-price. Every thing is now lined up. Cornerstone investor, two producing assets, cash revenue coming in, Italians (ex-ENI) all in place on the Board, Italian bureaucracy, streamlined, High net worth’s involved, Nervesa about to be drilled, Cash in the bank, basically debt free. Lot of maneuvering has gone on to get Sound oil to this place in time. Lift off is here.
When I say ‘sparse’ I mean the Company are deliberately tight lipped. Always a sign that they’re sat on price sensitive news and don’t want a leak to ‘outside of the tenters’ such as yours truly. A communications lock down means they’re ‘nervous on Nervesa.’
About to go ballistic
There’s a lot of news about to come through as they gear up for what the Company describe as ‘an exciting period of back-to-back drilling’, which commences with site operations at Nervesa in a matter of a few weeks or two. News has reached the blog that all is on track for a major announcement over the coming week/s. Just what that is, isn’t known. But it’s almost certainly good news, bearing in mind that the flagship asset, Nervesa is about to go ‘operational’. Once this is announced then it’s game on for the sp. It will begin to climb. I expect the sp to double in value from where it currently stands. Then we have news on the exploration play that is Badile. A massive gas play that would catapult Sound oil into the arms of a major international oil company, never to be seen again. Gone, taken over for the good of Italy.
I’ve been trying to get an interview with the boy Parsons (CEO), the man’s a difficult fish to land. Particularly as he’s a frequent flyer, flying back and forth across Europe. Last spotted having a cappuccino with an Italian energy minister. We’re not supposed to know that! It’s no wonder that Continental Investment partners (Sounds’ ‘cornerstone Investor’) have agreed to throw more cash into the hat via one of their affiliated partners Greenberry S.A. It’s money for jam for them. They know (Unlike most) that they’re going to get a hefty return on the investment. Nervesa remains a Major project for Sound Oil with an estimated NPV10 of circa US$66,000,000 million (100%). Which will probably rise.
Tight lipped.
I’ve been keeping my eye on Italy news wise. The Italian oil and gas permitting process has now been cleaned up making life a lot easier re’ the permitting process. This was announced back in late August of this year by their Prime Minister.
Remember Nervesa is a huge gas discovery, once it comes on stream the sp should be transformed. It can only go one way. UP↑. Even as the oil price struggles Sound will reap huge benefits from Nervesa which is as those in the know know, gas, which is as those in the know know, highly sought after in Italy. Premium prices being paid.
Not so ‘tight lipped’
According to one recent article “Italy is the new Texas.” With over 40 small to middle oil companies on the verge of unlocking proven oil/gas resources. Sound Oil being one of them mentioned in the same article as? ENI!
For all those familiar with the Sound Oil story here’s a quick update.
There’s a Swiss clock ticking over at Sound Oil (LON: SOU) Hot off the press and following on from the James Parsons & Director Luca Madeddu UK private investor share-holder get together, after their successful presentation at the 67th Oil Barrel, news is coming through on BMD’s black telephone that there’s a secret, yes secret, private international investor presentation in the pipeline (at the request of an Institution) to be held some where in Europe. It’s all very ‘hush, hush’. So keep it quiet. We don’t want questions raised such as? ‘Why are international investors desperate to get there Swiss franc into Sound Oil just before a potential official farm-in RNS? Do we?
These are not UK investors these are Swiss by birth. Are they private Bankers, Chocolatiers’ or makers of Swiss army knives? We don’t know, but what we do know is that It would seem this could be tied to an impending big news release on a potential International Oil Company farming-in to the huge exploration play that is Badile. This farm-in could be a Company Maker and when announced will push Sound oil stock like a juggernaut
I really can’t understand how investors are still remaining on the fence re’ Sound Oil (LON:SOU) who once again have just pulled a major financial rabbit out of the hat. Sound confirmed today that they have signed ‘non-binding’ terms on a €7mln reserve-based lending facility to fund its 2nd well on the Nervesa discovery, onshore Italy. Note the emphasis on “discovery”
The proposed deal is being tabled by Greenberry SA, an affiliate of Continental Investment, Sound’s cornerstone investor, who investors may or may not recall paid a huge premium themselves to grab a 15.48% stake in SOU.
Sound says the loan, which ‘carries a 5% annual coupon, fully funds Nervesa going forward, allows it to retain its cash balances and offers a more economic and less complex alternative to a proposed farm-in deal. Now what this means is that the Niche Group farm-in has become basically irrelevant. It further strengthens the investment case that the Company are continuing along a path that will lead to a potential financial bonanza for those that can stay the course. Maybe this is why their Major Institutional Investor Continental has pushed Greenberry forward to take away any doubt re Niche providing funding for Nervesa. Remember Greenberry are an affiliate of Continental. Ergo Continental MUST be extremely confident on the returns they will make from these deals.
As part of the deal Greenberry get a 4% royalty on gross revenues from the Nervesa discovery, while an arrangement fee (And this is a very interesting point) will be paid via the issue of 3.9mln shares at 16p each (25% premium to Friday’s close).
The boy Parsons said: “This loan will be the second major investment by our cornerstone institutional investor and demonstrates the value of our flagship asset, Nervesa, which will achieve first gas in 2015.”
Just as an aside I was going through the RNS lists on ADVFN when it struck me that each and every one of these RNS’s, just by their headline, gives an accurate picture of exactly what is going on. http://uk.advfn.com/p.php?pid=news&symbol=L%5ESOU
It looks to me that the goose is being fattened up for some form of major farm-in or takeover. Which is why I will be listening into tomorrows Investor Conference Call, then making my way down/up to the big smoke for a tete a tete with the Company who are presenting at the 67th Oil Barrel Conference in London on the 25th September 2014. There are a (burgeoning) group of Private Investors & City bods who’ve managed to organise an hour with the Company at The Jugged Hare 49 Chiswell St, London EC1Y 4SA from approx. 11.40am for a general face to face chat.
Should be interesting. It just keeps getting better…
As you all know I am a big fan of Sound Oil (LON:SOU)
I was expecting to take part in their Conference call tomorrow but news from the Company is that it’s been delayed until 24th September which coincidently is 24 hours before Sound present at the Oil Barrel Conference.
I will be attending the Oil Barrel & have with Doctor Holiday from the http://docslaymanschatter.blogspot.co.uk/ prescribed a 60 minute private investor tete a tete with the Sound oil team for 11.40am. I will be speaking to the “Boy Parsons” in my official capacity as “I hold a large chunk of SOU stock”. Tell me it’s going to treble!
These opportunities do not come along very often so I’d urge any one who wants to get ahead of the game on SOU to Email: [email protected] to be added to the meeting list.
Now far be it for me to speculate why the attention of Sound oil needs to be somewhere else tomorrow but I do believe that there’s some good news in the pipeline which has coincided with the Conference call. There is a whisper that we will get some form of “Good News” what this will be is any ones guess. Farm-in? Farm out? Another major institution coming on Board, ENI, Edison or some other Major taking a piece of SOU?
We just do not as of yet know. One thing is for sure there’s an RNS on the way.
As promised we’ve tried to keep sourcing info’ on some of the Companies that we’ve had fantastic gains on over the last few months etc. Next up Sound Oil (LON: SOU).
At the moment it looks like the SOU sp is in a holding pattern. No real movement either way at 12p ish. September could be a busy month for the Company. It’s been bandied around online that the CEO has been on his holidays and is now back progressing the Company. There’s plenty going on in the business behind the scenes, what with Nervesa approvals, Niche farm in, Badile farm in & whispers of Laura farm-in etc. We do know that, regardless of what SOU refuse to confirm or deny, that they are in talks with at least 2 Major oilers, on farm-in & potential takeover should they come up trumps on Nervesa, Badile, Laura etc.
I did actually hear that some form of ‘chat’ with Rockhopper Exploration (LON: RKH) may have gone on a few weeks ago. How true this is? I’d say 50/50. Recent news has included, the Badile land purchase & long lead items, Nervesa long lead items & well head purchase, Letter of intent with Drillmec Spa for the exclusive use of an AHEAD 375 Drilling Rig in Italy for both the SMG and Laura wells, and first gas at Casa Tiberi. This points to a Company going in the right direction.
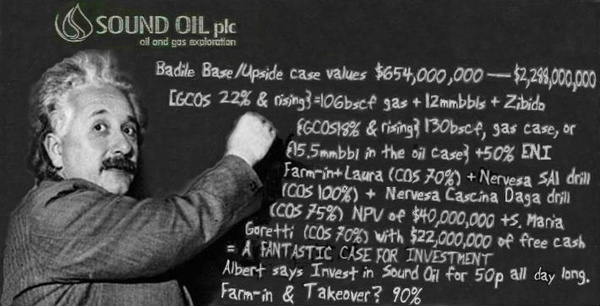
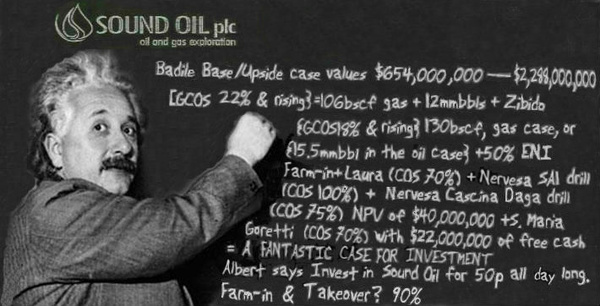
Take a good look at the Einstein Equation pictorial. Therein lies the answer to the question we are all asking; ‘How high can they go on more positive news?’ It really is a question of perception for each individual investor. We know that Takeovers or farm-ins of Companies with world class assets, always come at a premium to the current share-price. There are many different schools of thought. Takeover; 60p, 100p, 40p, 50p, Farm-Ins; 25p 20p, 30p, 18p. One thing is very likely, they are going up towards 20p this year.
Do not be fooled for 1 minute by the Company line; ‘The aim is to make Sound Oil a footsie 250 Company’ This will never happen. They will, subject to continued success, be swallowed up.
Logic should dictate your move here. Hold for Farm-In & or Takeover News in 2014.
Quiet week this week. But it’s going to hot up soon enough at Lenigas & Oil! Fantastic story developing. Eyes on UKOG!
Empyrean Energy (LON: EME)
Released a strange one this week. It is launching a review of strategic options open to the Company to maximise value for shareholders. They’ve basically called Takeover without any takeover actually occurring. They’ve put the whole company up for sale! You can read the RNS HERE
Faroe Petroleum (LON: FPM)
Duster! Centrica-operated Butch South West exploration well 8/10-6S no hydrocarbons were encountered. Oil strike! The Bue side-track well (6406/12-3 A) was drilled to a depth of 3,656.5 metres below sea level, 2.1 kilometres north east of the Pil discovery well 6406/12-3 S. The objective was to investigate the extent, thickness and reservoir properties in the Middle and Upper Jurassic reservoirs in the Bue prospect and to establish the pressure regime and hydrocarbon/water contact. The well encountered an 18 metre hydrocarbon column in reservoir rocks of variable quality. Pressure data indicates no communication between the Pil and Bue discoveries and Bue has therefore proven a separate accumulation of hydrocarbons. An extensive data acquisition programme was carried out including a fluid sample and the operator’s preliminary estimate of the gross size of the Bue discovery is between 6 and 25 million barrels of recoverable oil equivalent In addition, following the Pil side-track, which encountered a gross hydrocarbon-bearing reservoir section with approximately 80 metres of oil in the Upper Jurassic reservoir of the Rogn Formation, the operator of the licence, VNG, has advised the partners of an updated gross recoverable resources range estimate for the Pil discovery of 72 to 172 mmboe (18 to 43 mmboe net to Faroe), up from a previous gross recoverable resource range estimate of 50 to 170 mmboe.
Fastnet Oil & Gas (LON: FAST)
Announces that its wholly owned subsidiary Pathfinder Hydrocarbon Ventures has entered into an amended exclusive option agreement with Oil and Gas Investments Funds, in relation to eight Exploration Permits comprising the Tendrara Lakbir Petroleum Agreement onshore Morocco. Following substantive negotiations with its partner OGIF, Fastnet has secured improved commercial terms from those previously announced on 29 May 2013.
Forum Energy (LON: FEP)
A UK incorporated oil & gas exploration and production company confirms that the Philippine Department of Energy has granted the Company’s request for an extension to the second sub-phase of Service Contract 72. The deadline for completion of the second sub-phase, comprising the drilling of two appraisal wells, has now been extended by one year to 15 August 2016; Further details regarding the Company’s plans for SC72 will be made in due course, as and when appropriate.
Frontera Resources (LON: FRR)
Announced that it has begun the start of a new drilling campaign at the Mtsare Khevi Gas Complex in the country of Georgia. Location construction for well #32a will commence shortly and drilling is expected to commence during the month of August. The well will take approx. 15 days to reach total depth. Well #32a is planned to be drilled to a depth of approx. 400 metres and is designed to continue to explore and expand the identified gas potential associated with the Mtsare Khevi Gas Complex. Gas production operations have continued since commencement in April and are delivering gas to Georgia’s national grid via the Company’s gas gathering/processing facilities and associated 14 kilometer transportation system. This system accommodates gas production at a planned rate of approx. 2 million cubic feet per day of gas.
Ithaca Energy (LON: IAE)
A production update following the end of the second quarter of the year came this week. Average pro-forma production in Q2-2014 was approximately 14,400 barrels of oil equivalent per day (“boepd”), 94% oil, including the contribution from the assets being acquired from Sumitomo Corporation. This performance is in line with the Company’s pro-forma 2014 production guidance range of 13,500 to 15,500 boepd.
Leni Gas & Oil (LON: LGO)
It’s just going to get better and better for David Lenigas & Neil Ritson at the LGO Trinidad drills! The fourth of its planned Goudron development wells, GY-667, was successfully spudded yesterday at 1530 hrs and is now drilling ahead in the Goudron Sandstones. The well is being drilled as a deviated hole from the same well pad as used for the recently drilled wells GY-665 and GY-666. Well GY-667 has a planned total depth of 3,600 feet true-vertical depth (equivalent to 3,840 feet measured depth) to a bottom-hole location that is approximately 590 feet south east of the surface location. The primary target of this well is the Gros Morne sandstones, the top of which are anticipated at a depth of approximately 2,180 feet TVD. The well will also investigate the reservoir potential of the Lower Cruse at this location. Separately, final approvals have now been received for the construction and installation of a new 2,000-barrel sales tank and construction contracts have been awarded. The new tank will be installed at the Goudron Field’s oil sales point at Tank Battery Station 134 and will be adjacent to the two existing sales tanks increasing total daily export capacity equivalent to approximately 2,750 barrels of oil per day. It is anticipated that the new tank will be commissioned to coincide with the completion of the four wells being drilled on the current well pad; of which GY-667 is the third. Negotiations for a second drilling rig are actively being progressed with a variety of different options emerging. It is planned to retain Well Services Rig 20 for at least a further six wells and no decision has yet been taken on the choice of the second rig.
Mosman Oil & Gas (LON: MSMN)
Couple of RNS’s this week. Latest progress on its drilling programme at the Petroleum Creek Project, New Zealand. Crestal-1 was drilled to 75m and 7 inch casing run and cemented. Drilling continues and on 6 July had reached a depth of 100m. Oil shows (fluorescence) from 55m to 70m and 80m to 95m have been encountered. Rock samples under ultra-violet (UV) light show fluorescence indicating hydrocarbons on rock cuttings circulated out of the hole and separated from drilling fluid (mud) by screens. These rock samples are collected as representative of every 2.5m of hole drilled. If there is no oil on the sample then there is no fluorescence shown in UV light. ****These standard site tests are useful qualitative indications and will be followed up with additional work, including wireline electric logs and flow tests before any technical and commercial significance can be determined**** Therein the stars is the truth of exactly what’s going on here. You have been warned. Second RNS Crestal-1, oil shows have been identified throughout the Cobden Limestone from 158m to 173m. (I’d hardly describe oil shows from 158m to 173m as “Through out the Cobden limestone.”) John W Barr, Executive Chairman of Mosman commented: “It is important to put our progress into context as this positive news is the first step of the drilling programme which will be followed by the appraisal process. The next stage of which will be to carry out flow tests, additional seismic acquisition and processing work, and then complete the economic modelling required to determine commercial viability of our wells, which as previously announced is anticipated to take several months.” Several months? You have been warned!
Providence Resources (LON: PVR)
Provided took a kick in the goolies this week. An operational update on activities in FEL 2/04, FEL 4/08 and FEL 1/14, which are all located within Quadrant 35 in the northern Porcupine Basin. Capricorn Ireland Limited (38%, Operator (wholly owned subsidiary of Cairn Energy (LON: CNE) operates these licences on behalf of its partners, Providence Resources (32%), Chrysaor E&P Ireland (26%) and Sosina Exploration (4%). The licences, which cover an area of c. 2,000 km2, are located c. 175 km off the west coast of Ireland in water depths of c. 400 metres. The Operator has advised that the Spanish Point appraisal well will not be drilled in 2014, as previously planned. Extensive delays in the refurbishment of the Blackford Dolphin drilling rig which had been scheduled to drill the well, mean that drilling operations would not be able to commence until at least October, thereby putting the Spanish Point drilling operations into the winter period. Accordingly, the Operator has advised that the contract with Dolphin for the Blackford Dolphin has been terminated and tendering for another rig to carry out the planned well operations in 2015 has commenced. Separately, the Operator has confirmed that, subject to regulatory approval, a large 3D seismic acquisition programme over blocks 35/13, 35/14, 35/15, 35/18 and 35/19 in FEL 1/14 will go ahead this summer.
Roxi Petroleum (LON: RXP)
Hit the oily stuff this week with news of a discovery at its flagship BNG asset. The BNG Contract Area is located in the west of Kazakhstan 40 kilometres southeast of Tengiz on the edge of the Mangistau Oblast, covering an area of 1,561 square kilometres of which 1,376 square kilometres has 3D seismic coverage acquired in 2009 and 2010. Roxi has a 58.41 per cent interest in the BNG Contract Area. Deep Well A5 the first deep well on the BNG Contract Area, with a planned Total Depth of 4,700 meters is targeting principally the middle Carboniferous formation at 4,390 meters of the South Emba sub-basin. Oil and gas shows have been detected at a depth of 4,332 meters. After the completion of clean-up work to deal with the oil and gas shows encountered, core samples will be taken to determine the oil bearing horizon. News also came today of a licence extension and operational progress at its Galaz asset. Roxi announced the extension of the licence at the Galaz Contract Area for a further two-year period to 14 May 2016. The licence has been extended on the current pilot production basis, although at the request of Galaz LLP may be converted to a full production licence. As previously announced Roxi Well NK-31 has been spudded and is to be drilled to a total depth of 2,500 meters targeting the Middle Jurassic. The well is expected to reach Total Depth by the end of July 2014. It is being drilled on the main Contract Area. Drilling has reached a depth of 2,350 meters without incident. Core samples taken between 2,070 and 2,079 meters in the Karagansaisky horizon contain an interlayering of argillite and conglomerates.
Sound Oil (LON: SOU)
Has issued shares in respect of the first equity tranche of the £14 million institutional funding first announced by the Company on 25 April 2014. Following receipt of a cash payment of £1.86 million, the Company has issued a total of 23,212,500 new ordinary shares in the Company to related parties of Continental Investment Partners S.A. The issue of the New Ordinary Shares represents the first of two tranches of the equity issue associated with the institutional funding. The remaining equity tranche, totaling a further £5.14 million, is expected to complete during July 2014.
Victoria Oil and Gas (LON: VOG)
Updated on its Logbaba gas supply operations in the industrial port city of Douala, Cameroon, operated by wholly owned subsidiary, Gaz du Cameroun S.A. The announcement is the first update which includes supply to both thermal and gas fired electricity generation customers. Much to lengthy an epistle for the round up. Click HERE to read it
 Empyrean Energy (LON: EME)
 Mosman Oil & Gas (LON: MSMN)
 Sound Oil (LON: SOU)
 Victoria Oil and Gas (LON: VOG)
